Ten Billion Dollars Spent, Still in Excel: The Office of the CFO Is Ready for Its Solution Era
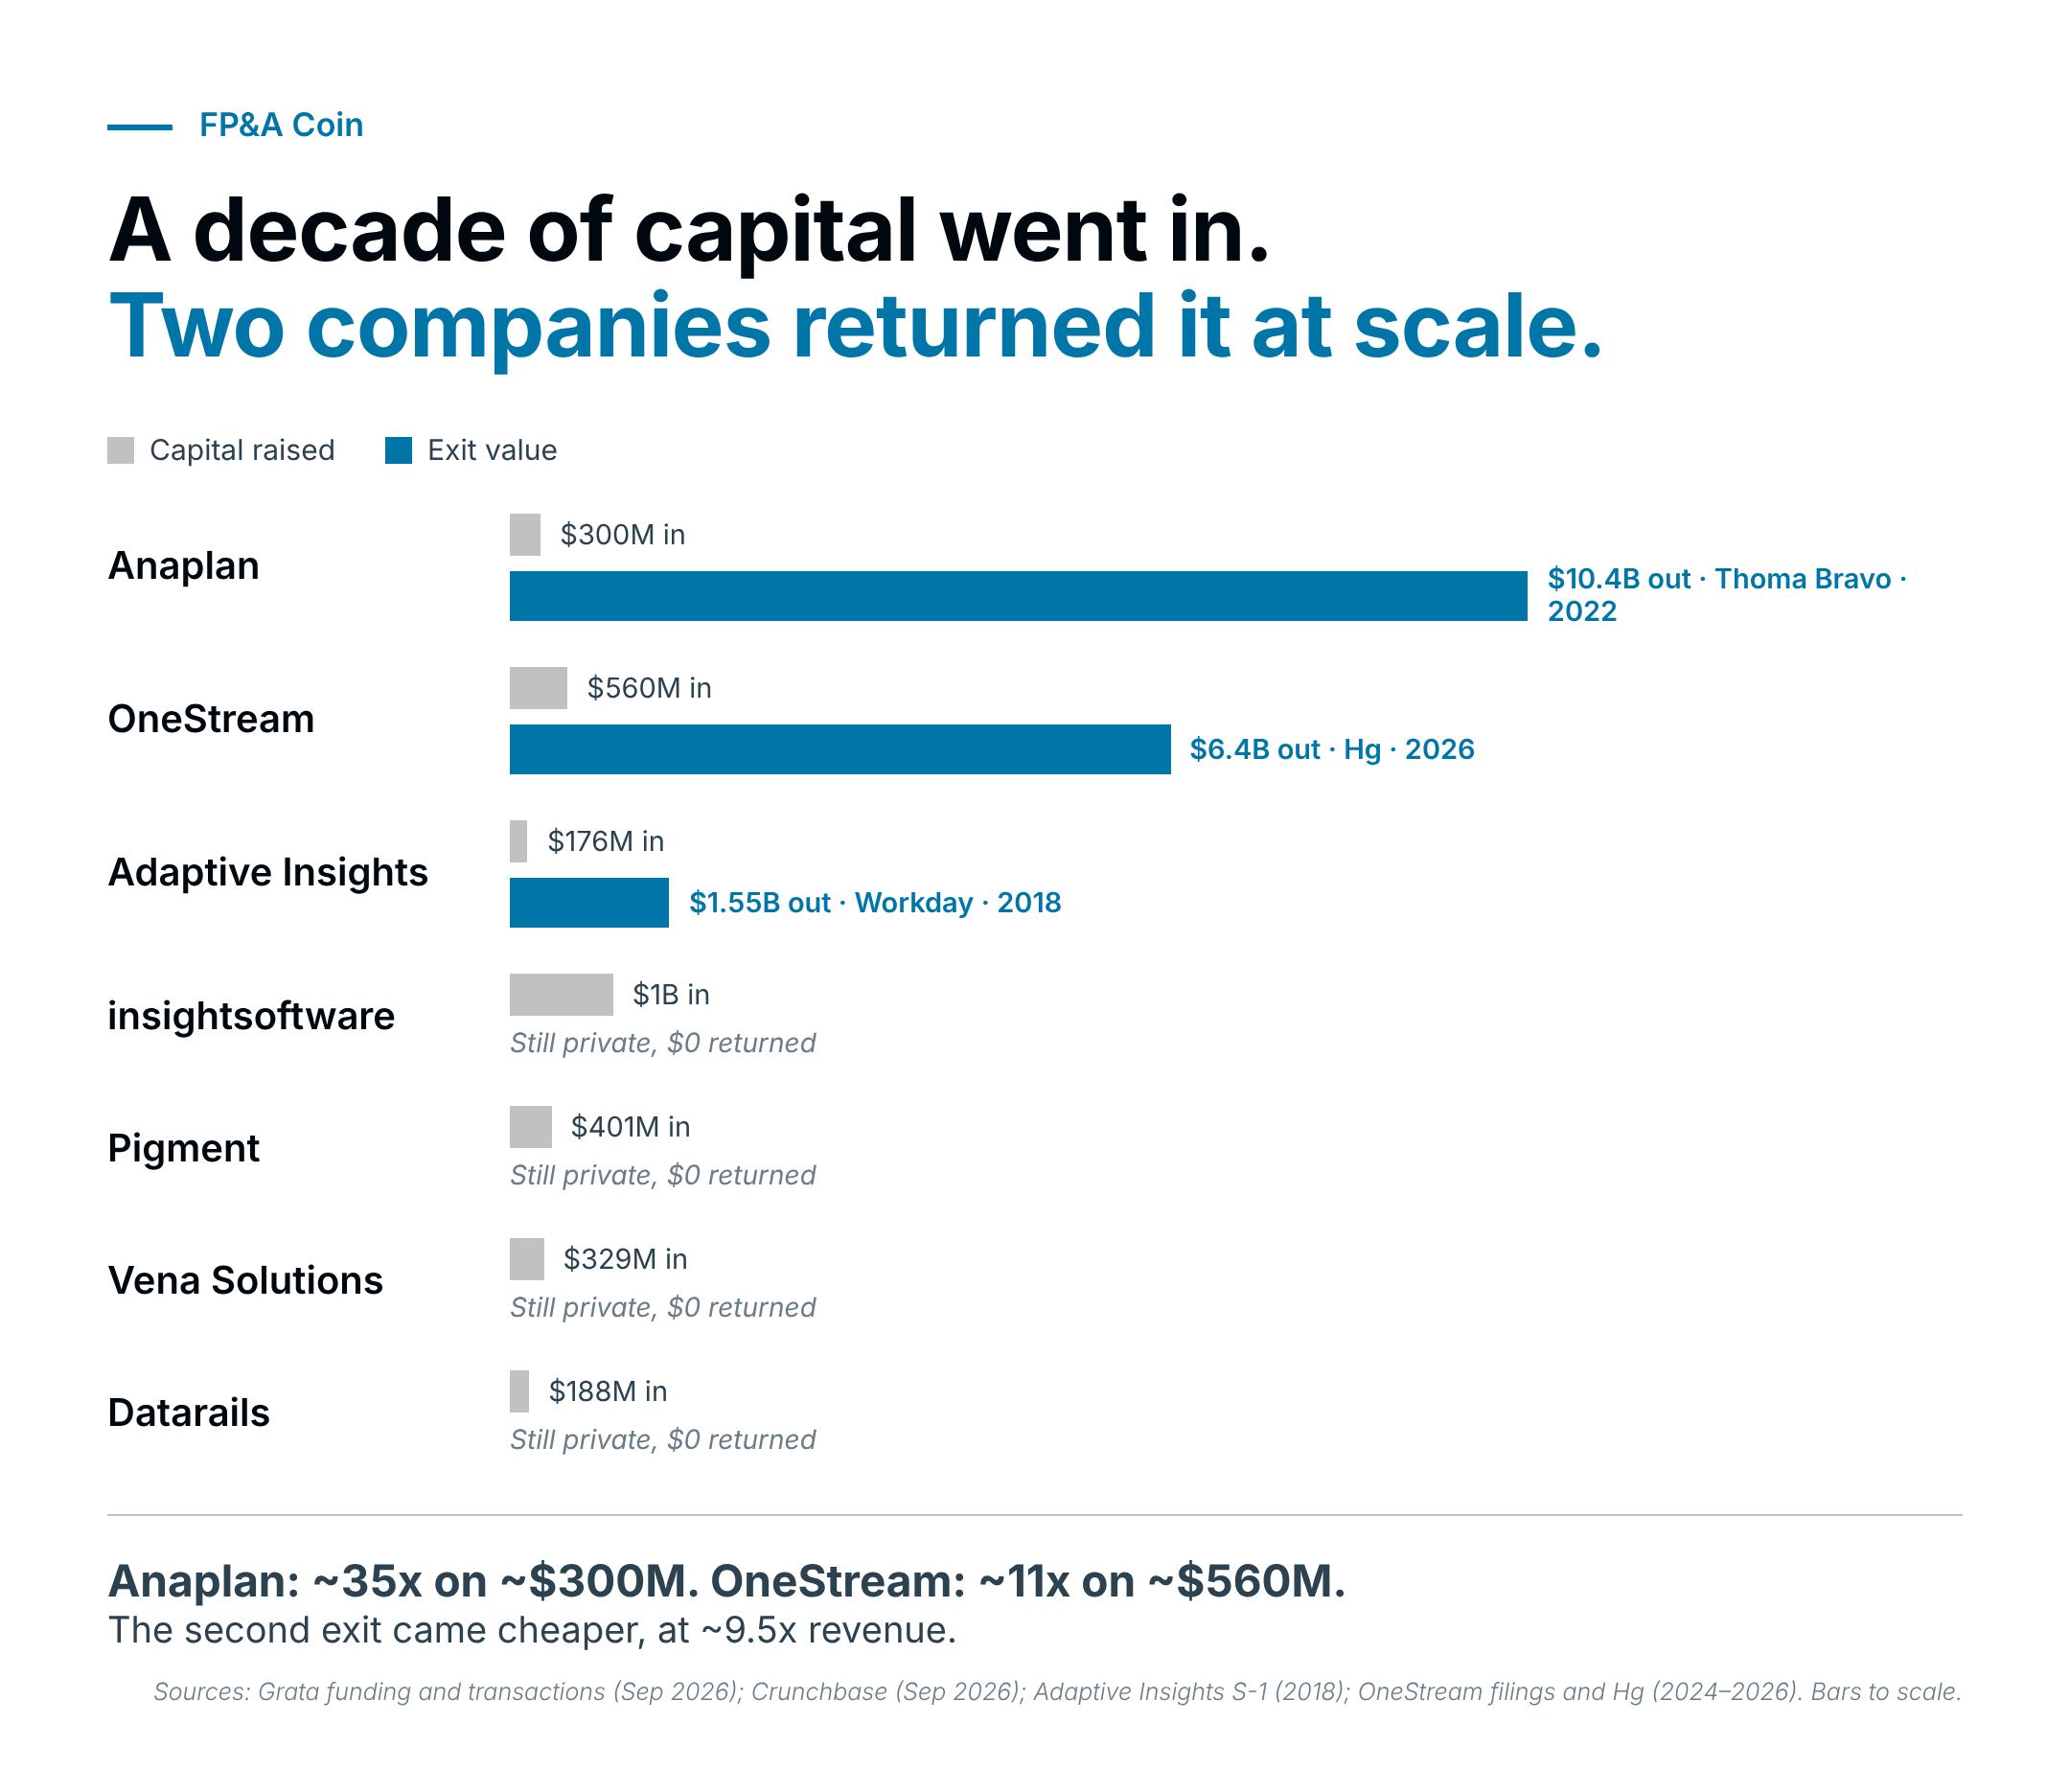
A decade of capital went into the CFO's software stack: more than 45 platforms invested in by venture and private equity, but only 2 premium exits. Money was spent on software and hours.
In 2027, will the customer finally buy the outcome, not the tool?
I track backoffice deal flow every day: 2K+ DealNet signals and 349 backoffice deals so far in 2026. Three markets I covered this fall, FP&A, ERP and backoffice solutions, look like separate stories. They're one story.
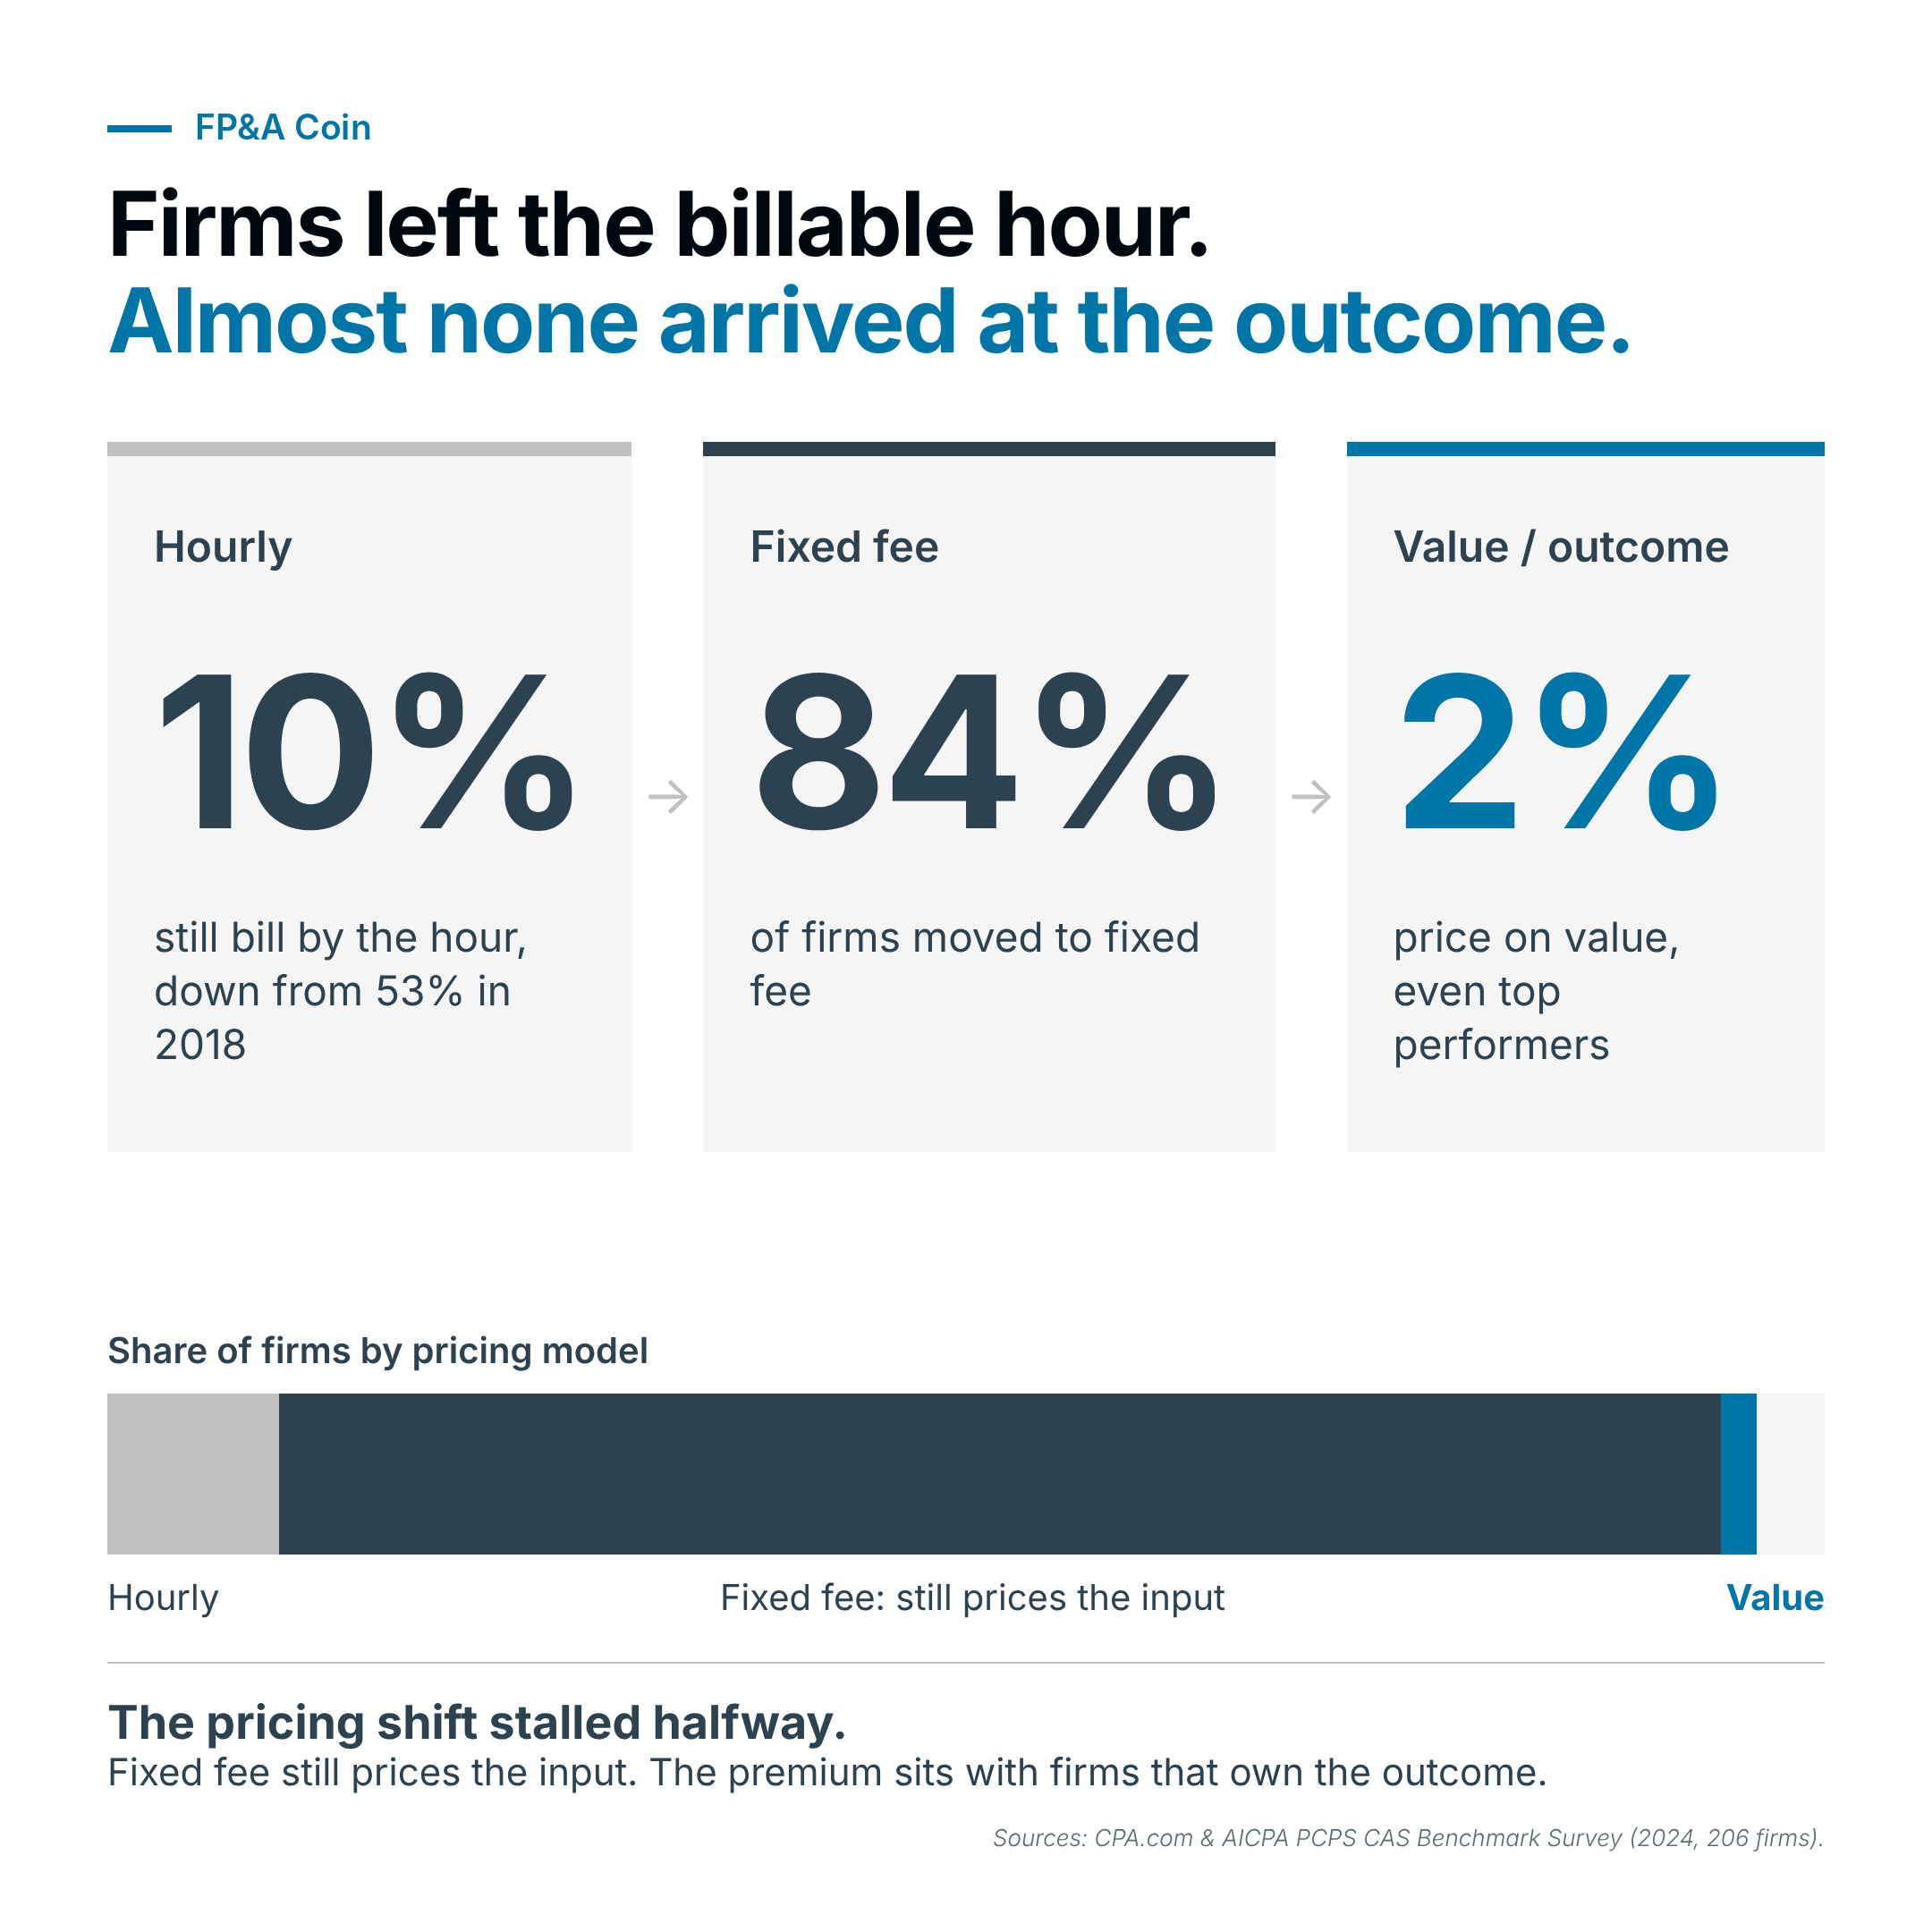
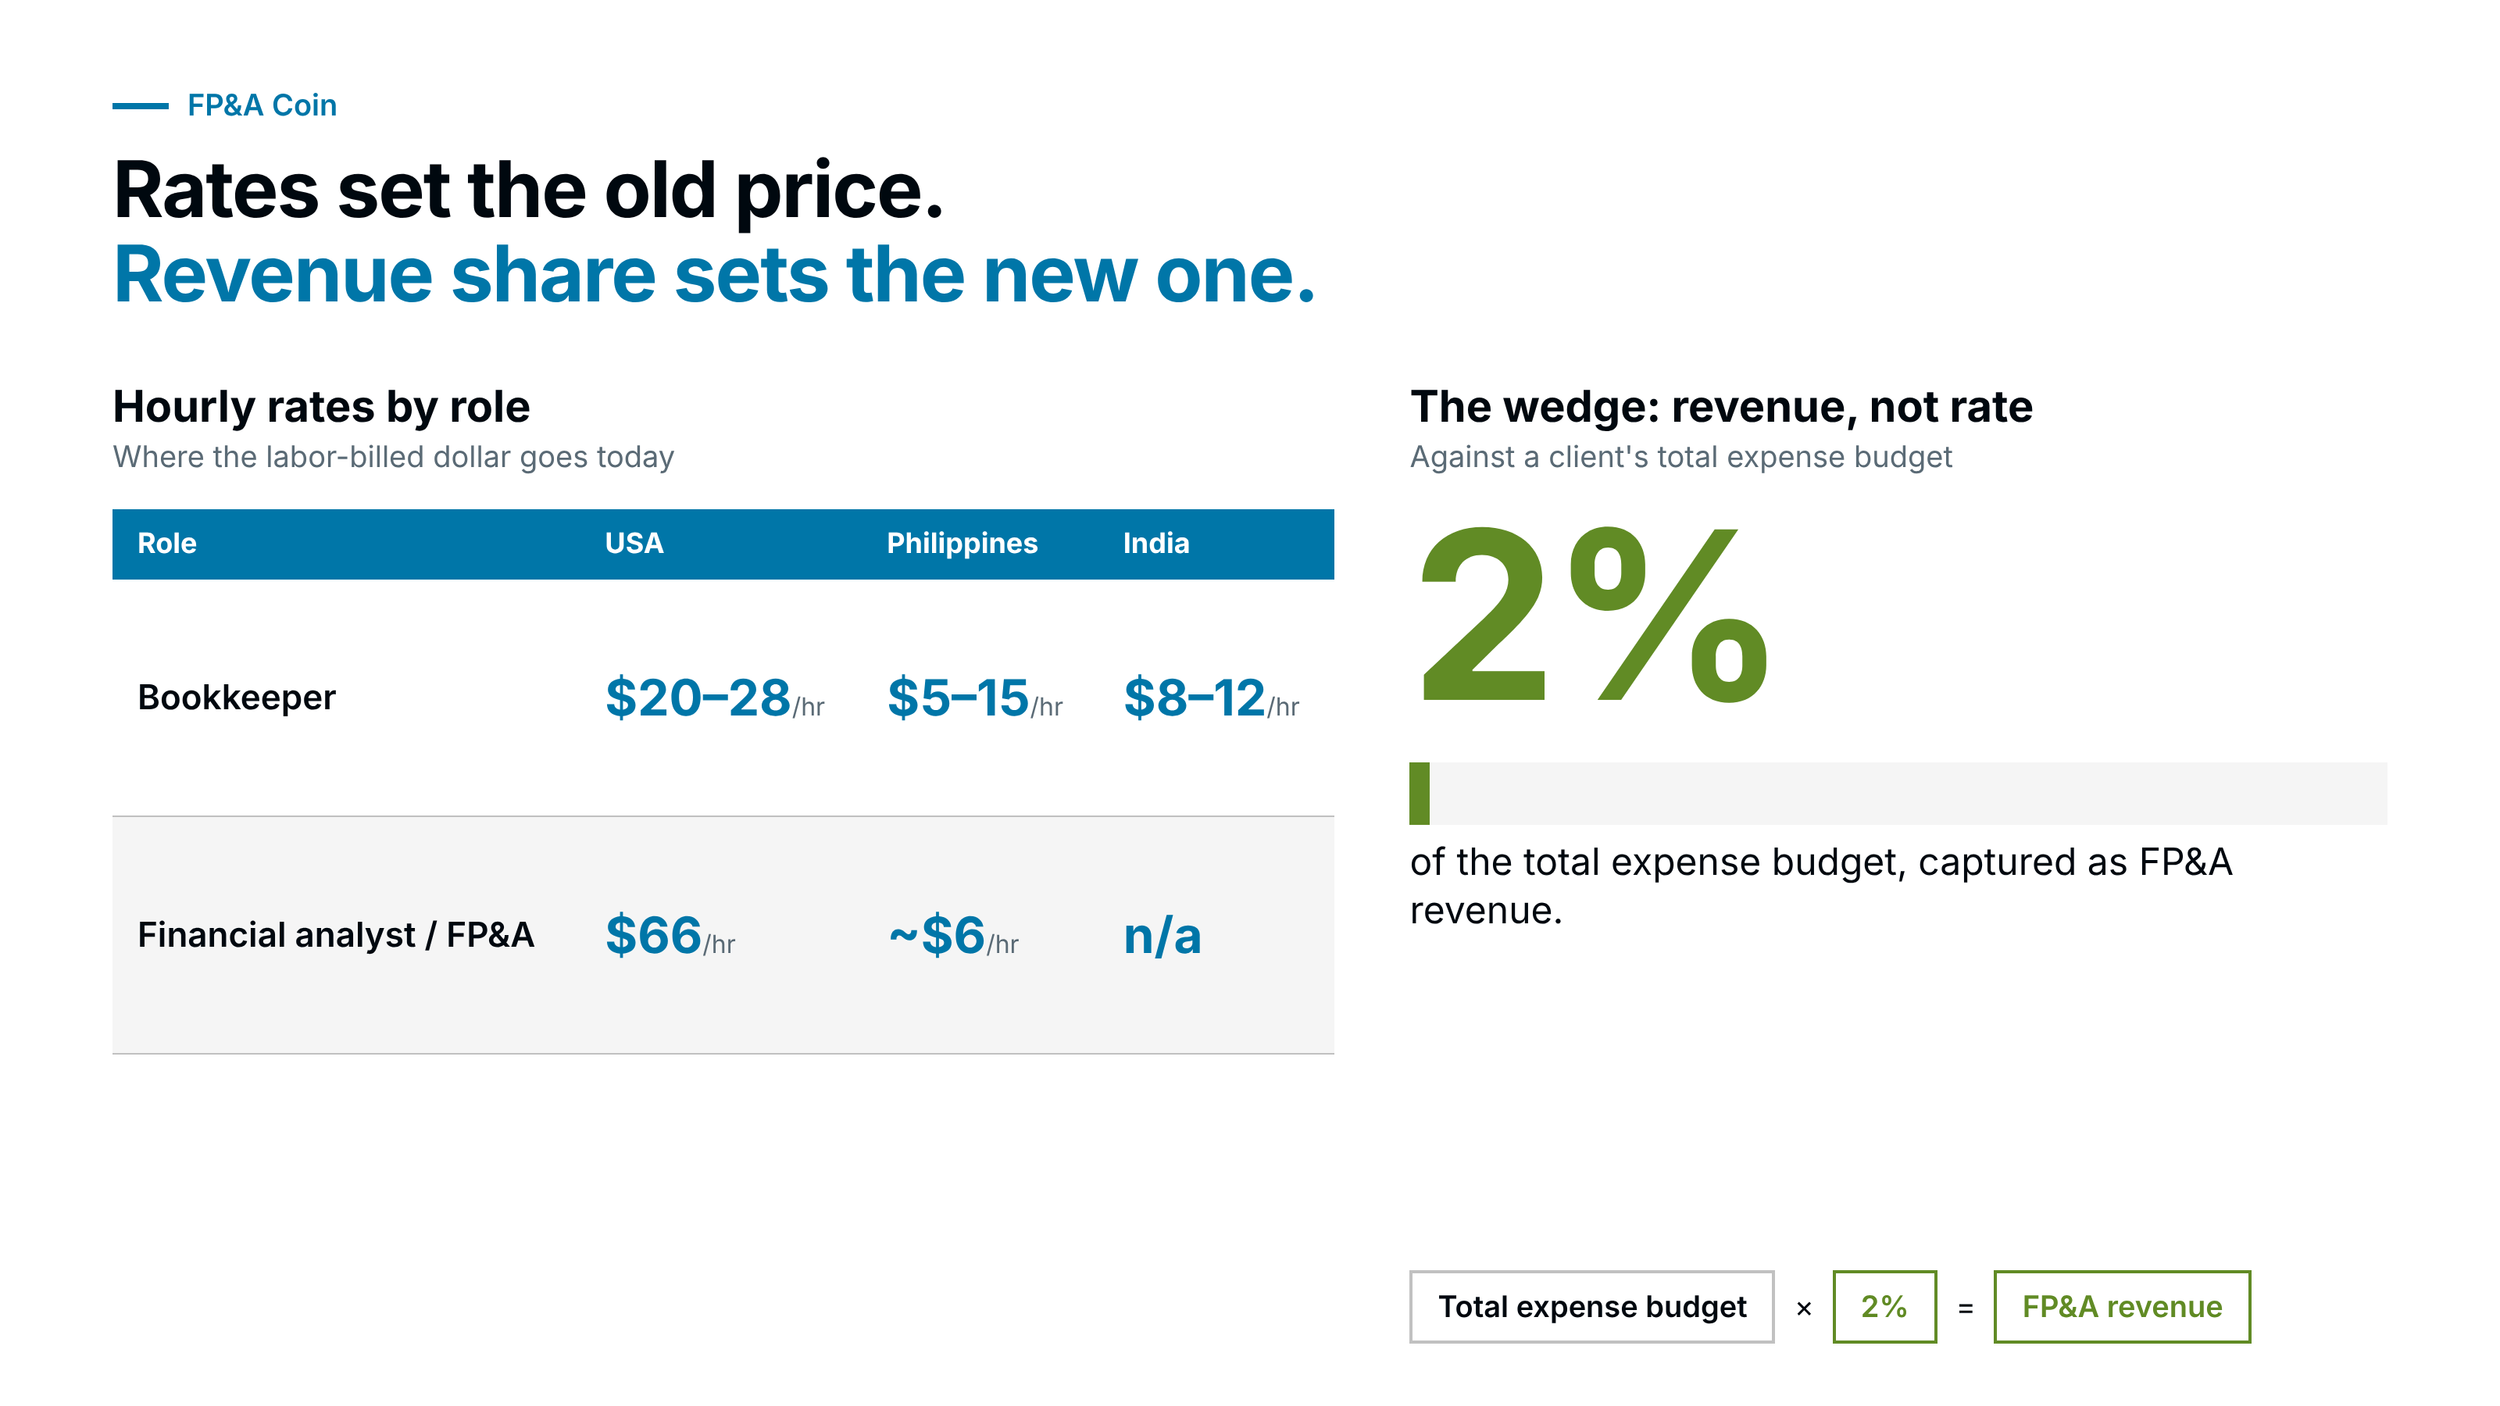
1. FP&A: billions spent on the software, only 2 premium exits Anaplan sold to Thoma Bravo for $10.4B. OneStream followed at $6.4B, at roughly half Anaplan's revenue multiple. Investors got paid for deploying capital into the software. The work underneath didn't change: 96% of FP&A teams still plan in spreadsheets, though 71% own a planning tool. Only 2% of firms price on value, not time.
2. ERP: the buyers want the implementers The most active ERP deal flow in 2026 isn't software vendors. It's implementation and managed-services partners, bought by serial consolidators at roughly 0.9x–2.7x revenue. Value-priced, AI-enabled delivery is what moves a partner above that range. Meanwhile, 10 AI-native challengers founded since 2021 are coming for the ledger itself.
3. The backoffice converges, and finance takes the center Ten backoffice functions that were ten separate vendors are becoming one unified solution.
The proof: 229 acquirers are buying across 3+ backoffice functions this year. The market prices which side you're on:
Workflow software 10x EV/revenue; effort-based services 1x
Above 120% NRR 9x; at ~100% ~3.1x; below 100% at <1x
FP&A, ERP and backoffice sponsors are paying for something else: firms that deliver the work on software they own.
For the Customer: Pay for the work to get done, not just the software
For the Industry: Build a solution that does the work, not another tool to manage it.
The common pattern: In all three markets, the premium no longer goes to software alone or to hours alone. It goes to the solution provider: a firm that delivers the work directly, on proprietary software it owns, and prices on the outcome. That's the open lane.
10 findings behind the pattern
Software alone failed. Well-funded software-only players raised ~$100M each - ScaleFactor, Bench and others names in my analyst briefing, and all three shut down. Software alone doesn't win.
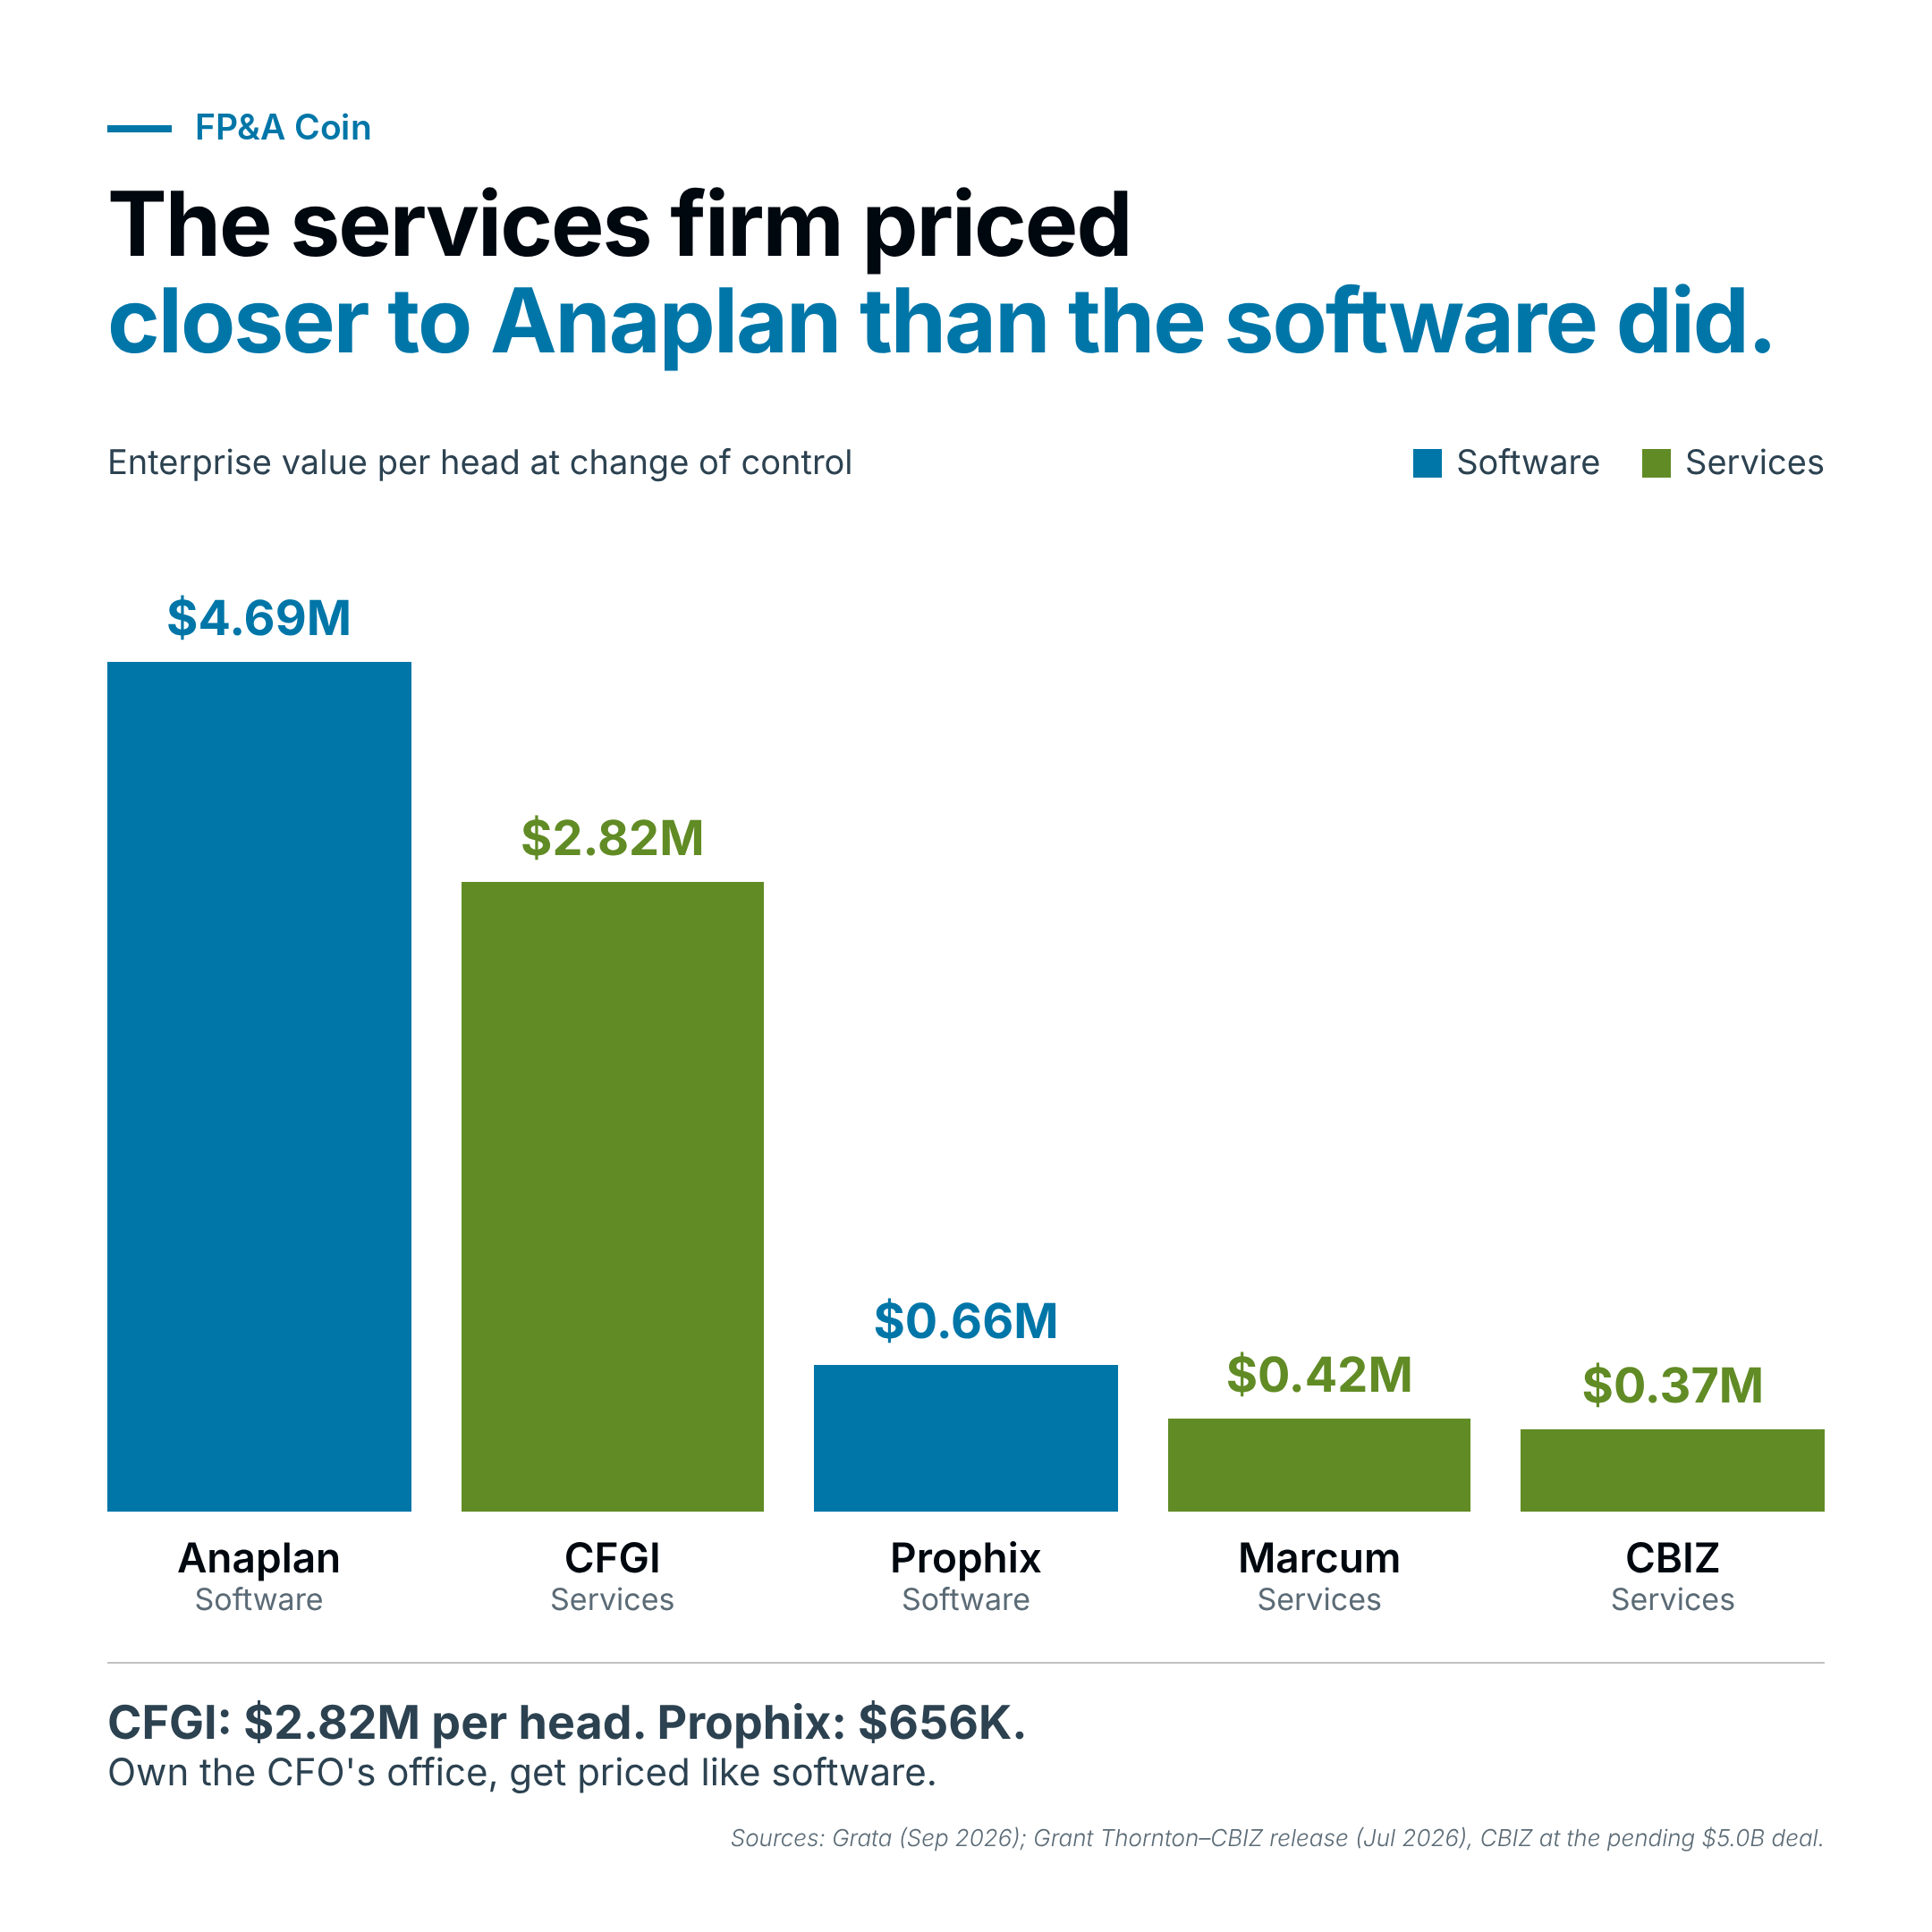
Services that own the CFO's office solution delivery get priced like software. CFGI sold to CVC at $1.85B, $2.82M per head, about 4x what planning-software Prophix got from Hg ($656K per head). Services that sell effort don't: CBIZ went to Grant Thornton at ~1.8x revenue, against ~10x for workflow software like OneStream.
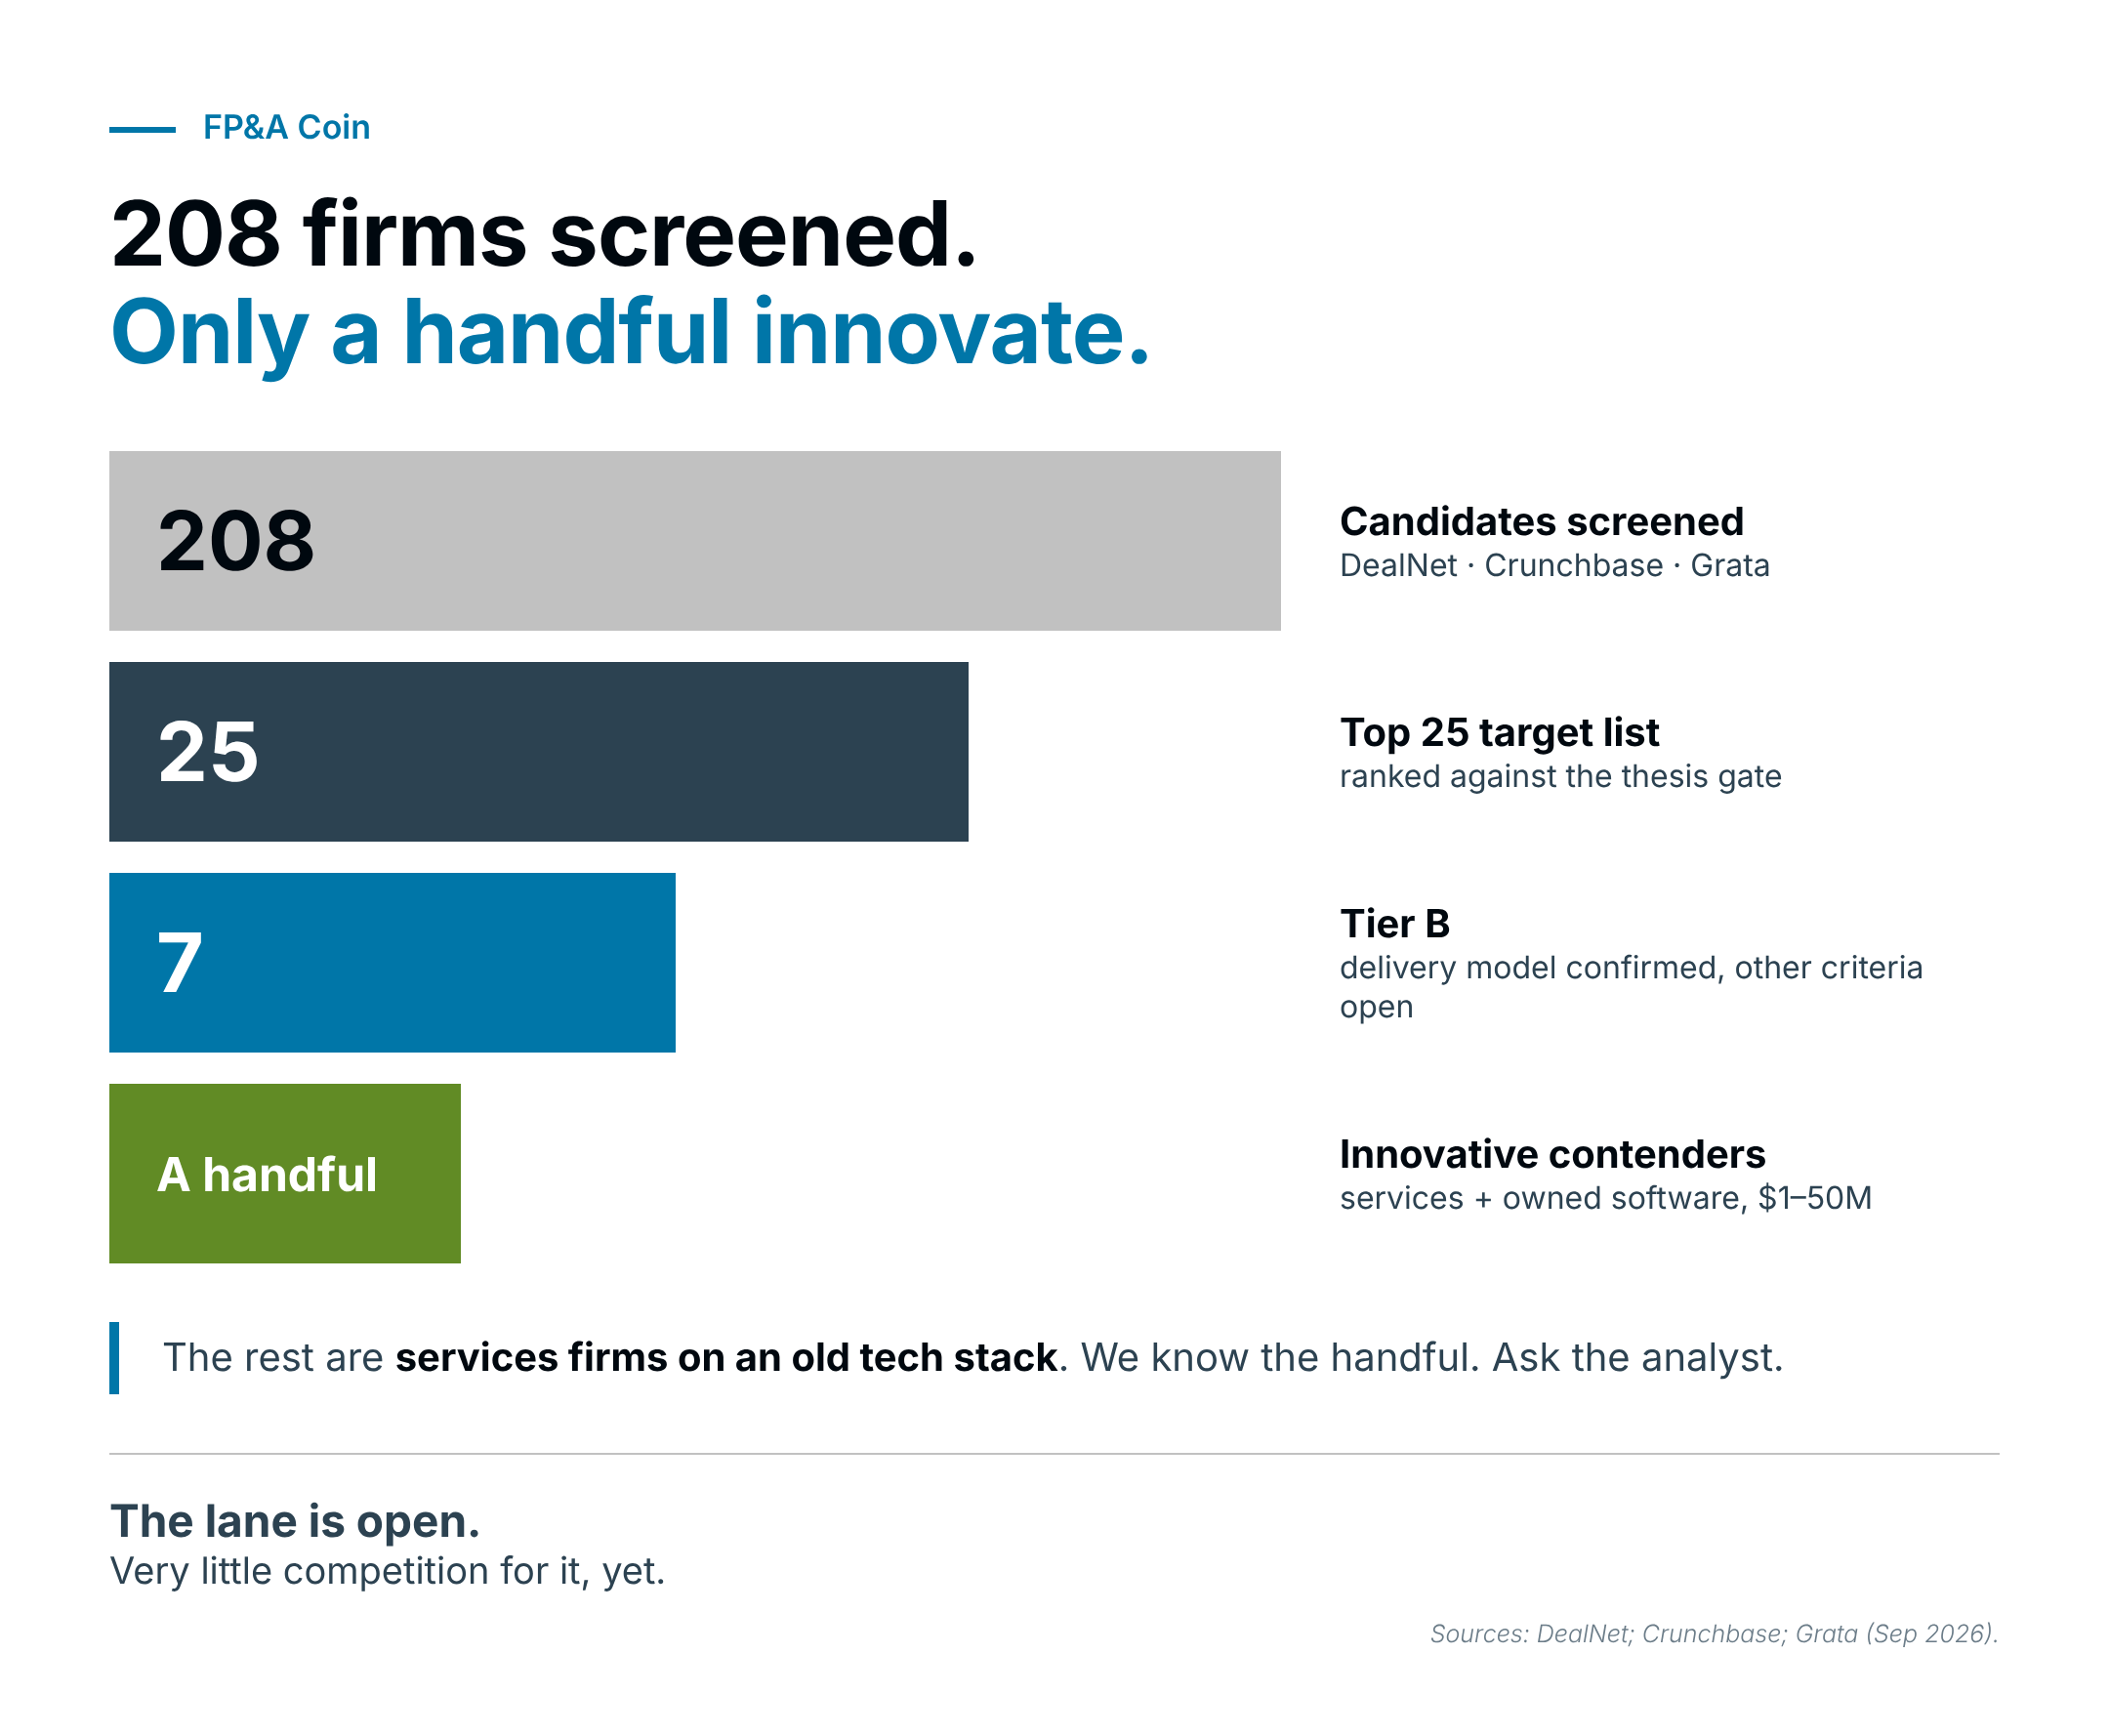
The open lane. I reviewed 208 firms YTD, and only a handful pair FP&A services with software they own.
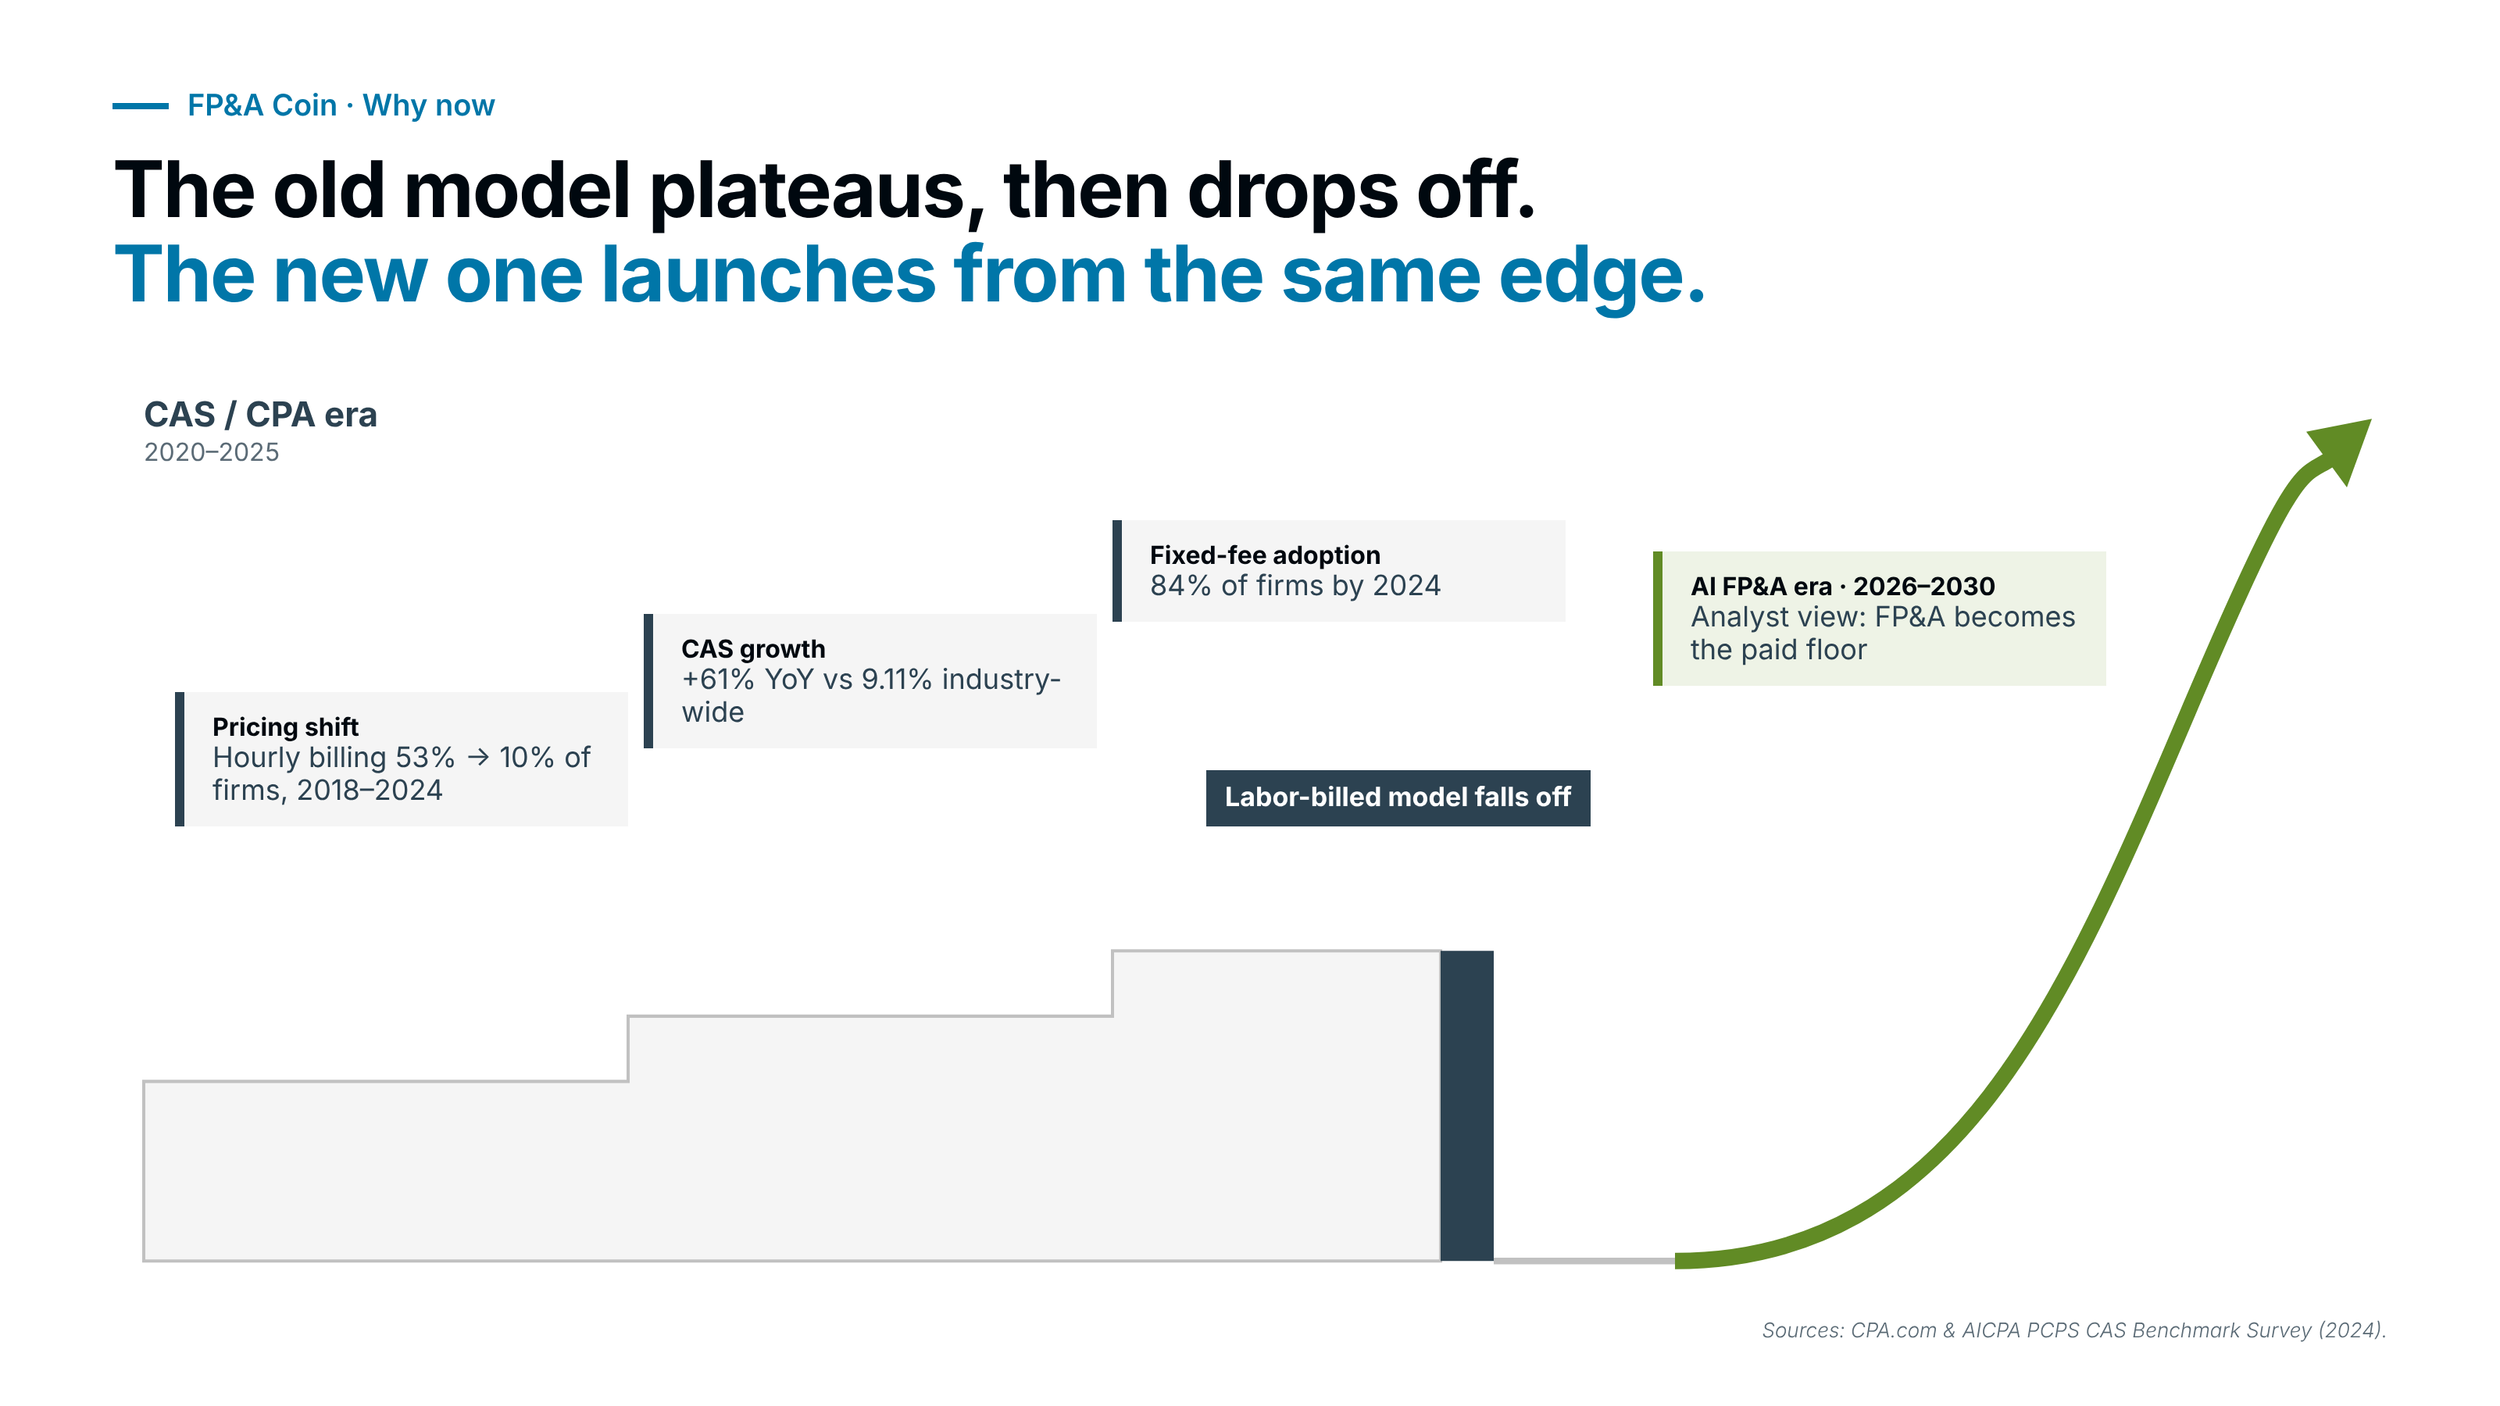
The pricing shift stalled halfway. Hourly billing fell from 53% to 10% of firms (2018 to 2024) and 84% now charge a fixed fee, but only 2% price on value. This explains why "outcome" is the next step.
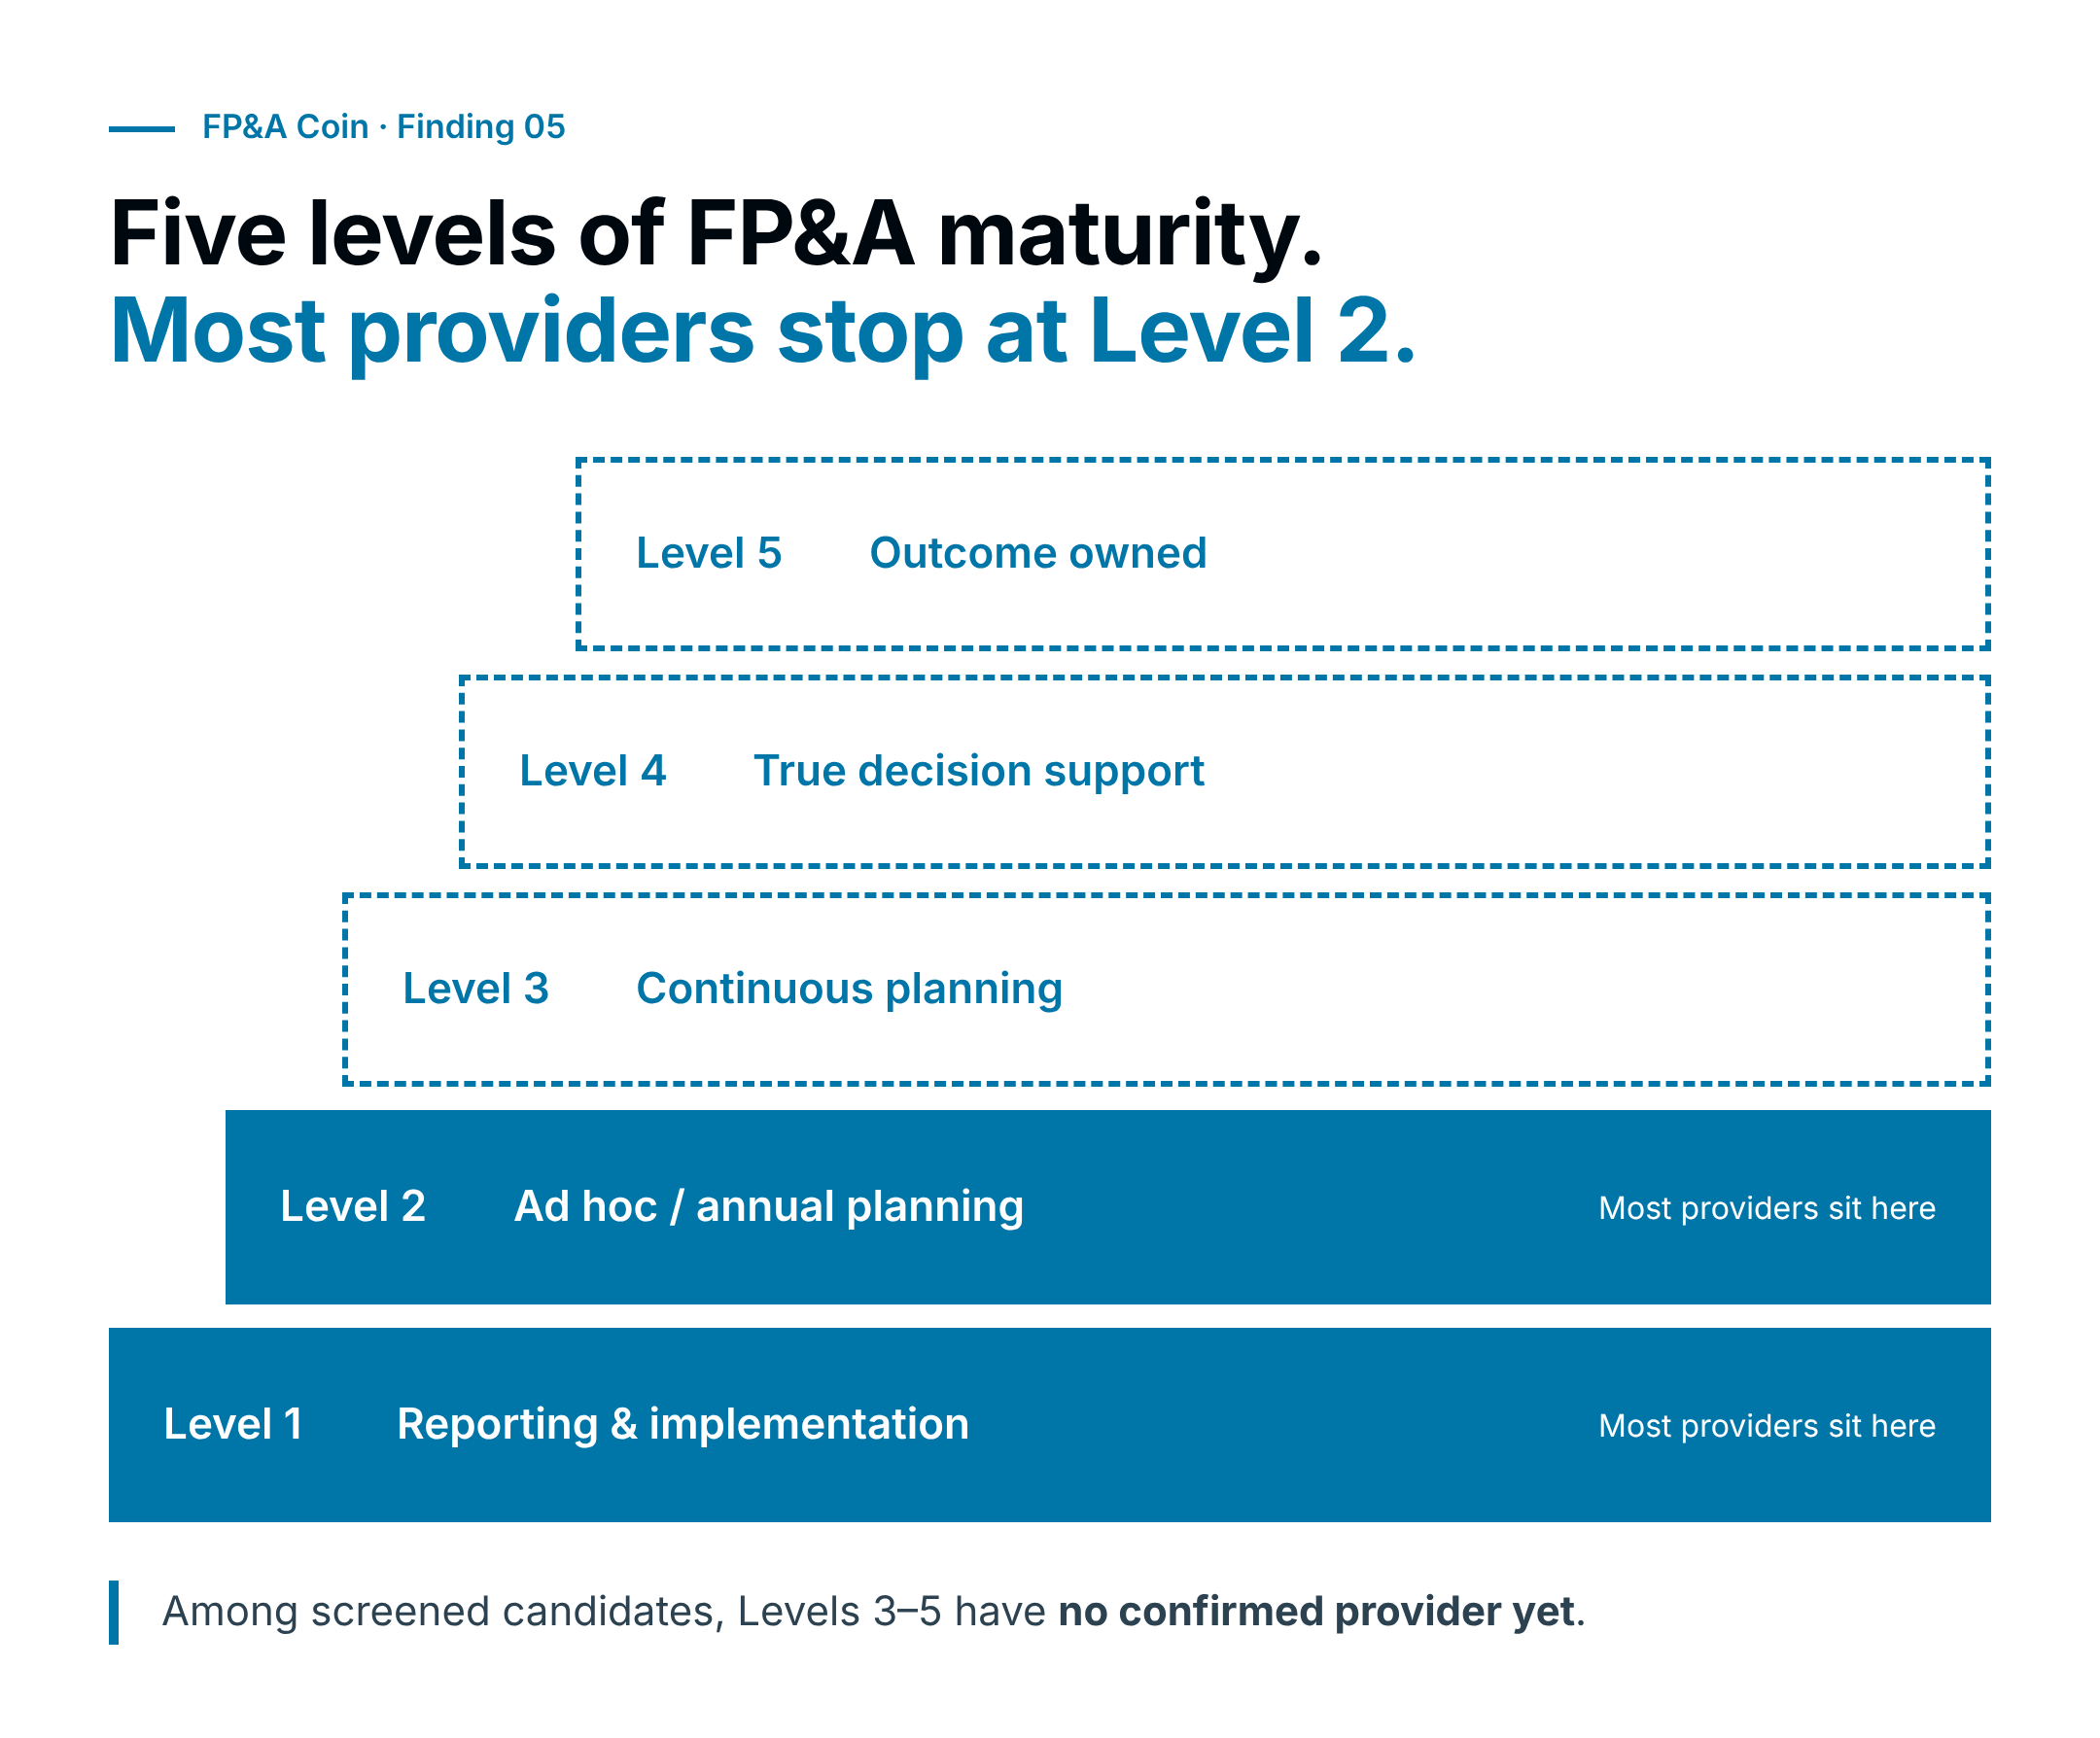
The maturity gap. Levels 3–5 (continuous planning, decision support, outcome-owned FP&A) have limited solution providers.
Most 2026 ERP deals bought implementers: ~30+ deals YTD.
Your ecosystem is your buyer. Six scale ecosystems (SAP, Microsoft, Sage, Oracle, Infor, NetSuite) hold most partners and most consolidators. SAP alone has 3,380+ listed partners.
The copilot vs. agent split. 6 of 10 incumbent ERPs now ship agentic finance AI. That's the "AI-enabled delivery" behind the move above 2.1x.
AI-native challengers are well funded: Rillet ~$208M, DualEntry $100M+, Campfire $100M+.
Labor is the line AI goes after. Labor costs 4x what technology does per $1 of revenue: ~25¢ against ~5¢. That gap is where the solution era gets paid.
If you deliver FP&A, ERP or Backoffice professional or outsourcing services:
Do you sell hours, or outcomes?
Do you own the IP, data, workflows, and software your delivery runs on?
FP&A, ERP, Backoffice Industry Briefing Preview @