
300+ services firms sell the same software. What they add to it sets the price.
Our NetSuite partner map counts more than 300 services firms working on the same software. So what sets one apart? Swipe the 8 slides below.
Two firms, two answers
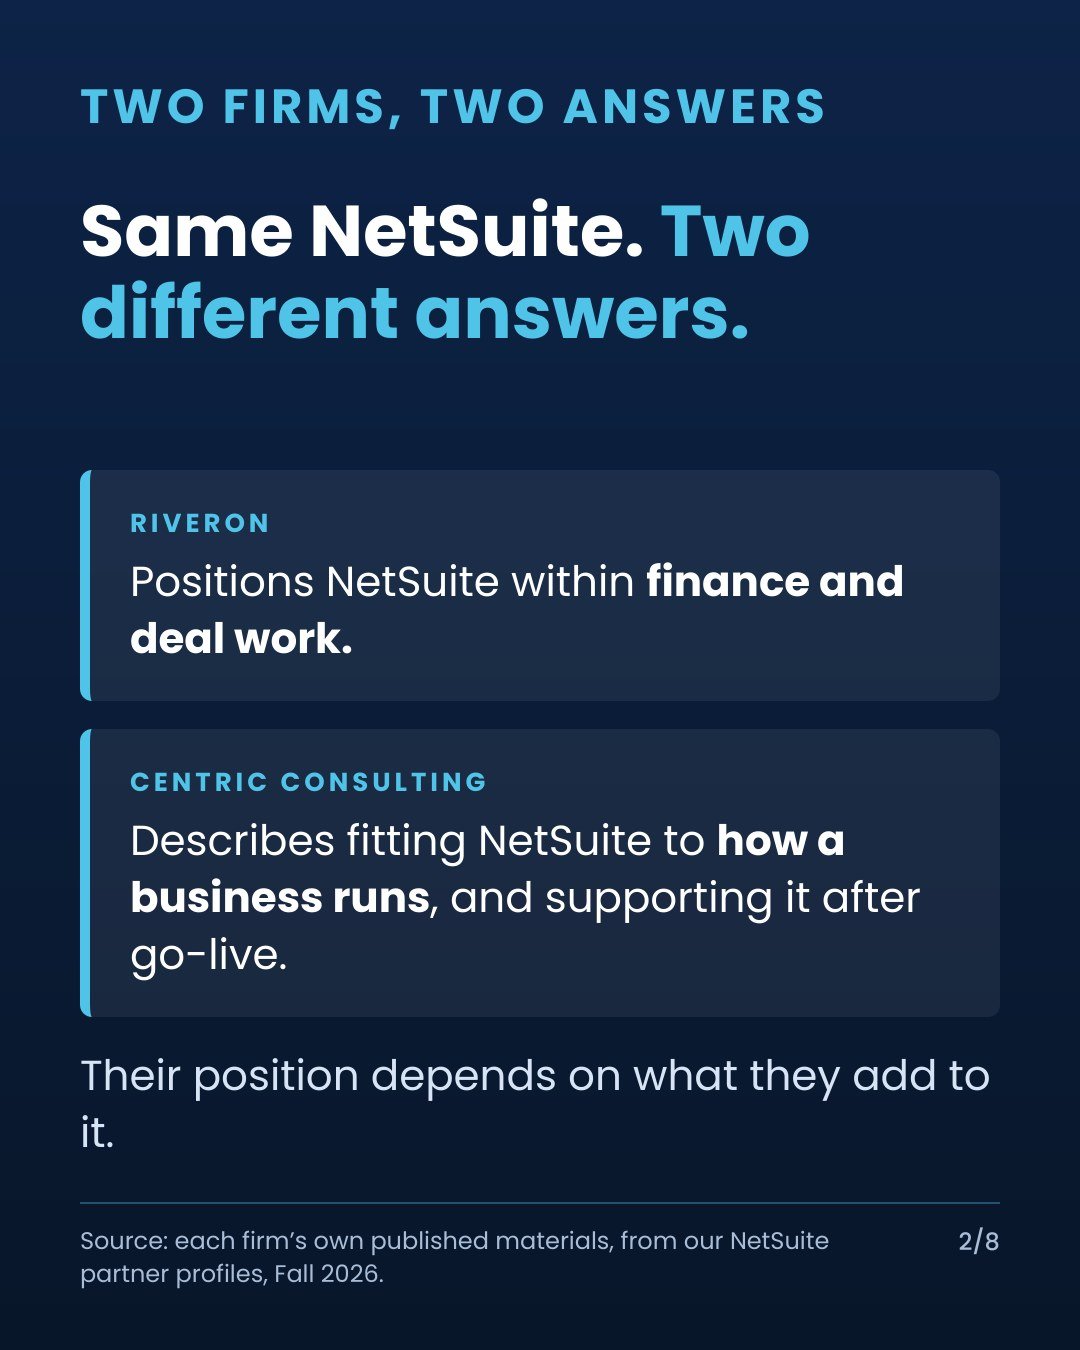
Riveron positions NetSuite within finance and deal work. Centric Consulting describes fitting NetSuite to how a business runs, and supporting it after go-live. Same NetSuite, two different answers: a partner's position depends on what it adds.
Who owns them
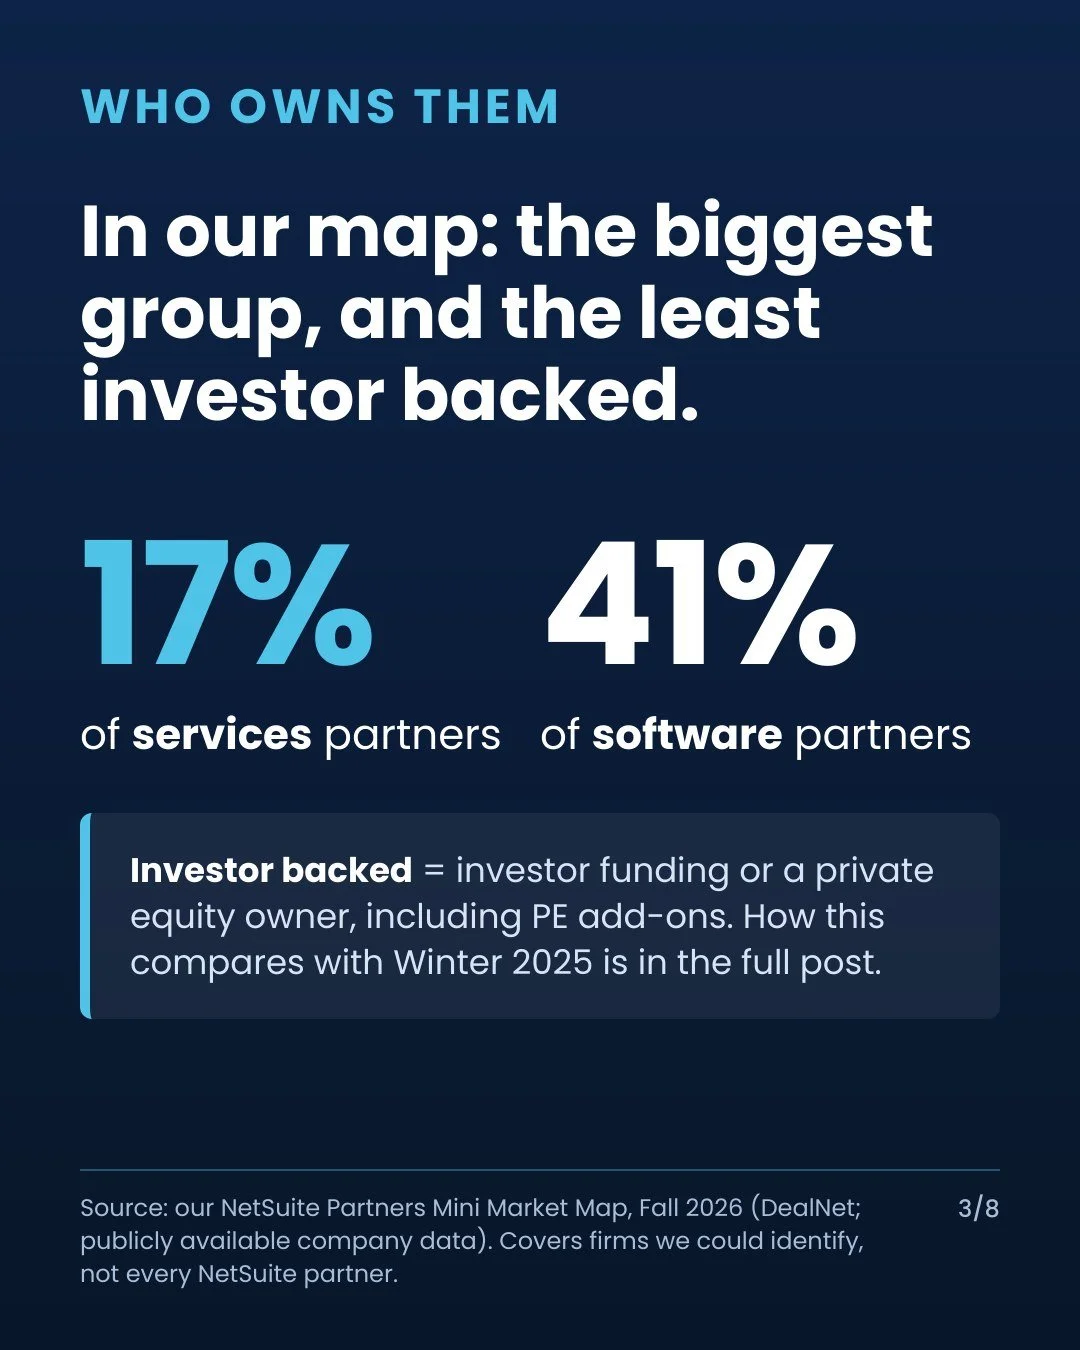
17% of services partners in our map are investor backed, against 41% of software partners. Services partners are the biggest group and the least investor backed.
A rare mix
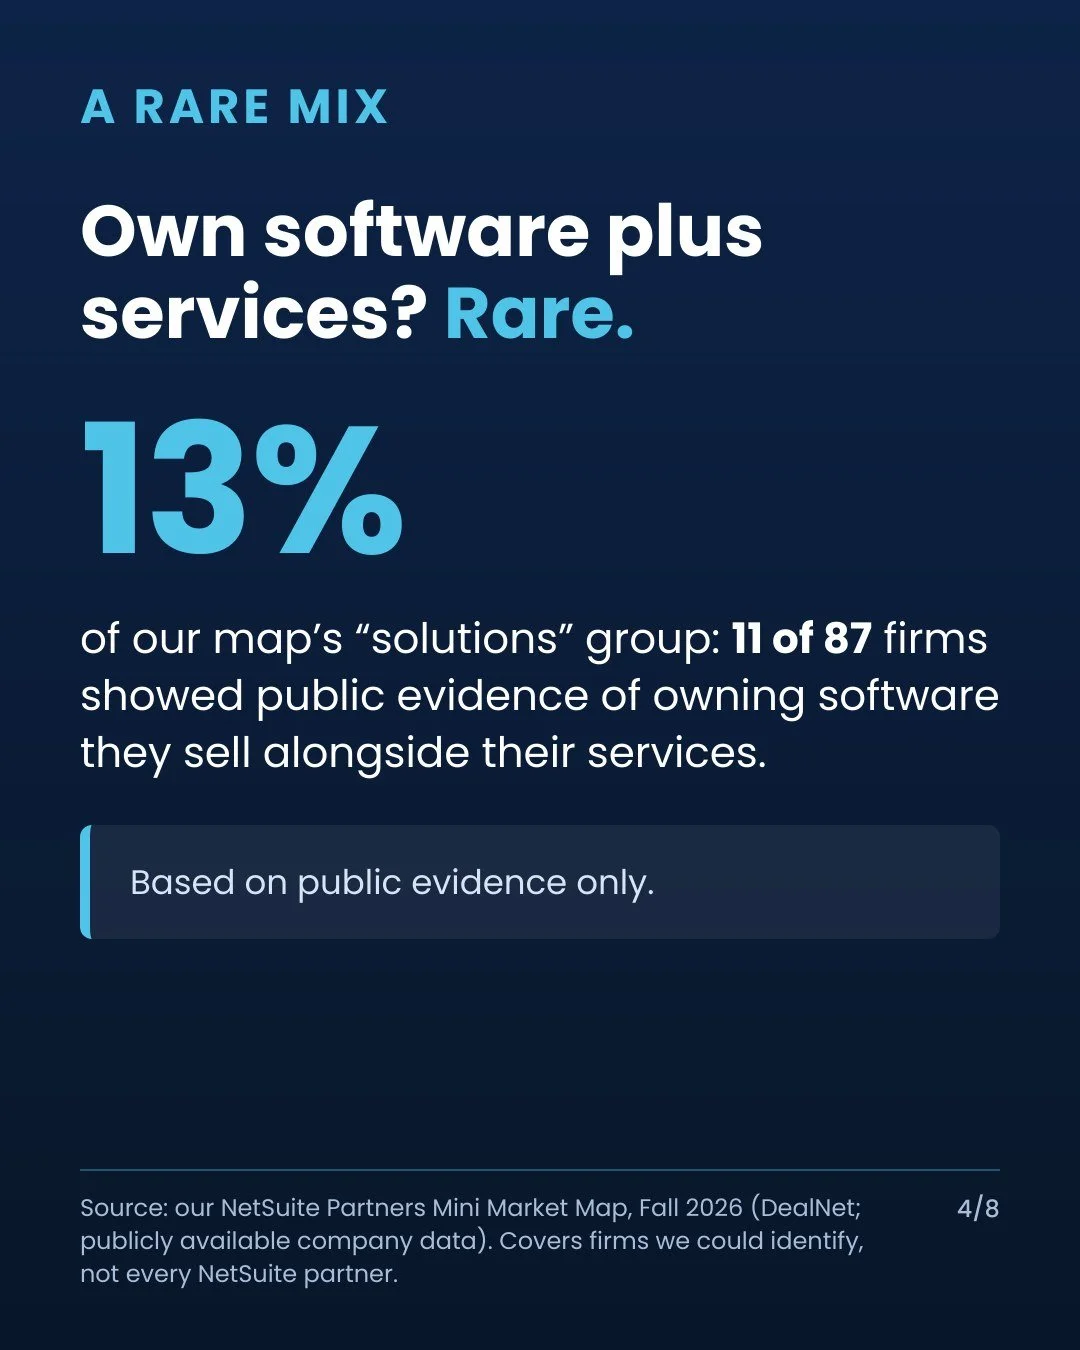
13% of our map's solutions group, 11 of 87 firms, showed public evidence of owning software they sell alongside their services.
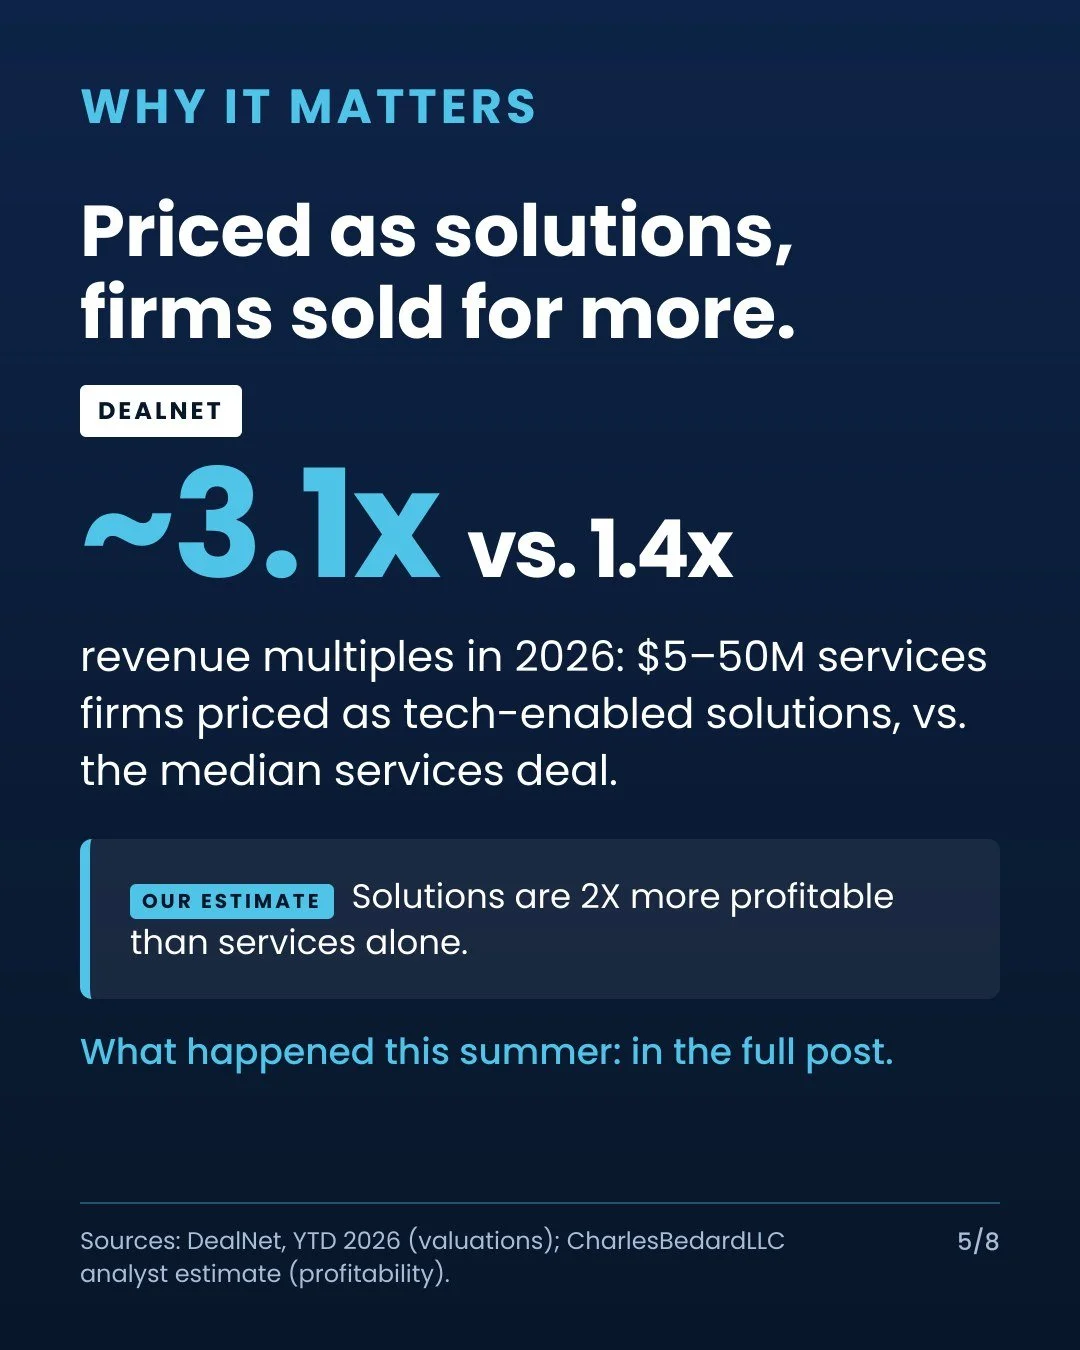
Why it matters
~3.1x vs 1.4x. In 2026, $5M–$50M services firms priced as tech-enabled solutions sold for about 3.1x revenue, against 1.4x for the median services deal. Our estimate: solutions are 2X more profitable than services alone.
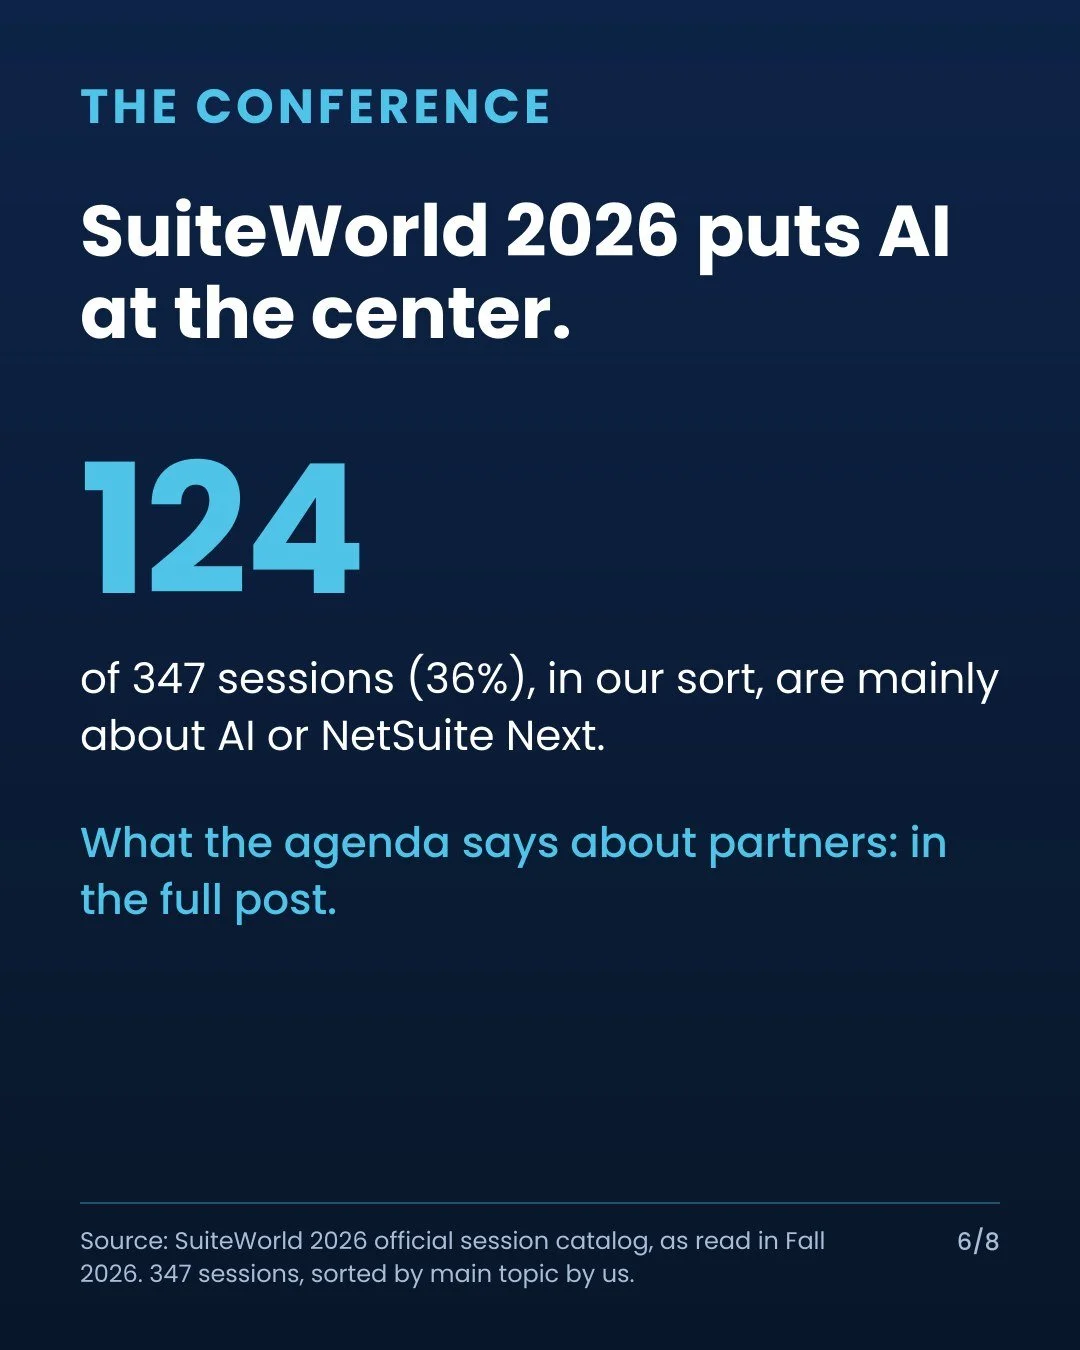
SuiteWorld put AI at the center
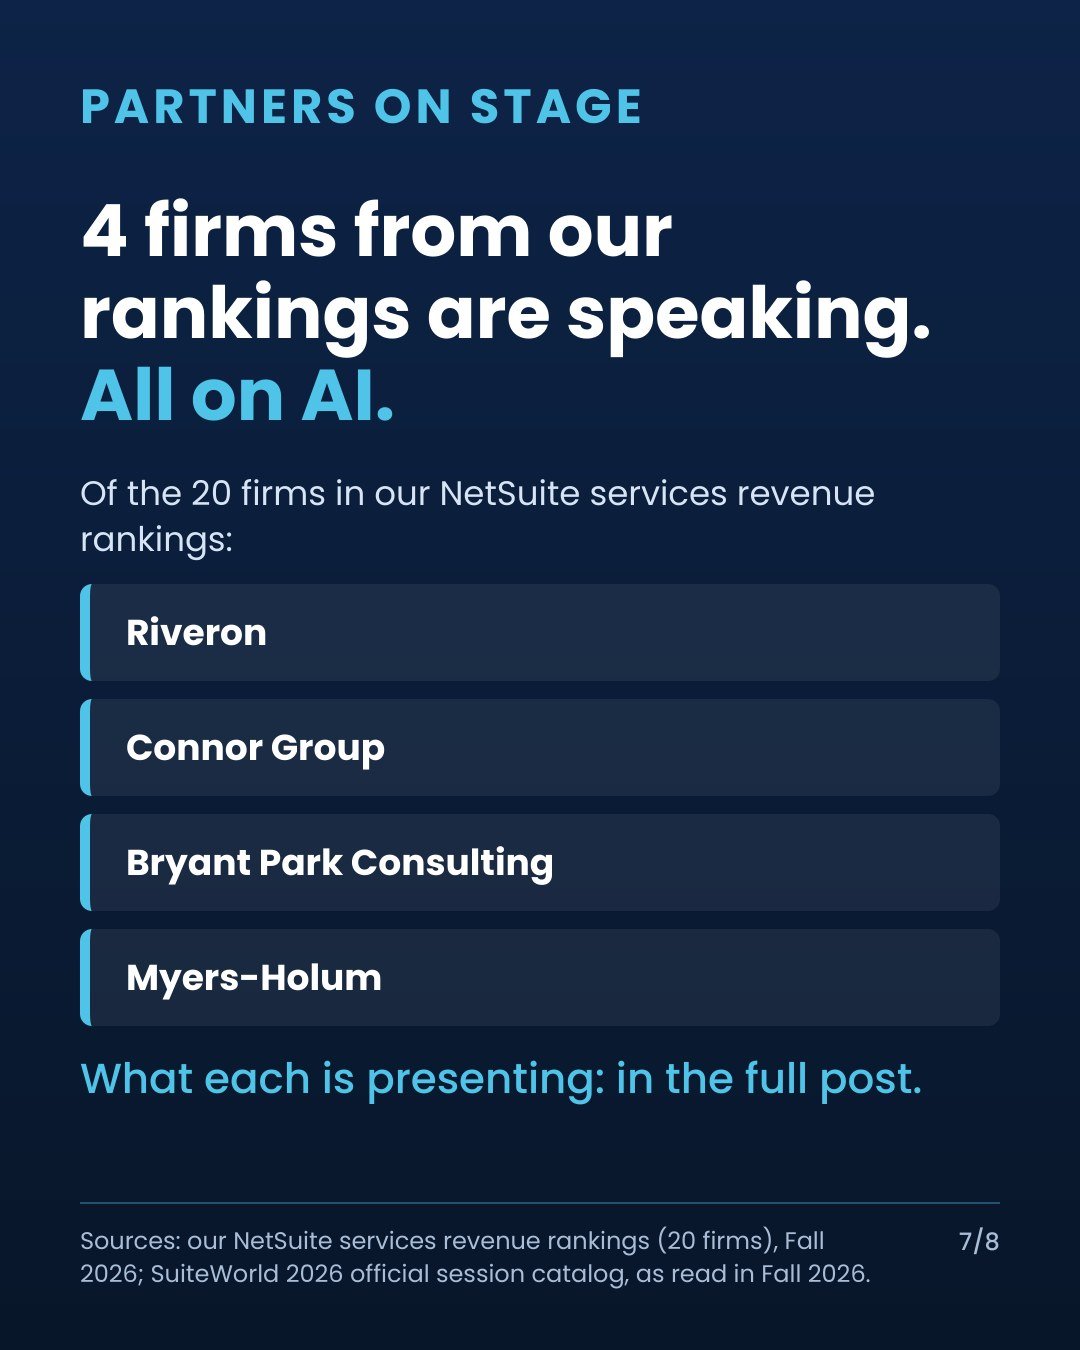
124 of 347 SuiteWorld 2026 sessions (36%), in our sort, were mainly about AI or NetSuite Next. Four firms from our NetSuite services revenue rankings spoke, all on AI: Riveron, Connor Group, Bryant Park Consulting and Myers-Holum.
Our read
Beyond implementation, what do you add? For a NetSuite partner with $1M–$50M in revenue, owning software or a solution on top of the services is what moves the multiple.
Want to see where your firm stands against other NetSuite partners? Request your analyst briefing:
charlesbedardllc.com/contact-us
Sources: NetSuite Partners Mini Market Map, Fall 2026 (DealNet; publicly available company data; covers firms we could identify, not every NetSuite partner); DealNet YTD 2026 valuations; SuiteWorld 2026 official session catalog, 347 sessions sorted by main topic.
