The Solution Premium — Q3 Analyst Coverage Recap
Three market corrections are reshaping Work Tech M&A across the Backoffice to Frontoffice — the evidence, and what to do about it.
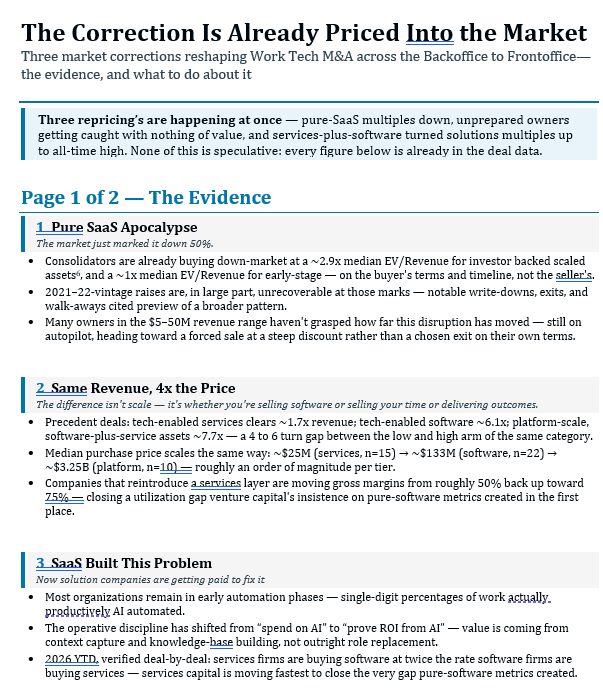
Three repricings are happening at once: (1) pure-SaaS multiples down, (2) unprepared owners getting caught with nothing of value, and (3) services-plus-software turned solutions multiples up to all-time highs. None of this is speculative — every figure below is already in the deal data.
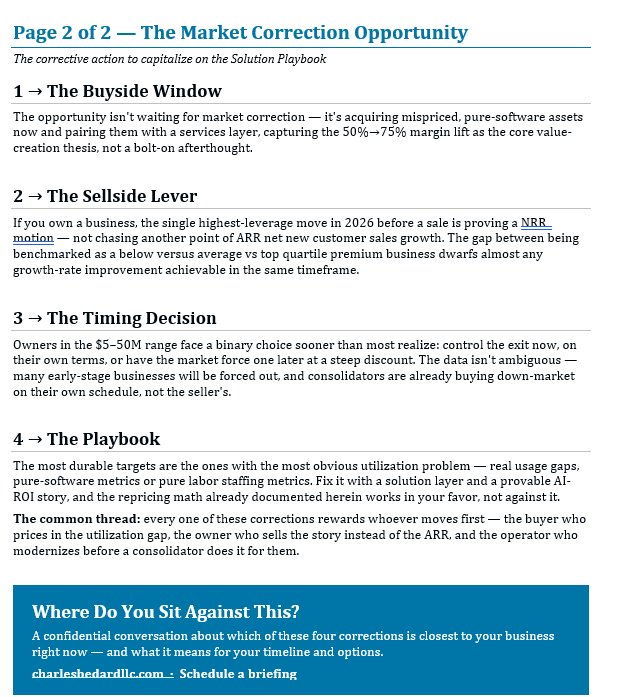
The most durable targets are the ones with the most obvious utilization problem — real usage gaps, pure-software metrics, or pure labor staffing metrics. Fix it with a solution layer and a provable AI-ROI story, and the repricing math already documented here works in your favor, not against it.
The Solution Premium Playbook: buy the fragmented service, attach the software and AI layer, exit a re-rated solution business model — and do it from both directions at once. Services firms are buying software to escape commoditized delivery; software firms are buying services to escape the utilization gap pure-SaaS metrics created. What used to be two separate playbooks is now one unified better business model.
1 — Market Dynamics
Two forces are converging on the same trade from opposite directions. On one side, a new generation of private equity buyers — 25 identifiable "fourth-generation" firms with $150M+ to deploy per portfolio, having already put over $1 billion to work rolling up service partners (Workday, ServiceNow, Sage, NetSuite, UKG, DayForce, and Paylocity's own partner network among them) — is acquiring services businesses and attaching software. On the other, software companies that spent the last cycle chasing pure-SaaS metrics are buying back the services layer they stripped out, pivoting from vertical-SaaS positioning toward mission-critical or solutions-oriented offerings. The convergence is not a prediction — it is already showing up in gross margins: companies that reintroduce a services layer are moving from roughly 50% back up toward 75%, closing a utilization gap that venture capital's insistence on pure-software metrics created in the first place.
This quarter's analyst coverage:
Playbook — The 5 Winning M&A Playbooks for Corporate Development Buy-and-Build Strategies July 2026
Briefing — The Solution Premium Playbook: Why Software + Services Is Converging Now, and The Correction Is Already Priced In Sep 2026
Catalog — Fall eNewsletter Catalog Preview of my Analyst Quarterly Coverage: The Winning Playbook for the AI Era Corporate Development Sep 2026
Market Map Rankings — The Catalog of Market Map Rankings Across 50 Product Categories for Work Tech, Backoffice to Frontoffice Oct 2026
Full coverage archive and ongoing analysis:
LinkedIn Newsletter