
Retention, not the hire, is the outcome buyers pay for
Findings from the HR Technology Conference, Las Vegas, October 20–22, 2026, read against 3,280 Work Tech deals and 2,687 market signals tracked this year. AI wins when it sells that outcome. Workflow alone is now table stakes, and standalone modules (ATS, compliance, onboarding, succession planning) get absorbed into platform suites.
Analyst take: the firms winning in Work Tech sell measurable business outcomes beyond the point vendor and the systems customers use every day, not only workflow administration and insights.
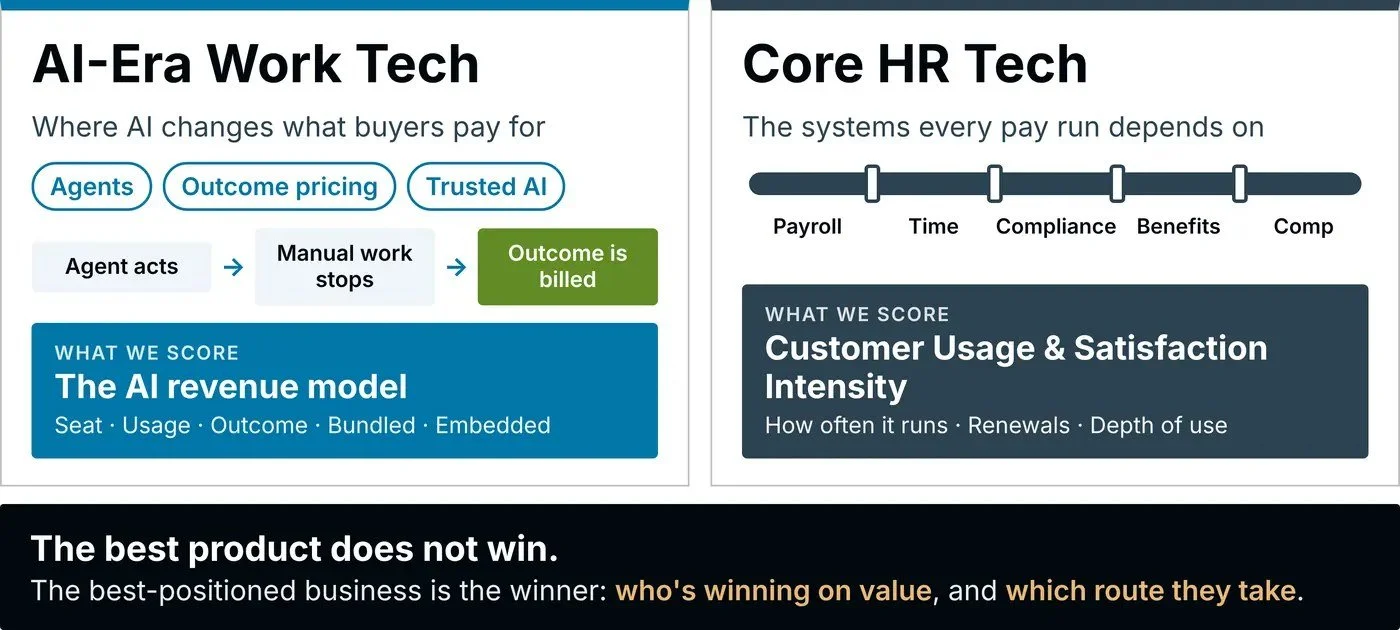
The Headlines vs. the Volume: What 2,687 Signals Say About Work Tech M&A
AI is the one clean long-term shift in Work Tech M&A. Everything else is steady or cyclical.
The headlines belong to billion-dollar publics; the deal volume belongs to owner-operators. For a founder running a private, early or growth stage business, the read is simple. Buyers are paying for capabilities that compound inside a platform: AI delivery, AI revenues, governance and capacity top the list.
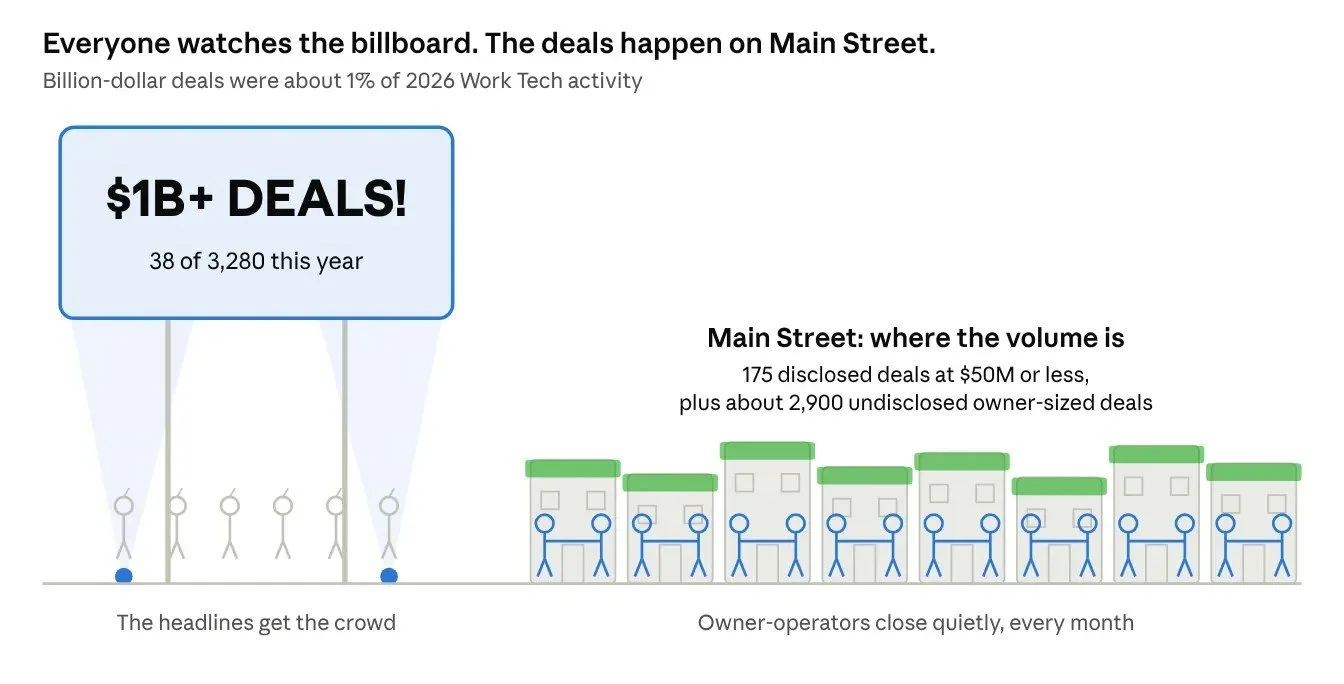
Illustration · DealNet 2026 deal counts, Jan 1–Oct 19
The C-suite moves before the deal
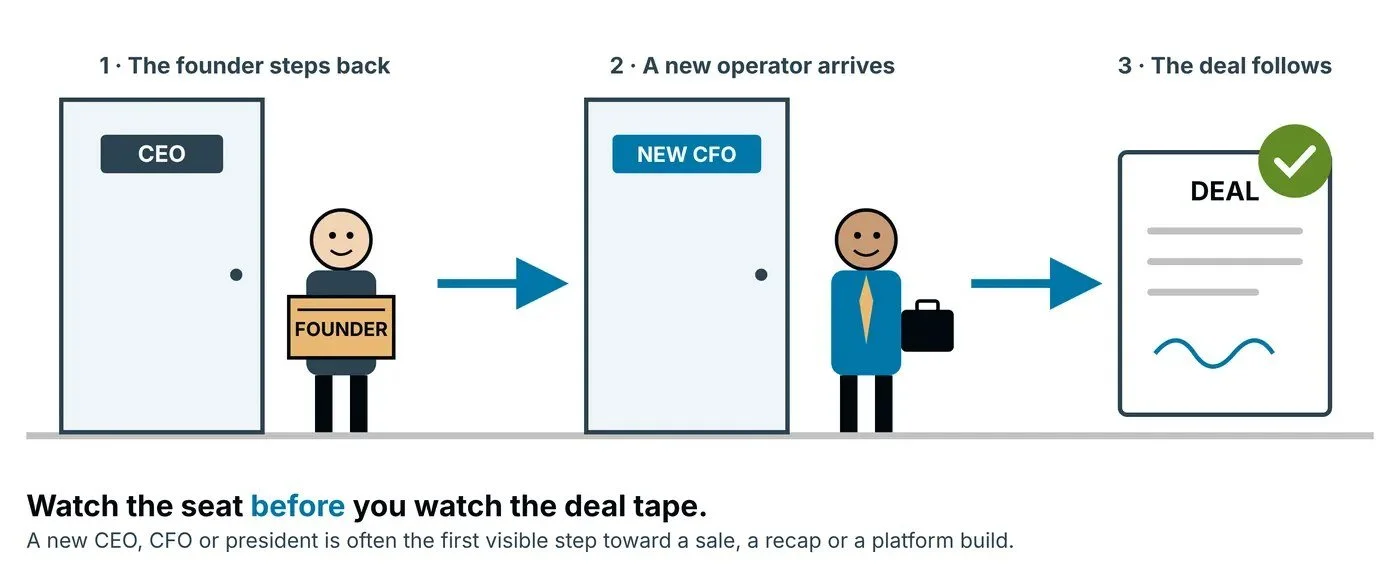
Leadership change is the loudest signal in the market: 961 of 2,687 signals this year (36%) were executive moves, more than M&A, funding and product launches combined.
They run at a steady 80–120 a month while deal flow swings. A new President, CFO, CRO, CTO or Partner is often the first visible step toward a sale, a recap or a platform build. Watch that seat before you watch the deal tape.
Summer stall, fall rebound
After a steady first half, deal activity stalled in July and August, then snapped back in September as M&A signals tripled.
DealNet · 2026 deals and M&A signals by month, Jan 1–Oct 19
Where the money is going
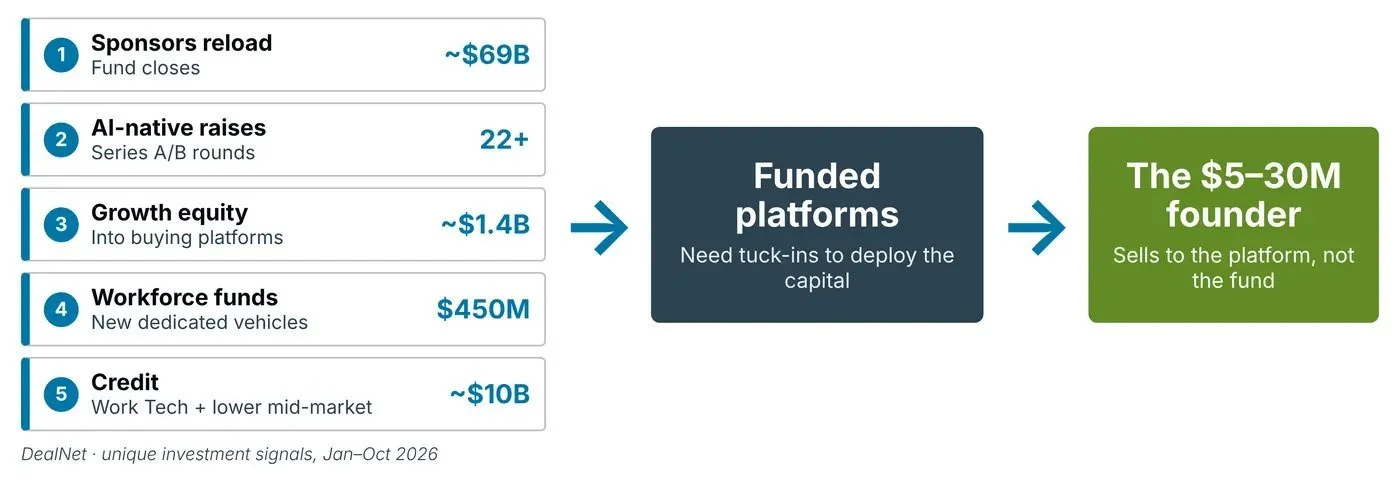
Fund closes, AI-native raises, growth equity and credit all point the same way: capital reaches owner-operators through funded platforms that need tuck-ins. The themes, verticals and buyer mix below show where those platforms are buying.
Top 5 investment trends
The capital is there, and it reaches owner-operators through funded platforms that need tuck-ins, not directly from the funds.
| # | Trend | Evidence |
|---|---|---|
| 1 | Sponsors reload: fund closes stack up¹ | EQT $15.6B, Bain $10.5B, TPG $10B, Bessemer $5.75B, PSG $5.1B, Spectrum $2.5B, STG $1.3B (oversubscribed). Gen 4 PE sponsors focused on AI value creation. |
| 2 | AI-native Work Tech raises at Series A/B, not late stage² | Juicebox $80M B at $850M post, Ema $77M B, Metaview $60M C, Flex $70M B, Warp $60M B, LearnUpon $50M, Miter $40M B |
| 3 | Growth equity funds the platforms that buy owner-operators³ | HR Path near-$1B led by Ardian, then 6+ tuck-ins (latest SnapAI); Symplr $175M; Five Arrows + Vista into StarRez |
| 4 | Workforce-specific funds appear | Achieve Partners closed a $450M Workforce Fund II aimed at AI-driven labor disruption |
| 5 | Credit fills the gap⁴ | VensureHR $450M debt, DailyPay $195M, HiBob $160M, Earnin $150M; BDC lenders (Hercules, Capital Southwest, Main Street) raised $200–595M each |
¹ 24 fund-close signals, about $69B. ² 22+ venture and growth round signals. ³ 4 PE growth or minority signals, about $1.4B. ⁴ 21 debt signals, about $60B, of which $50B is two mega-cap issuers; about $10B is Work Tech and lower-middle-market credit. Counts are unique investment signals, Jan–Oct 2026. Source: DealNet.
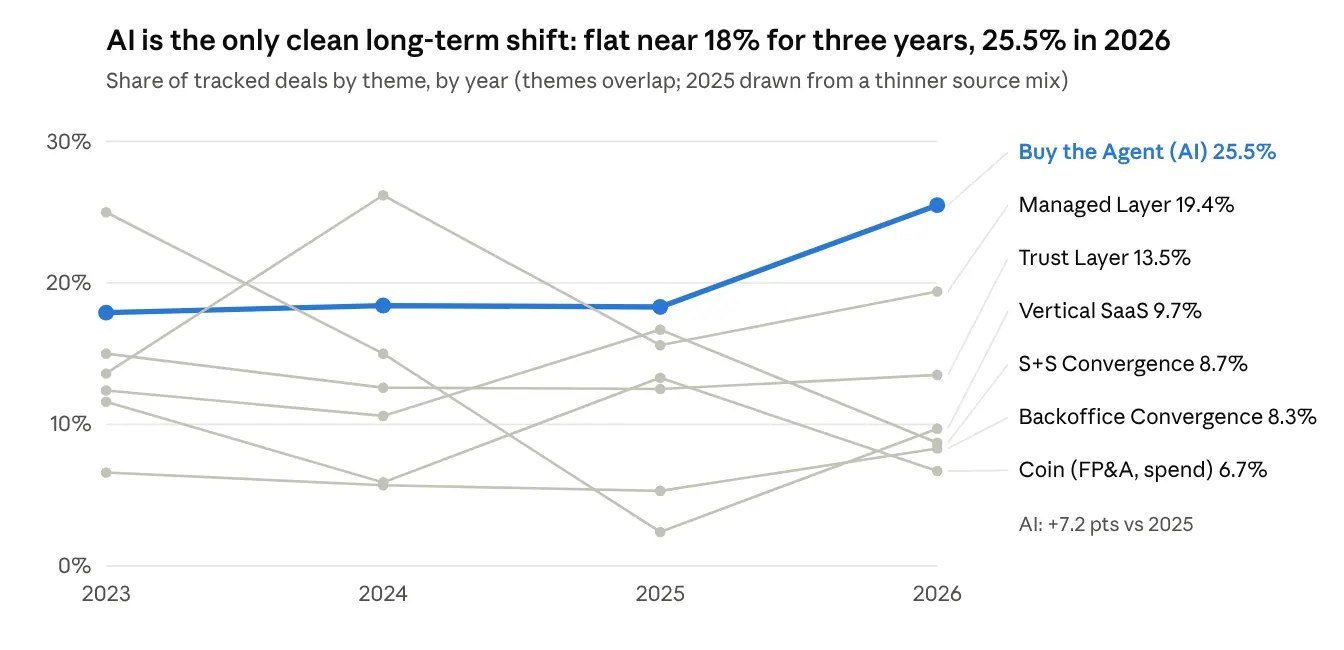
Seven M&A themes
AI is the structural shift; the rest are durable markets where buyers keep consolidating.
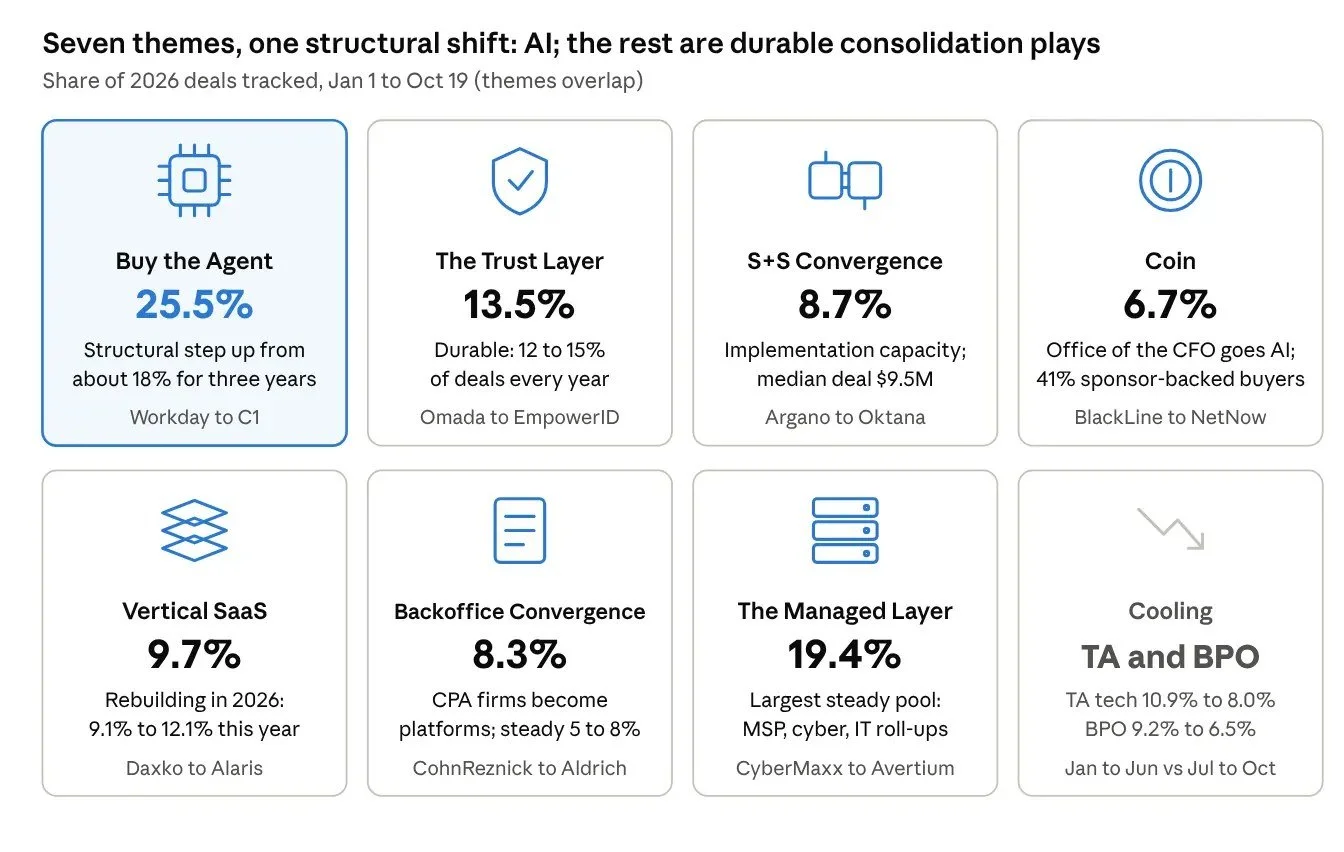
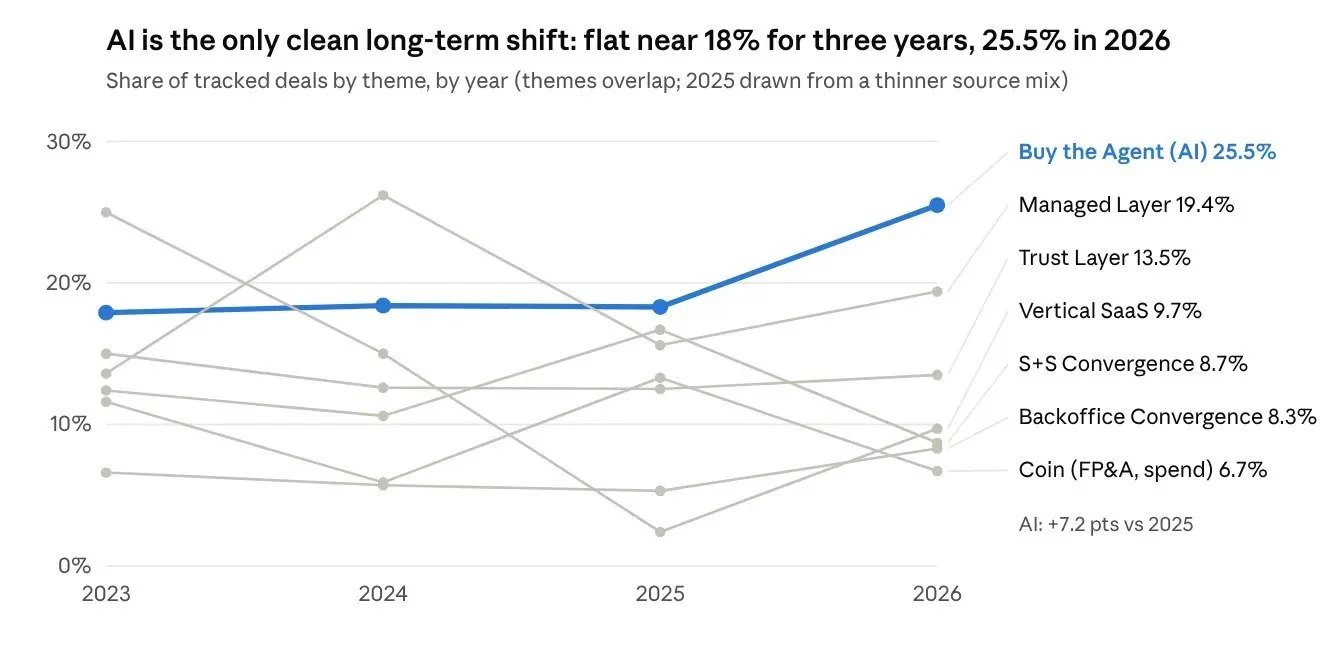
DealNet · share of tracked deals by theme, 2023–2026 YTD (Oct 19). Deal counts, 2026: Buy the Agent 832, Managed Layer about 640, Trust Layer 445, talent acquisition 337, Vertical SaaS 320, S+S Convergence 285, BPO 284, Backoffice Convergence 273, Coin 220. Themes overlap.
Top 5 vertical niches
The money follows regulated, frontline and technical specialists.
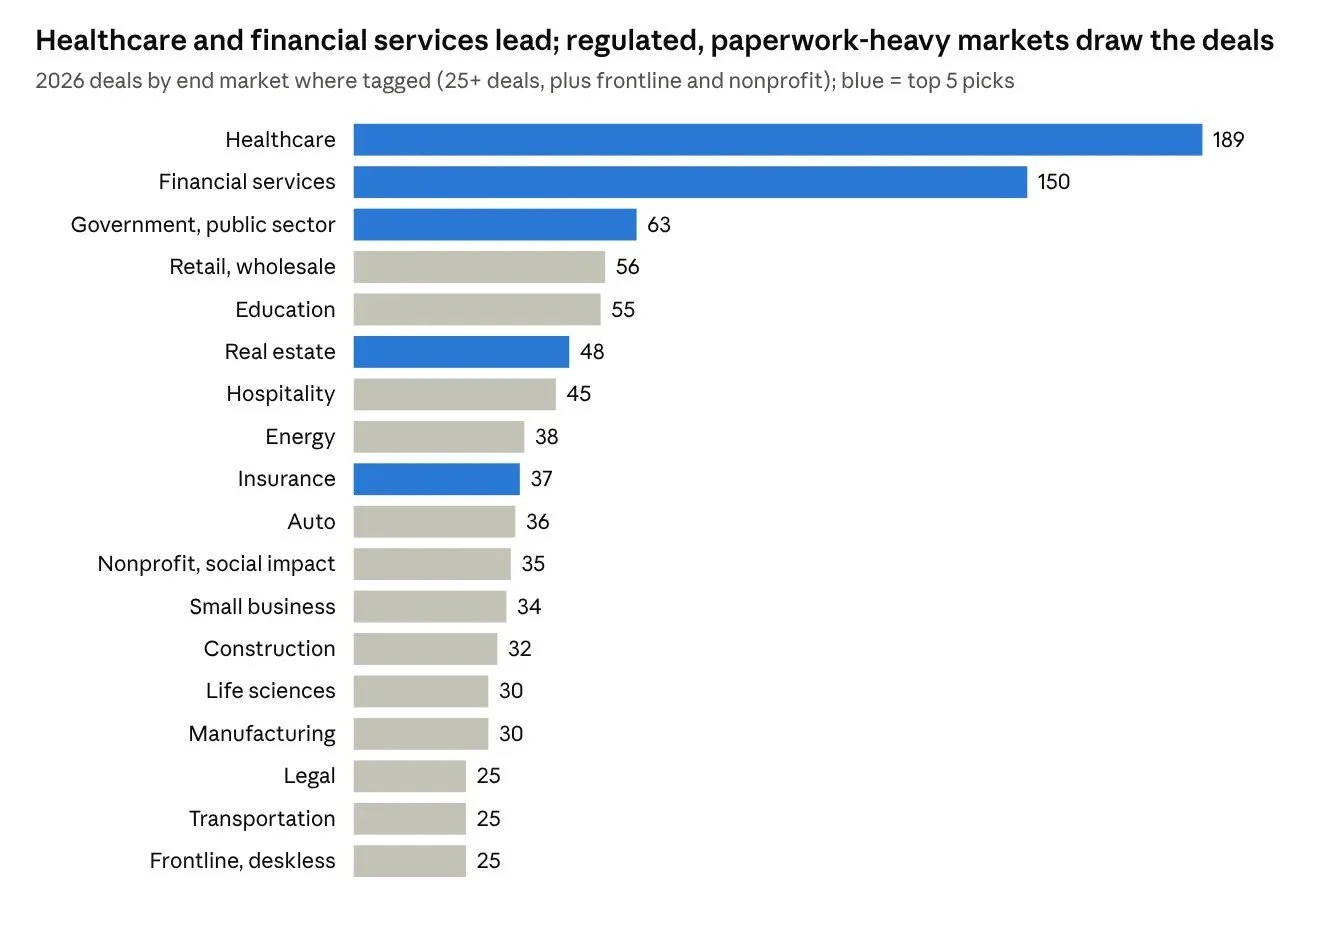
DealNet · 2026 deals with a tagged end market, Jan 1–Oct 19
| # | End market | Why it is a top pick |
|---|---|---|
| 1 | Healthcare | Largest vertical every month |
| 2 | Financial services | Steady number two |
| 3 | Insurance | Accelerating into the fall |
| 4 | Real estate and proptech | Accelerating (AppWork → Paraspot) |
| 5 | Government and public sector | Steady, compliance-driven |
Frontline and deskless: 25 deals, a keyword count that understates the category; funding is stronger (Relay $36M, Miter $40M). Nonprofit and social impact: 35 deals (WorkBuzz → HiveHR, Ticketure → Nortap). Other markets with 25+ deals: retail 56, education 55, hospitality 45, energy 38, auto 36, small business 34, construction 32, life sciences 30, manufacturing 30, legal 25, transportation 25. Most deals carry no end-market tag.
Top 2 AI trends
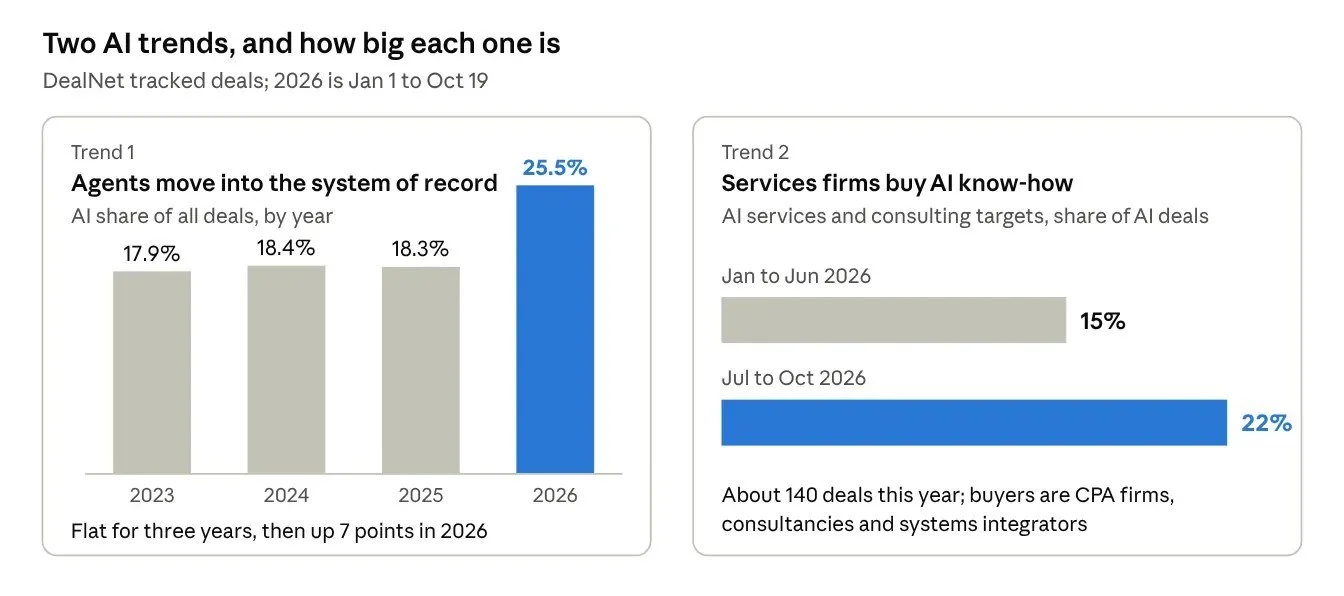
The AI premium is not reserved for model builders; it now reaches services firms that can prove working AI delivery.
| # | Trend | Evidence |
|---|---|---|
| 1 | Agents move into the system of record, and so does governing them | Workday → C1 (identity governance for AI agents), HR Path → SnapAI (AI governance), Omada → EmpowerID, Juicebox → Fetcher, Humanly → CareerArc |
| 2 | Services firms buy AI know-how | AI services and consulting targets rose from 15% to 22% of AI deals: Citrin Cooperman → Rosetree, Stout → Flightline, Qubika → Tryolabs, Analysys Mason → Modulai |
AI-themed deals: 620 in Jan–Jun and 206 in Jul–Oct 2026. AI services and consulting targets: 140 for the year. Source: DealNet.
Who buys, and how
The deal mix has barely moved in three years, which makes it a reliable guide for owner-operators planning an exit. The one notable shift: fewer sponsor-backed buyers, partly a change in source mix.
| Measure | 2023 | 2024 | 2026 YTD |
|---|---|---|---|
| Control acquisitions | 82% | 84% | 84% |
| Asset-only deals (IP sold in pieces) | 10% | 11% | 8.5% |
| Majority stakes | 7.6% | 3.9% | 5.1% |
| Strategic buyers | 52% | 49% | 48% |
| Sponsor-backed buyers | 32% | 32% | 26% |
What to watch, New Year 2027
- Agent governance as the next Trust Layer buy: identity and controls for AI agents inside HR, finance and IT.
- Implementation capacity for Workday, Dayforce, NetSuite and Salesforce: platforms keep buying partners instead of building practices.
- Leadership changes at firms: the earliest public sign a process is coming.
- Fund deployment: this fall's closes need add-ons in 2027, which keeps lower-middle-market demand high.
Method: DealNet tracks 3,280 unique 2026 deals and 2,687 signals, Jan 1–Oct 19, 2026. Theme shifts are cited only where a two-proportion test is significant (p<.05); themes overlap. Recent months fill in as data sources backfill.
What we heard in Vegas
Context was the word of the show. Walking the HR Tech expo floor, Cornerstone, Eightfold, LYTIQS, nSpire AI, Phenom, UKG, Visier and Workday all put context at the center of their materials. The message was consistent: an AI agent is only as good as the workforce data underneath it, connected across systems, governed and carrying meaning. Vendors are no longer competing on the agent alone. They are competing on who owns the context the agent runs on, how well it is orchestrated, and the business outcome.
The agents are cleaning up the backoffice. The Josh Bersin Company showed a strong slide of AI proof cases from the enterprises it works with. But on the floor, nearly every HR agent was built for the same job: removing errors and inefficiency from administration and compliance. Very few were doing advanced talent strategy or people work beyond insight reporting. Where HR and the CFO make talent decisions, it is still mostly a dashboard.
The tables below map who showed up with a context layer, which categories are thinner than the hype suggests, and which contenders can already show how their AI makes money.
AI context peers
Vendors that put a governed workforce data and context layer under their agents, not just the agents. A–Z.
| Vendor | Their context layer | Booth |
|---|---|---|
| Cornerstone | Cornerstone People Graph: context graph joining systems-of-record data with collaboration signals; debuted Workforce Planning and Agent Ready at HR Tech | — |
| Eightfold AI | Enterprise data plus 1B+ career profiles powering a suite of talent agents | 5214 |
| LYTIQS | Connects HR and finance data; IQ Assist builds workforce plans on it | — |
| nSpire AI | Practice layer that turns company methodology and training content into AI role-play | SU69 |
| Phenom | Unified talent profile across hire-to-retire, bidirectional HCM/HRIS/ATS integrations, A2A and MCP connectivity | — |
| UKG | Workforce intelligence turned into real-time decisions on staffing, pay, compliance and productivity | 4609 |
| Visier | Workforce Context Engine: maps, models and governs workforce data, then serves it to any AI agent | 5209 |
| Workday | Headless Trusted Agent Platform: any MCP agent reaches live payroll, recruiting and finance data (announced at Rising) | — |
Succession planning
Exhibitors tagged Succession & Leadership Continuity in the HR Tech directory. Core = dedicated succession product. A–Z.
| Company | Fit | What it does | Booth |
|---|---|---|---|
| AAP | Adjacent | Talent decision platform for consistent talent calls | SU44 |
| Careerminds | Adjacent | Workforce design, talent development and career transition; spans succession and outplacement | 2333 |
| Eightfold AI | Module | Talent intelligence covering mobility, career pathing and succession | 5214 |
| Enluma Leadership Group | Adjacent | Leadership development for time-strapped teams | SU90 |
| MoXaic | Adjacent | Turns manager 1:1s into performance and manager-effectiveness insight | SU83 |
| Oracle | Module | Fusion Cloud HCM, succession within the suite | 4614 |
| SuccessionHR | Core | AI-powered succession planning platform | 1910 |
| SuccessionStack | Core | Succession software that scores leaders against what the role demands | SU76 |
| Teamflect | Adjacent | Performance and engagement management | 2632 |
| tru | Adjacent | Whole-person intelligence layer on top of skills data | SU20 |
| Wisq | Adjacent | AI platform for HR with its Harper agent | 6427 |
Outplacement and exits
Exhibitors serving career transition and offboarding. A–Z.
| Company | Fit | What it does | Booth |
|---|---|---|---|
| Callings.ai | Core | Outplacement 2.0: AI job search, branding and coaching for every departing employee | 7312 |
| Careerminds | Core | Career transition in 100+ countries, tech plus human coaching | 2333 |
| INTOO | Core | Outplacement with unlimited 1:1 coaching; 25,000+ organizations | 7908 |
| Onwards HR | Adjacent | Workforce transition platform: severance and WARN/OWBPA offboarding compliance | SU17 |
| ReadyCloud | Adjacent | Remote offboarding: IT asset return | 5820 |
Source: HR Tech 2026 exhibitor directory, Oct 20–22, 2026.
The AI revenue podium: contenders
Top 3 validated AI revenue models from the floor, Oct 20–22. A company earns a podium slot only with proof of how the AI makes money: pricing, contract or customer evidence. These contenders are positioned to win. A–Z.
| Company | Category | AI product | Revenue model | Proof so far |
|---|---|---|---|---|
| LYTIQS | Talent Intelligence | IQ Assist | Bundled | Aug26: launched IQ Assist, building a workforce plan in minutes instead of months |
| nSpire AI | Learning & Coaching | Sage: AI video role-play for critical conversations | Freemium + enterprise | Oct26: launched Sage at HR Tech; feedback scored against company methodology for intelligent coaching |
| RSight | Talent Acquisition | RSight Agentic AI | Outcome | Nov25: Gartner Peer Insights lists it as outcome-priced agentic AI recruiting |
| Sidenote | Work Tech (AI compliance) | Real-time workplace communications coaching agent | Subscription | Sep26: agent flags legal and policy risk in drafts before send, on customer infrastructure |
| SonicJobs | Talent Acquisition | Jobs surfaced inside ChatGPT; career-site GPT | Subscription | Aug26: Hosted Apply agents lift application completion from ~5% to ~26% |
| Warden AI | Work Tech (AI compliance) | Warden Assured: independent audits of HR AI | Subscription | Jun26: PageUp completed Warden AI certification with monthly fairness audits |
| ZeroedIn | Talent Intelligence | AI workforce analyst: capacity modeling and feedback intelligence | Bundled | Oct26: launched AI*Analyst at HR Tech; every answer traced to its measures and time period |
Investor-backed leaderboard
Funded leaders across the exhibitor expo hall.
| Company | Investment funding | Why winning |
|---|---|---|
| Persona | $418M raised | Identity verification moving into hiring fraud, the year's most urgent HR risk |
| Awardco | $235M raised ($165M Series B, 2025) | Recognition programs plus a rewards marketplace; ~680 staff |
| Deputy | $131M raised | Frontline scheduling at scale; AI fills coverage gaps |
| Findem | $73M raised | Talent data plus AI agents from sourcing to workforce planning |
| Clair | $100M run rate; ~$68M raised | Embedded EWA in Gusto, Check, 7shifts; 10x YoY, cash-flow positive |
| People Data Labs | $55.5M raised | Data layer for AI HR tools; usage pricing |
| Enboarder | $50.5M raised | AI agents for lifecycle orchestration; tests "onboarding isn't sold alone" |
| 401GO | $49M raised ($33M Series B, Dec 2025) | 401(k) embedded through payroll partners; headcount +43% YoY |
| One Model | $47M raised | People analytics data cloud with an AI assistant |
| Cronofy | $37M raised | Scheduling infrastructure embedded inside ATS and HR platforms |
| ZayZoon | $36M raised | EWA and rewards sold through payroll partners; headcount +13% YoY |
| Wisq | $35M raised | AI HR agent for employee service delivery |
| Harmony | $34M seed (Jul 2026) | AI service-desk agents across IT and HR; founded 2025 |
| Goody | $32M raised | Employee and client gifting; headcount +28% YoY |
Sources: Oct 2026; company announcements.
Want this view for your category?
The signals that move value are rarely the loud ones. Charles Bedard builds analyst comps and corporate development briefings for founders, operators and investors: who is winning in your category, which AI revenue model is working, and which buyers and investors are active now.
Request your analyst briefingFounder questions, answered
What was the main finding from HR Tech 2026?
Retention, not the hire, is the outcome buyers pay for. AI wins when it sells that outcome; workflow alone is now table stakes, and standalone modules such as ATS, compliance, onboarding and succession planning get absorbed into platform suites.
How much of Work Tech M&A is AI in 2026?
About 30% of tracked 2026 Work Tech deals are AI-themed, up from about 1 in 5 for the prior three years. It is the one clean long-term shift in the market; other themes are steady or cyclical.
Who is buying Work Tech companies?
84% of 2026 deals are control acquisitions. Strategic buyers make up 48% and sponsor-backed buyers 26%. Only 339 of 3,280 tracked deals disclosed a price, and 175 of those were $50M or less.
What signal usually comes before a Work Tech deal?
Leadership change. 961 of 2,687 signals tracked in 2026 (36%) were executive moves. A new President, CFO, CRO or CTO is often the first visible step toward a sale, a recap or a platform build.
Read more: Ahead of HR Tech 2026: Where the Capital Is, and What the Agenda Covers
