
ERP as we knew it is dead. Long live the new era kings.
NetSuite ecosystem analyst finding · Charles Bedard, Corporate Development Analyst · Winter 26/27
SuiteWorld 26 Finding
The Autonomous Suite Era Is Now Here
ERP as we knew it is dead. Long live the new era kings.
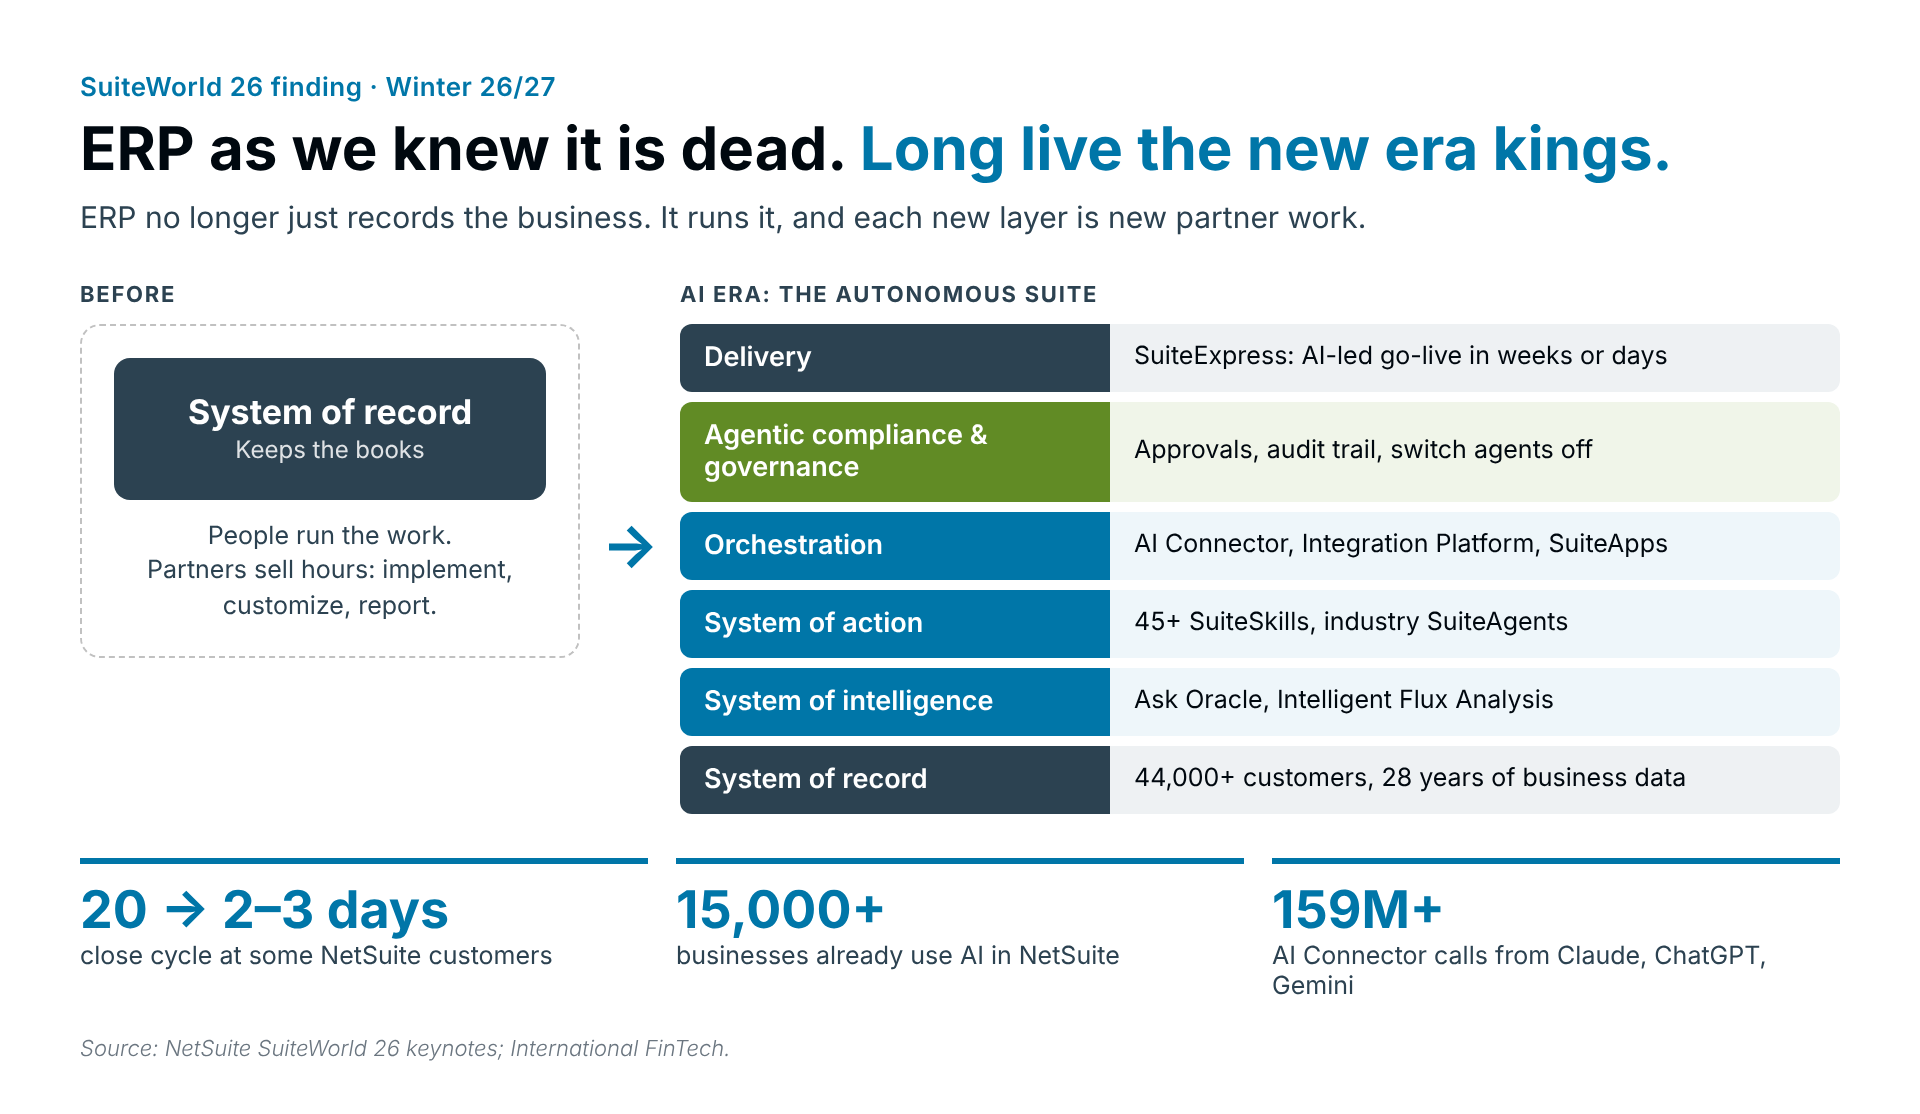
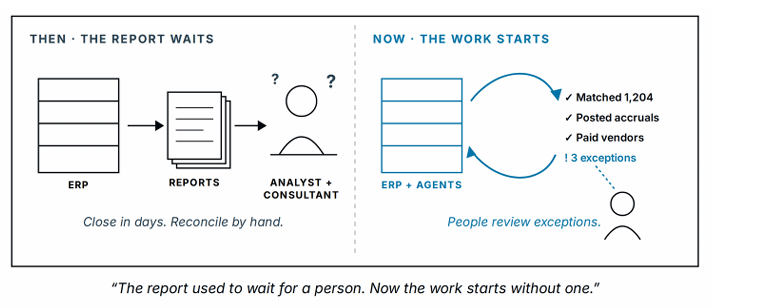
Oracle NetSuite is moving from a system of record to a system of action, and every new layer is new partner revenue. AI delivers ERP the way customers always wanted it: insights (Ask Oracle) and autonomous SuiteAgents (NetSuite Next plus industry solutions with context) take the place of delays and limits.
Why customers pay, and why now
Why customers pay
Finance teams are shifting work from accounting and compliance to analysis and advisory. Finance gets its time back, and more. Customers will no longer pay for hours or seats, only outcomes.
Why now: the maturity curve, from insights to action to outcomes
- The Close (insights): Some NetSuite customers have cut the close from 20 days to 2–3 (iTWire).
- The Control (action): AI saves finance operations staff an average of 21 hours a week (BILL).
- The Cash (outcomes): Cash in faster. 3 in 4 AI AR users cut DSO 6+ days (Billtrust).
Capital
Since Jan25, close and ledger companies raised about 12 times more than AP and AR. 55% of NetSuite software partners are investor-backed, versus 12% of services partners (DealNet).
So what
The premium goes to partners who own a layer: industry agents, controls, orchestration or usage billing. Value moves from billable hours to owned solutions.
Finding supporting evidence
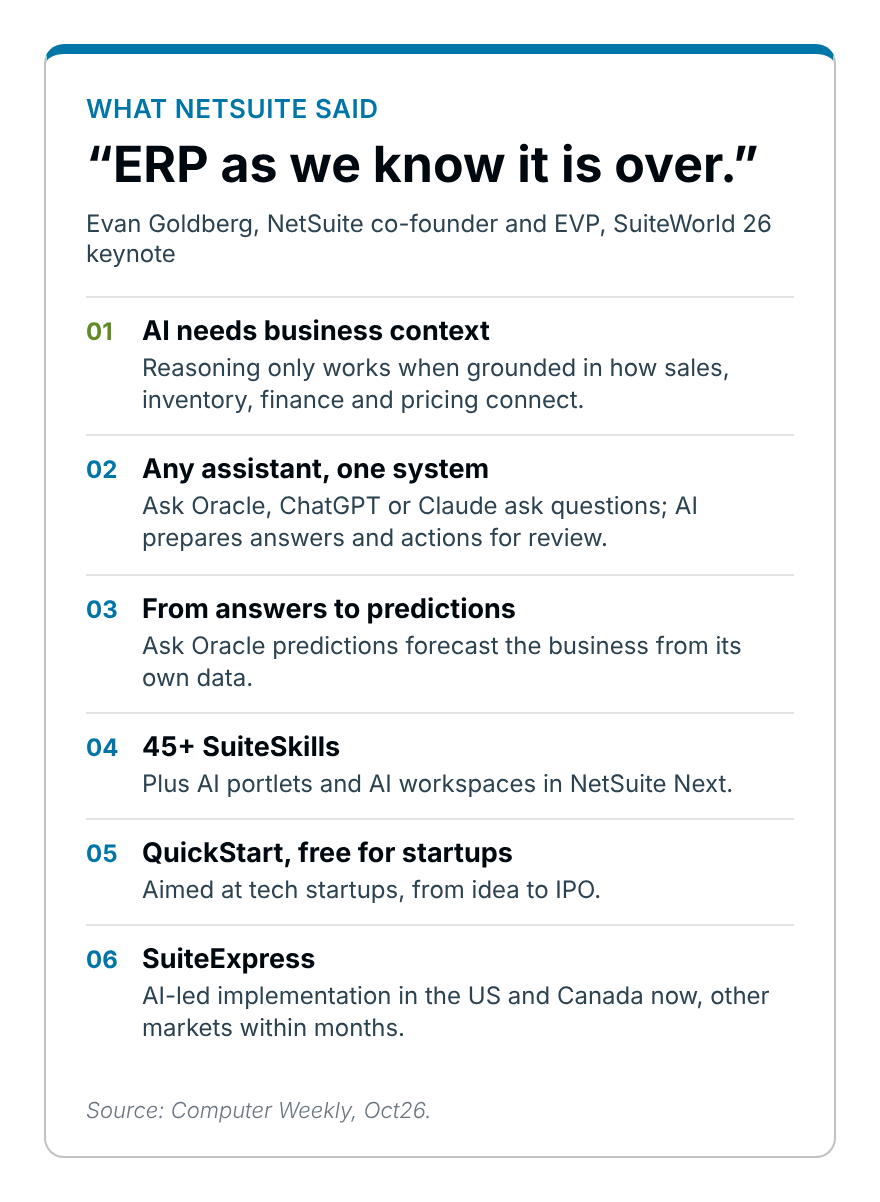
- “ERP as we know it is over.” Evan Goldberg, NetSuite co-founder, SuiteWorld 26 keynote (Computer Weekly, Oct26).
- Close: some customers cut the close from about 20 days to 2–3 (Futurum; NetSuite keynote).
- Control: AI saves finance operations staff 21 hours a week; survey of 500 SMB and midsize finance leaders (BILL 2026 State of AI in Finance).
- Cash: 99% of companies using AI in AR cut DSO, and 75% of them by 6+ days; survey of 500 finance decision-makers (Billtrust).
- Adoption: 15,000+ businesses use AI in NetSuite; 13,000+ customers made 159M+ AI Connector calls (International FinTech).
- Capital: close and ledger companies raised ~$341M since Jan25 vs ~$28M for AP and AR; 55% of software partners investor-backed vs 12% of services partners (DealNet).
What Oracle told investors
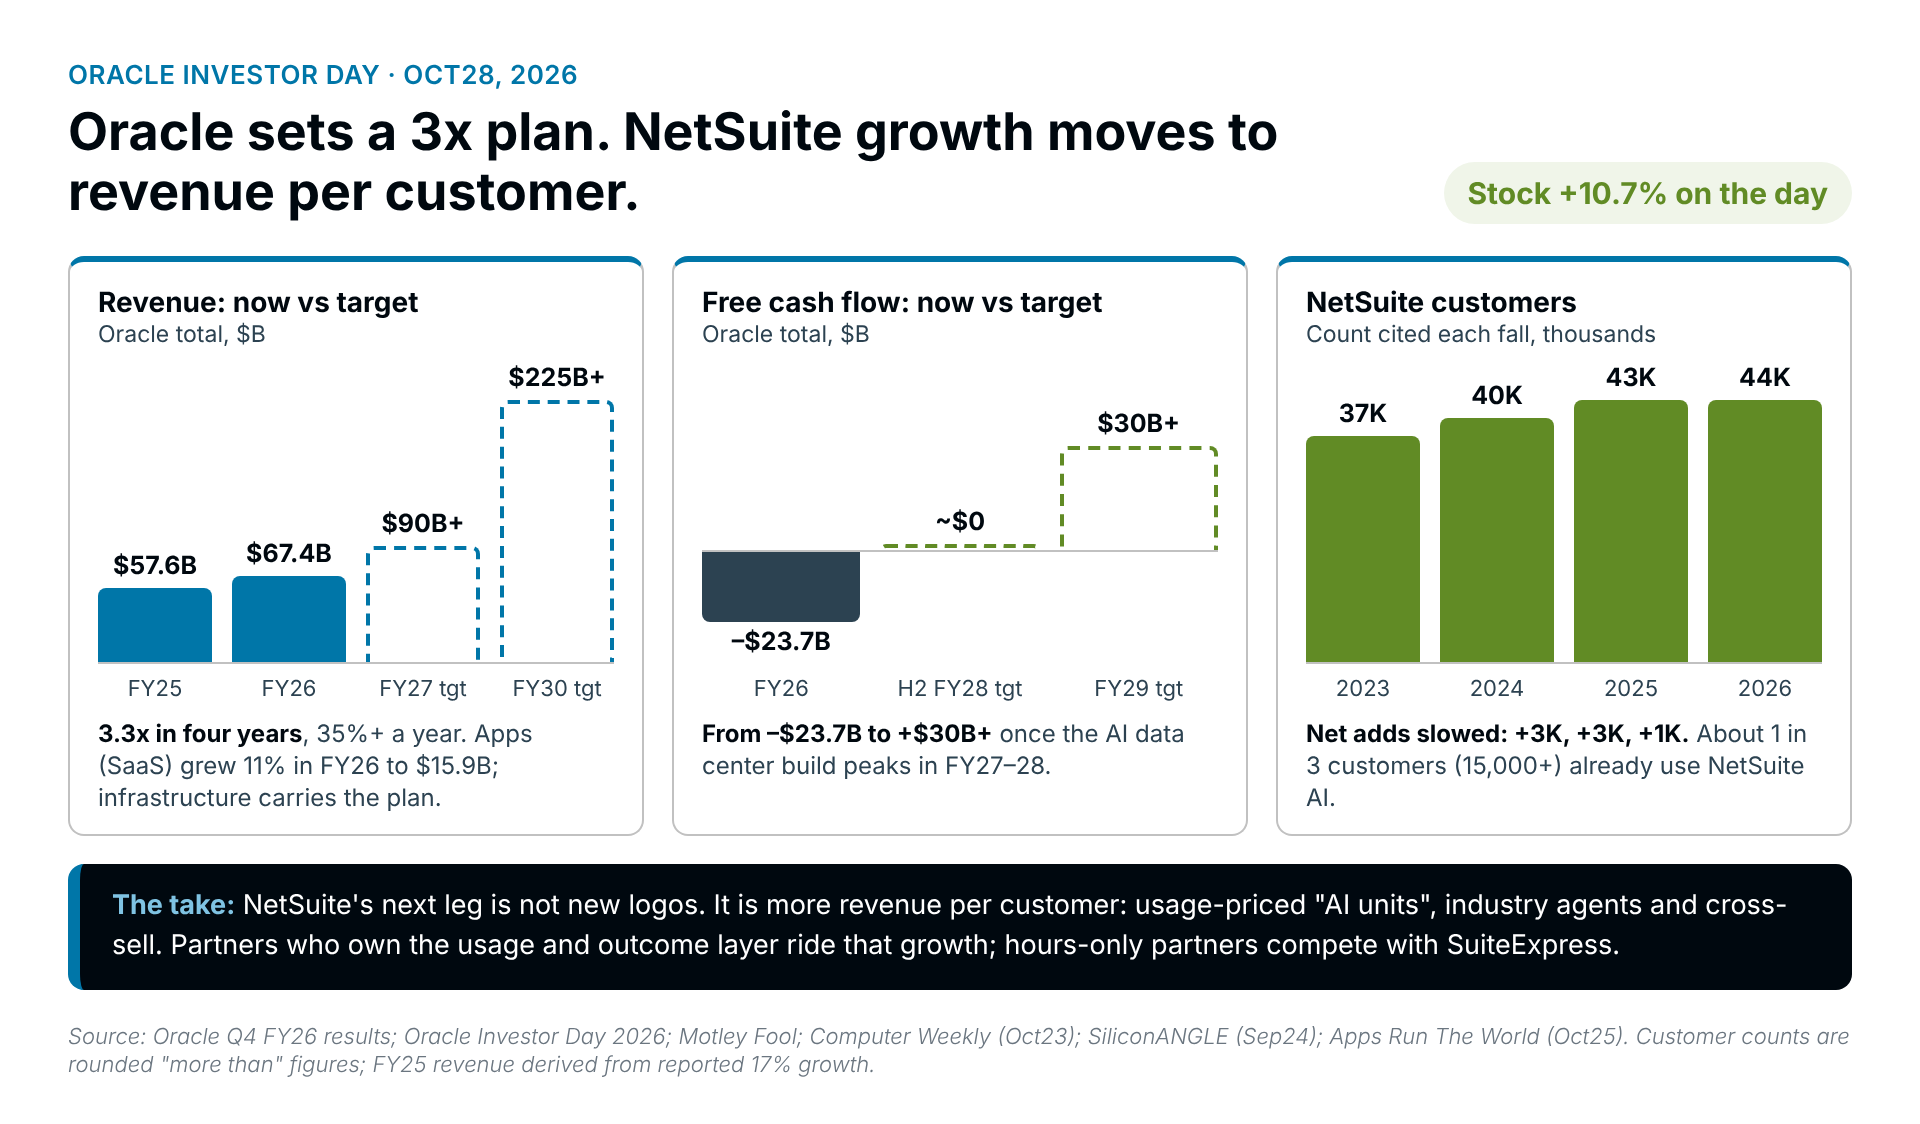
Oracle held its Investor Day at Oracle AI World on Oct28, and the stock rose 10.7% that day. Oracle's results report NetSuite as one line, so most of the NetSuite signal is in what Oracle's leaders said:
- Mid-market focus: 44,000 NetSuite customers, moving from a "piecemeal" approach to combined horizontal and industry offerings, which backs the Industry SuiteAgents headline.
- AI is the UI: "In NetSuite Next, AI is the UI," in Oracle's words. This supports the main finding.
- Usage pricing at Oracle itself: "AI units" add a usage-based revenue layer on top of seats, and payments are framed as outcome-based revenue. This supports finding 3.
- Agents at scale: 75 agentic applications and 5.7M agent runs in a quarter, with agents built in weeks, not months. This raises the governance stakes in finding 2.
- Faster implementations: new tooling cuts 50–70% of the mechanical implementation work. Billable hours compress, so partners need to own a layer.
- NetSuite in the numbers: $1.1B revenue in Q4 FY26, up 9%, while Oracle infrastructure grew 93%. NetSuite is steady; Oracle's growth capital goes to AI data centers.
- Cross-sell: a North American cross-sell opportunity of more than $5B, with a 3x–4x revenue lift when a customer moves to cloud.
Source: Oracle Investor Day 2026 transcript; Oracle press release; Motley Fool.
SuiteWorld 26 headlines
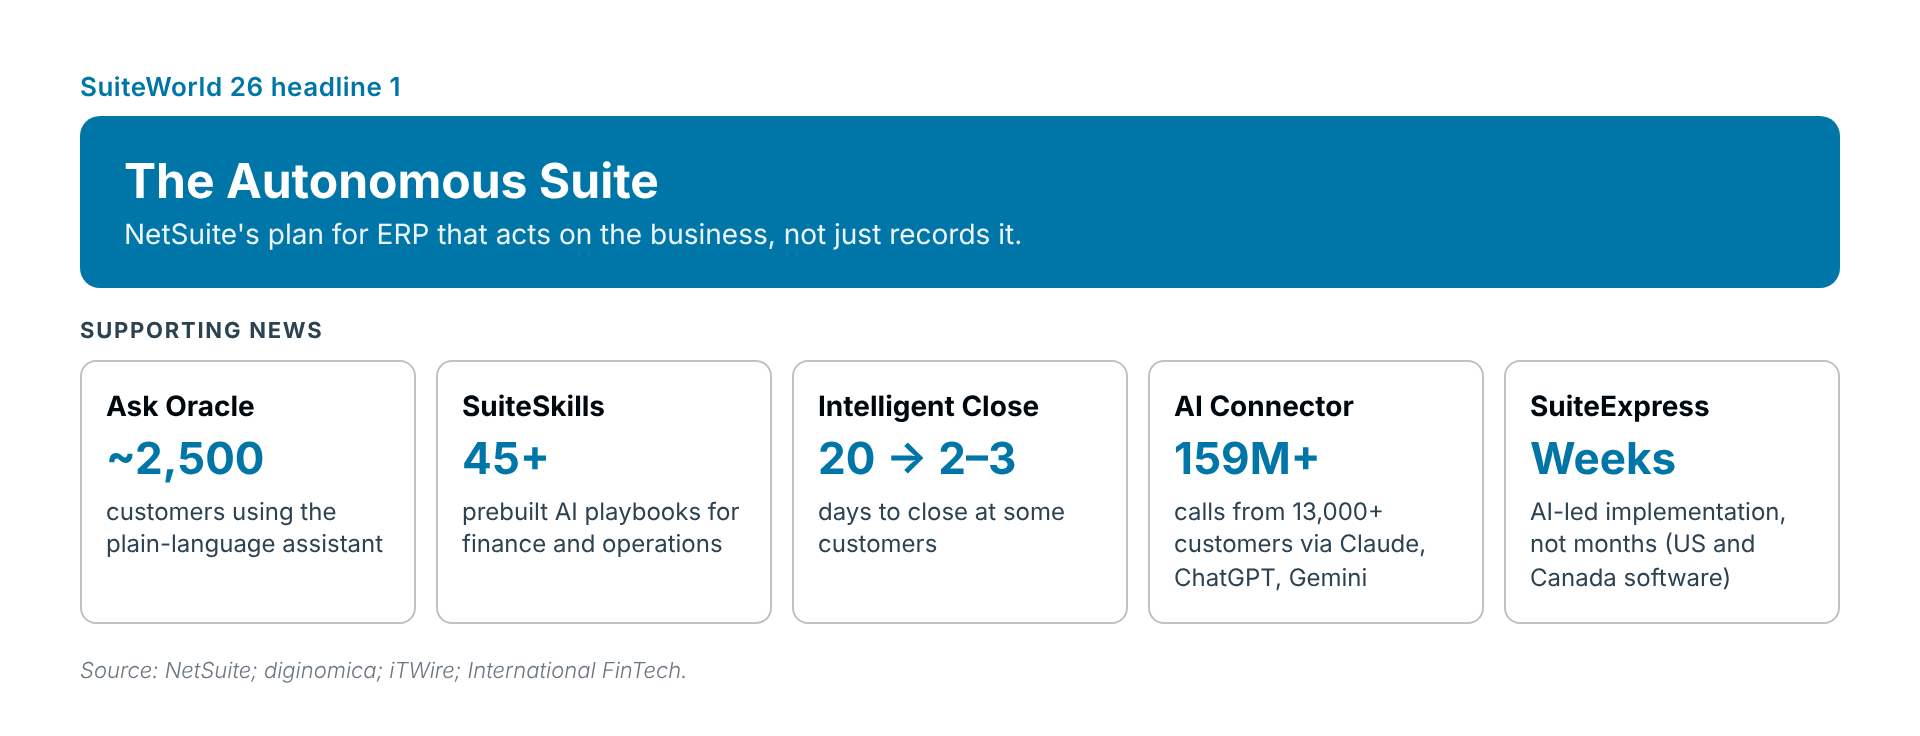
- The Autonomous Suite. NetSuite set out its plan for ERP that acts on the business, not just records it (Enterprise Times).
- Ask Oracle. A plain-language assistant for answers, reports and routine tasks, now in NetSuite for US and Canada customers, with about 2,500 customers so far (NetSuite 2026.2).
- SuiteExpress. AI-led implementation that cuts projects to weeks or days, now available to US and Canada software customers (NetSuite press release).
- AI Connector. 13,000+ customers have made 159M+ calls from Claude, ChatGPT and Gemini into NetSuite (International FinTech).
- 45+ SuiteSkills and the Intelligent Close workspace. Reusable AI playbooks and a close dashboard; some customers cut the close from about 20 days to 2–3 (NetSuite keynote via iTWire).
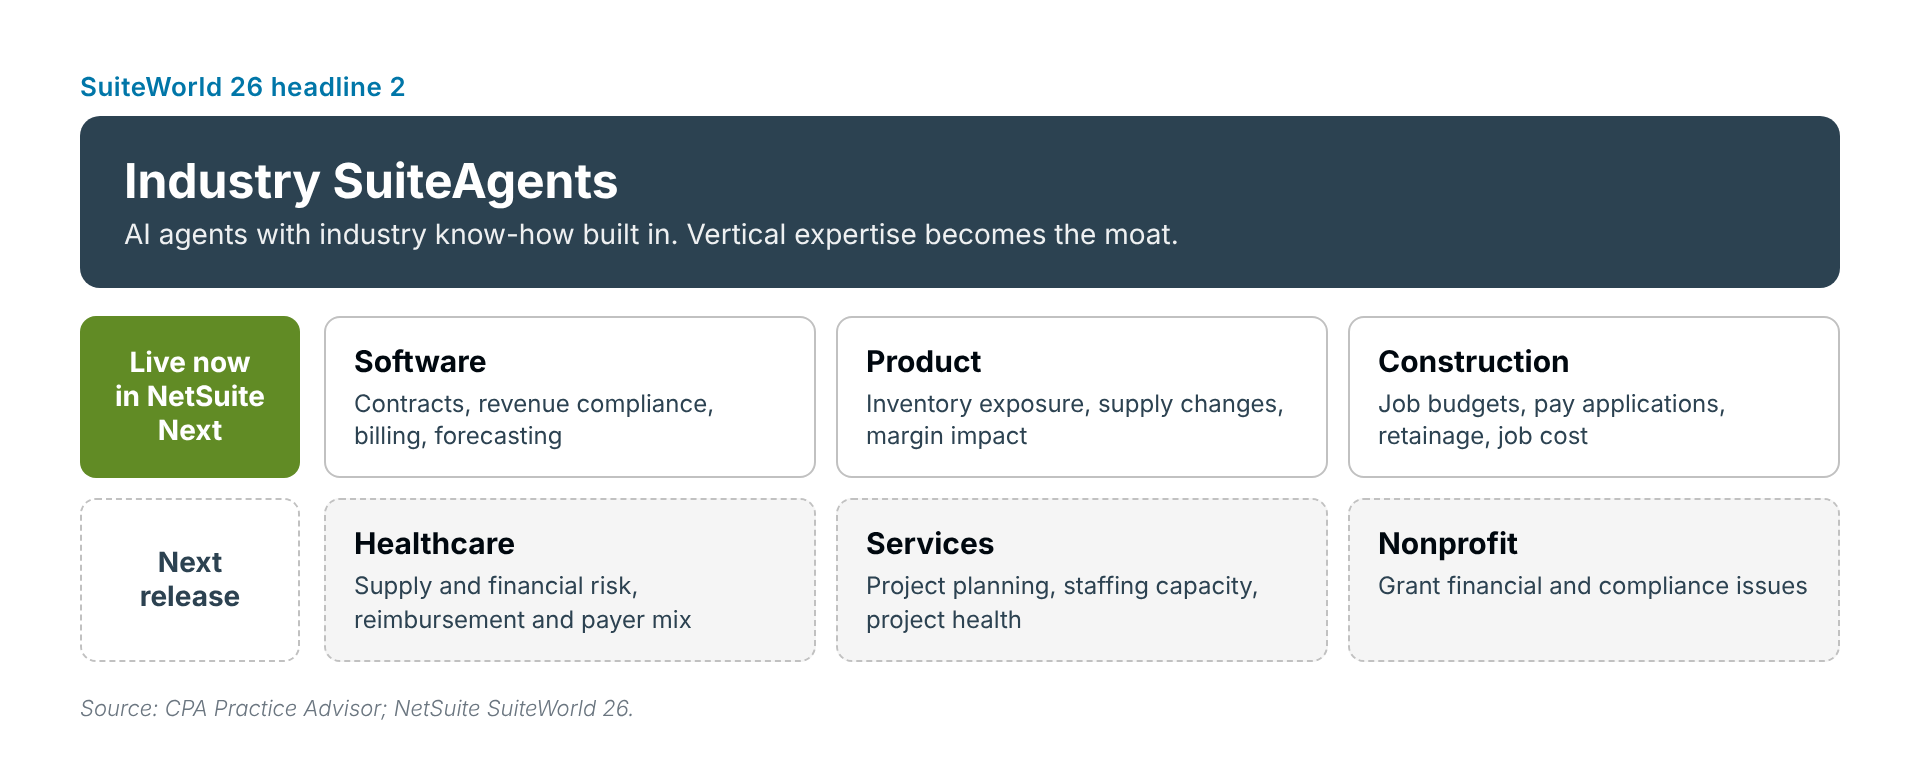
- Industry SuiteAgents. Agents for software, product and construction companies are live in NetSuite Next; healthcare, services and nonprofit come in a later release (CPA Practice Advisor).
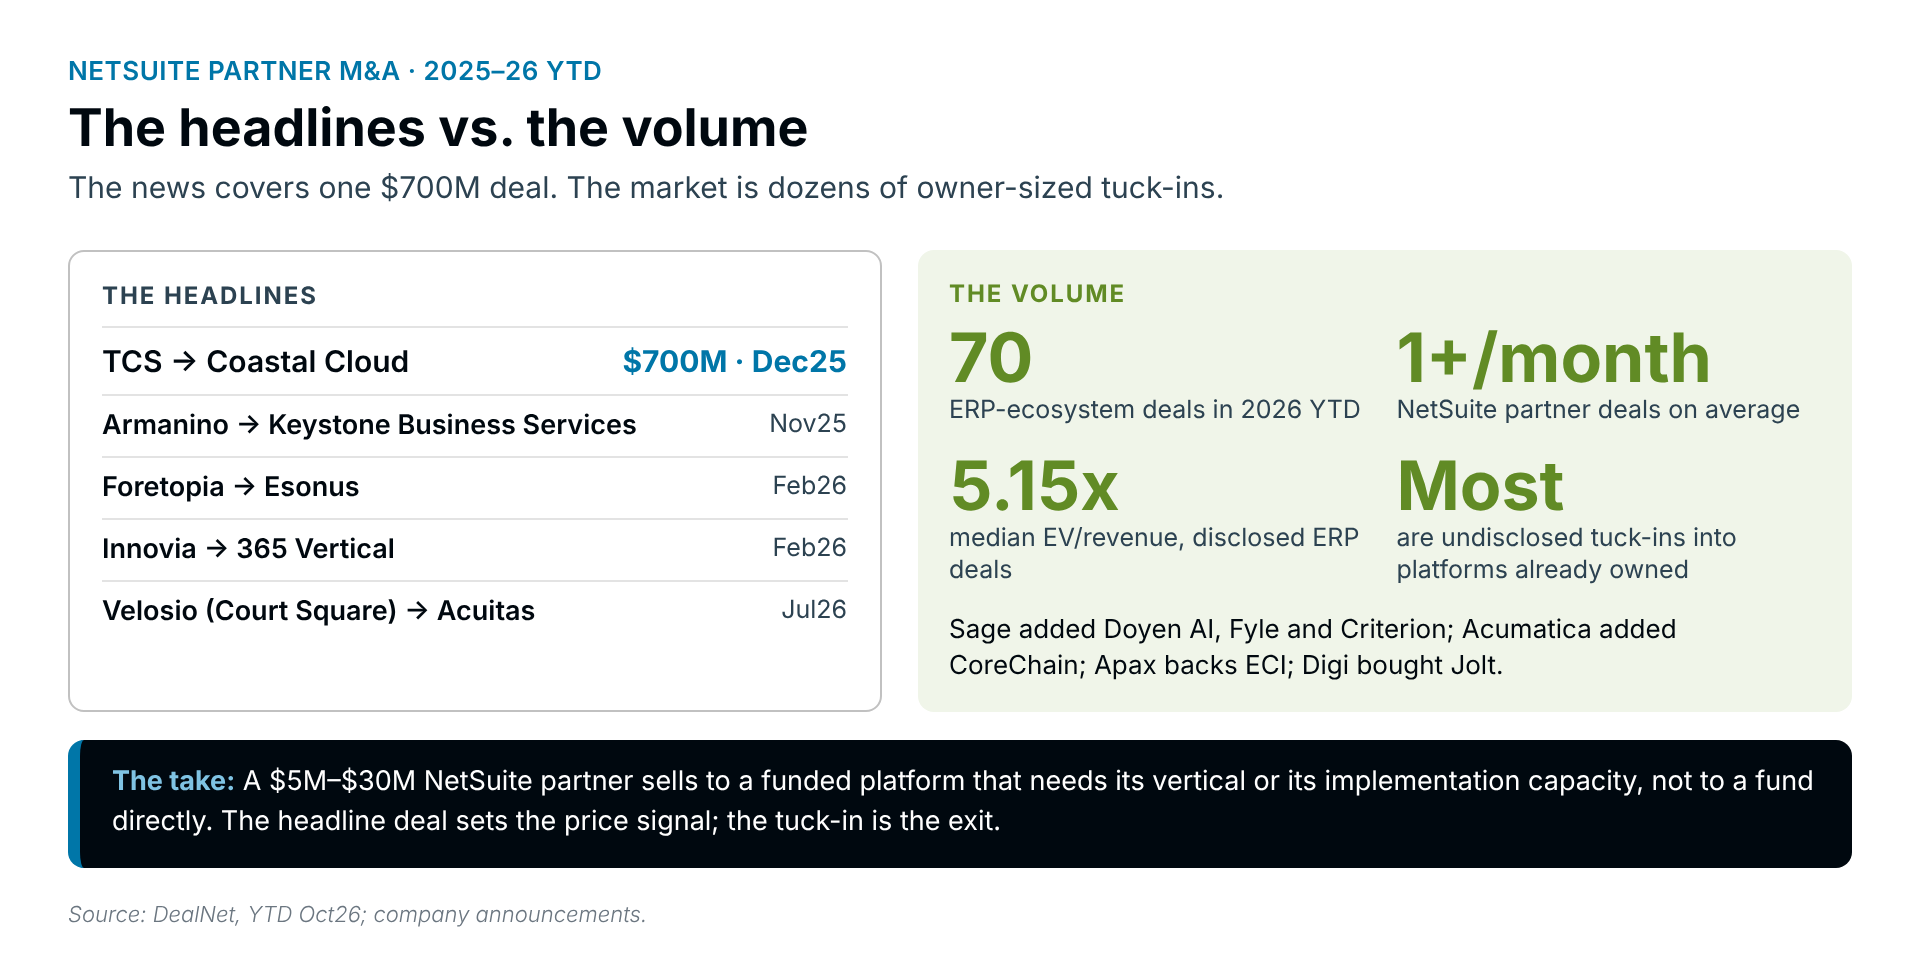
The headlines vs. the volume
SuiteWorld headlines go to the platform. The deal flow underneath is owner-sized partner tuck-ins, the same pattern we found in Work Tech.
Four findings from SuiteWorld 26
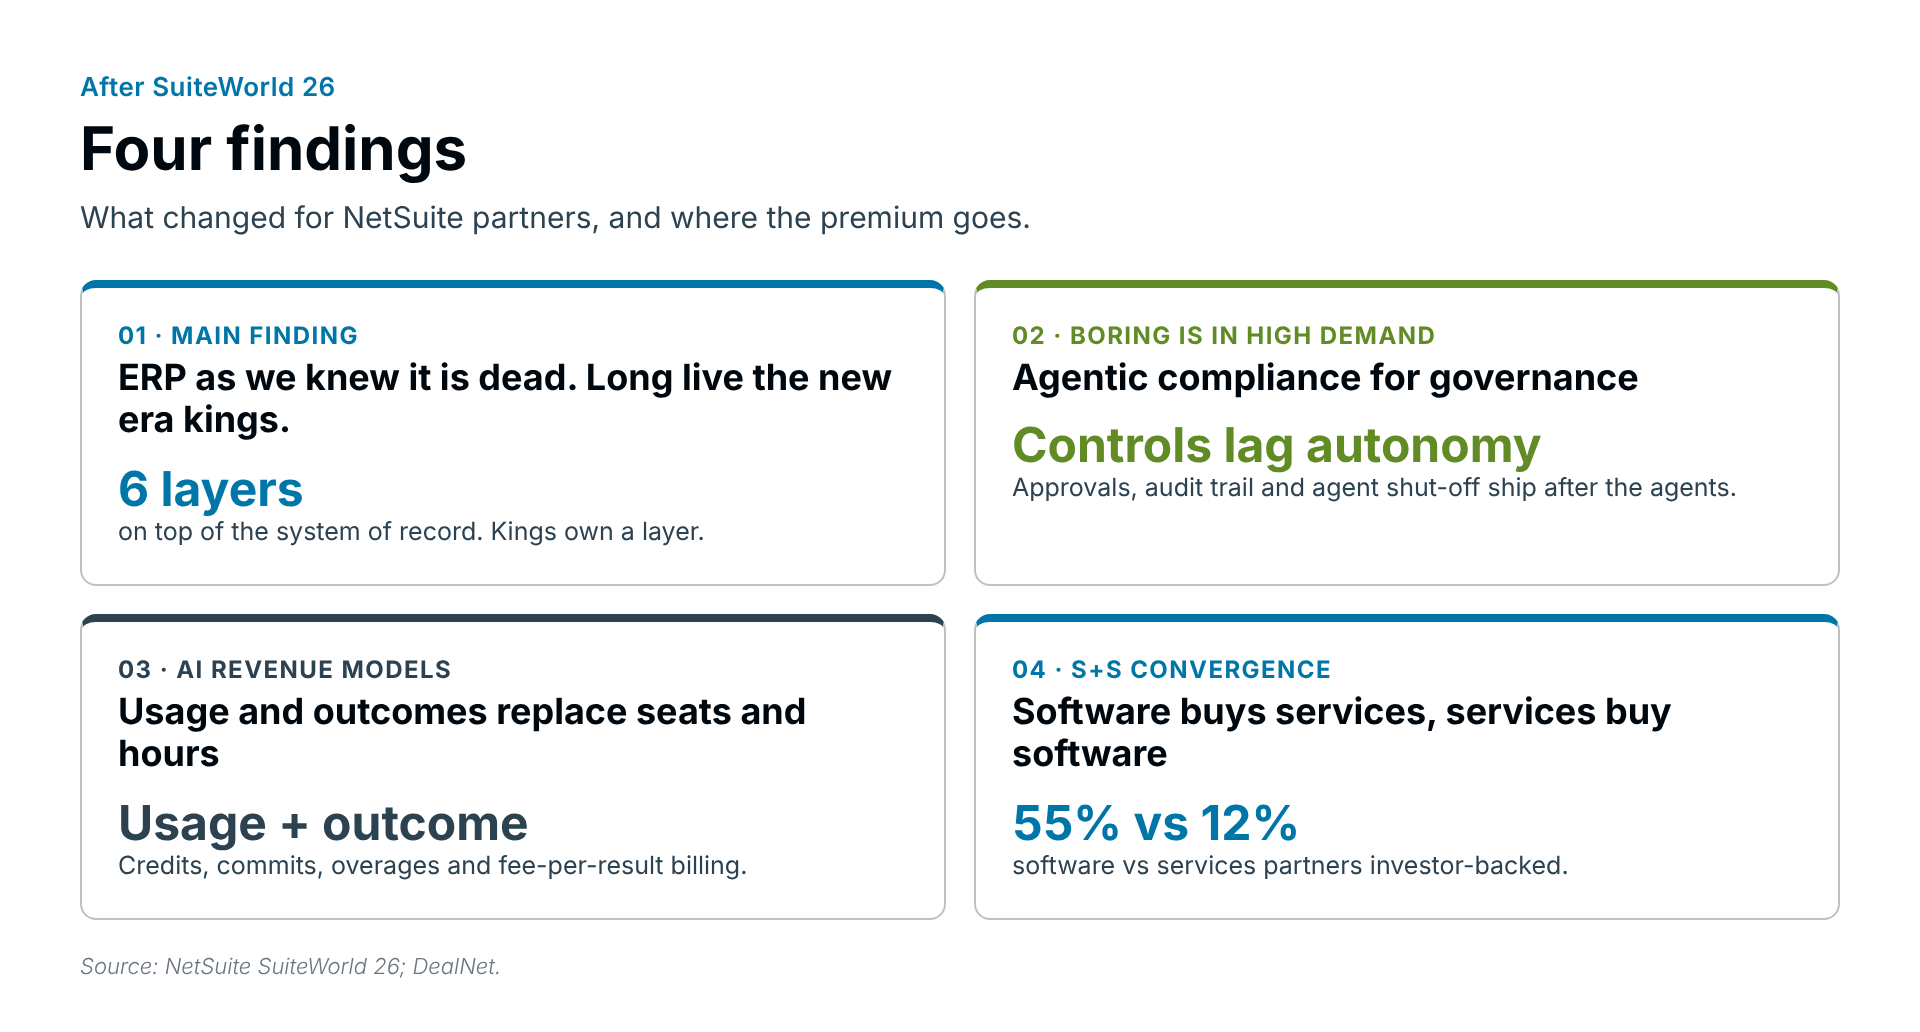
1. ERP as we knew it is dead. Long live the new era kings. ERP is no longer only the system of record
NetSuite used SuiteWorld to move ERP from recording the business to running it. The system of record now carries a system of intelligence, a system of action, orchestration and agentic compliance and governance on top, and AI is changing how customers go live. Each new layer is new partner work.
| Layer | What it does | What NetSuite showed | Partner opportunity |
|---|---|---|---|
| System of record | Keeps the books | 44,000+ customers, 28 years of business data, 10,000+ connections between business objects | Implementation, data migration |
| System of intelligence | Explains what happened and why | Ask Oracle, Intelligent Flux Analysis, NetSuite Data Intelligence | Analytics, FP&A |
| System of action | Does the work | 45+ SuiteSkills; SuiteAgents for software, product and construction | Industry agents and SuiteApps |
| Orchestration | Connects agents, apps and data | AI Connector (13,000+ customers, 159M+ calls); agent-driven orchestration in the Integration Platform | Integration and iPaaS |
| Agentic compliance and governance | Controls and audits what agents do | Roles, permissions and approvals; Agent Management Workspace; SuiteAgent Studio to come | Controls, testing, audit |
| Delivery | Gets customers live | SuiteExpress: AI-led implementation in weeks or days | Solutions over hours |
Source: NetSuite SuiteWorld 26 keynotes and announcements; iTWire; International FinTech; NetSuite 2026.2 release.
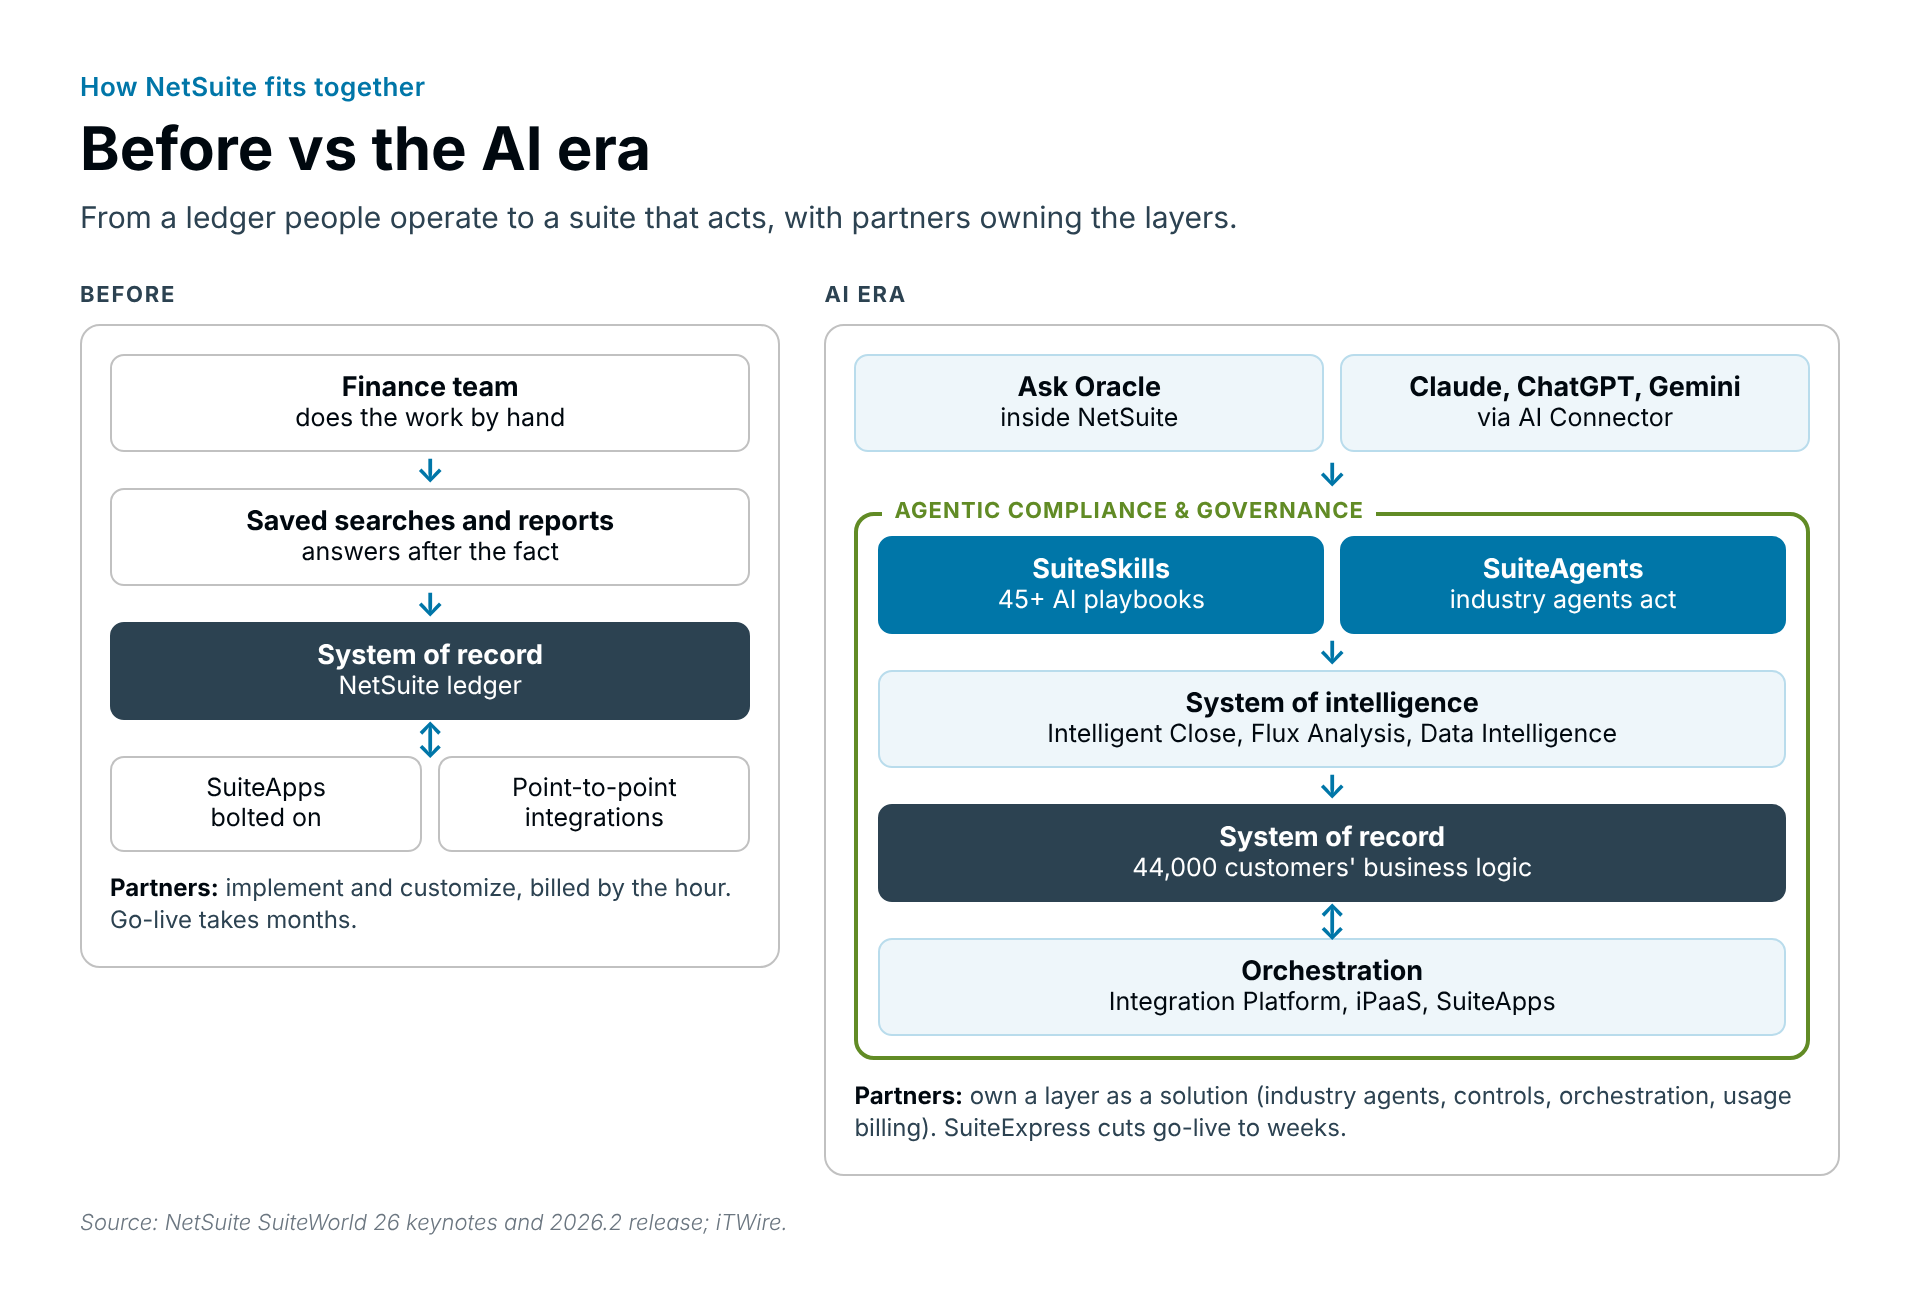
Customers pay for the layers that act: some have cut the close from about 20 days to 2–3, and more than 15,000 businesses already use AI in NetSuite. Capital is following. Close and ledger companies raised about $341M since January 2025, against about $28M for AP and AR. A partner that only implements the system of record now competes with SuiteExpress; the premium goes to the partner who owns a layer.
2. Boring is in high demand: agentic compliance for governance
Once agents act, someone has to answer for what they do: audit trails, approvals, testing and the ability to switch an agent off. Finance teams will not sign numbers an agent assembled until auditors accept the trail. Futurum's Keith Kirkpatrick: “Whether finance teams will trust agents with the close remains the open question” (Futurum). NetSuite's own controls, SuiteAgent Studio and the Agent Management Workspace, are still arriving after the autonomy. Audit has drawn about $30M in disclosed funding since January 2025, small next to close, which leaves room. Controls, testing and audit work come with every agent a customer turns on.
3. AI revenue models move to usage and outcomes
AI vendors, and NetSuite itself, are pricing on usage and outcomes rather than seats and hours. NetSuite's free QuickStart for early-stage startups is capped by usage, and SuiteExpress turns implementation hours into a delivered result (diginomica). Tabs, an AI revenue platform that integrates with NetSuite, shows how AI products are billed now:
| Billing model | What Tabs runs | AI-era use | Proof so far |
|---|---|---|---|
| Usage / metered | Ingests usage in real time, rates it and invoices it | API calls and compute | Alkira: thousands of usage data points invoiced monthly |
| Prepaid credits | Customer pays upfront and draws credits down | AI credits | — |
| Commit + overage | Tracks usage against a minimum spend; overage at standard rates | Enterprise AI contracts | — |
| Hybrid | Base subscription plus usage on one invoice | Seat plus AI add-on | 30%+ of customers moved to usage pricing in under 30 days (company claim) |
| Outcome-based | Bills on results, such as a fee per resolution | AI agents priced per outcome | — |
| Contract-to-invoice AI | Reads contracts, sorts billing terms, creates invoices | Removes manual billing setup | Statsig: 3x invoice volume with no added headcount |
Tabs raised a $55M Series B led by Lightspeed (Sep25). Source: Tabs billing models; Tabs; BusinessWire.
For partners, usage billing, revenue recognition and order-to-cash skills become core NetSuite work, and SuiteBilling was not built for AI pricing.
4. S+S Convergence
NetSuite is a platform. The partners who turn it into a solution are the ones buyers will pay for, and the M&A has just reached them.
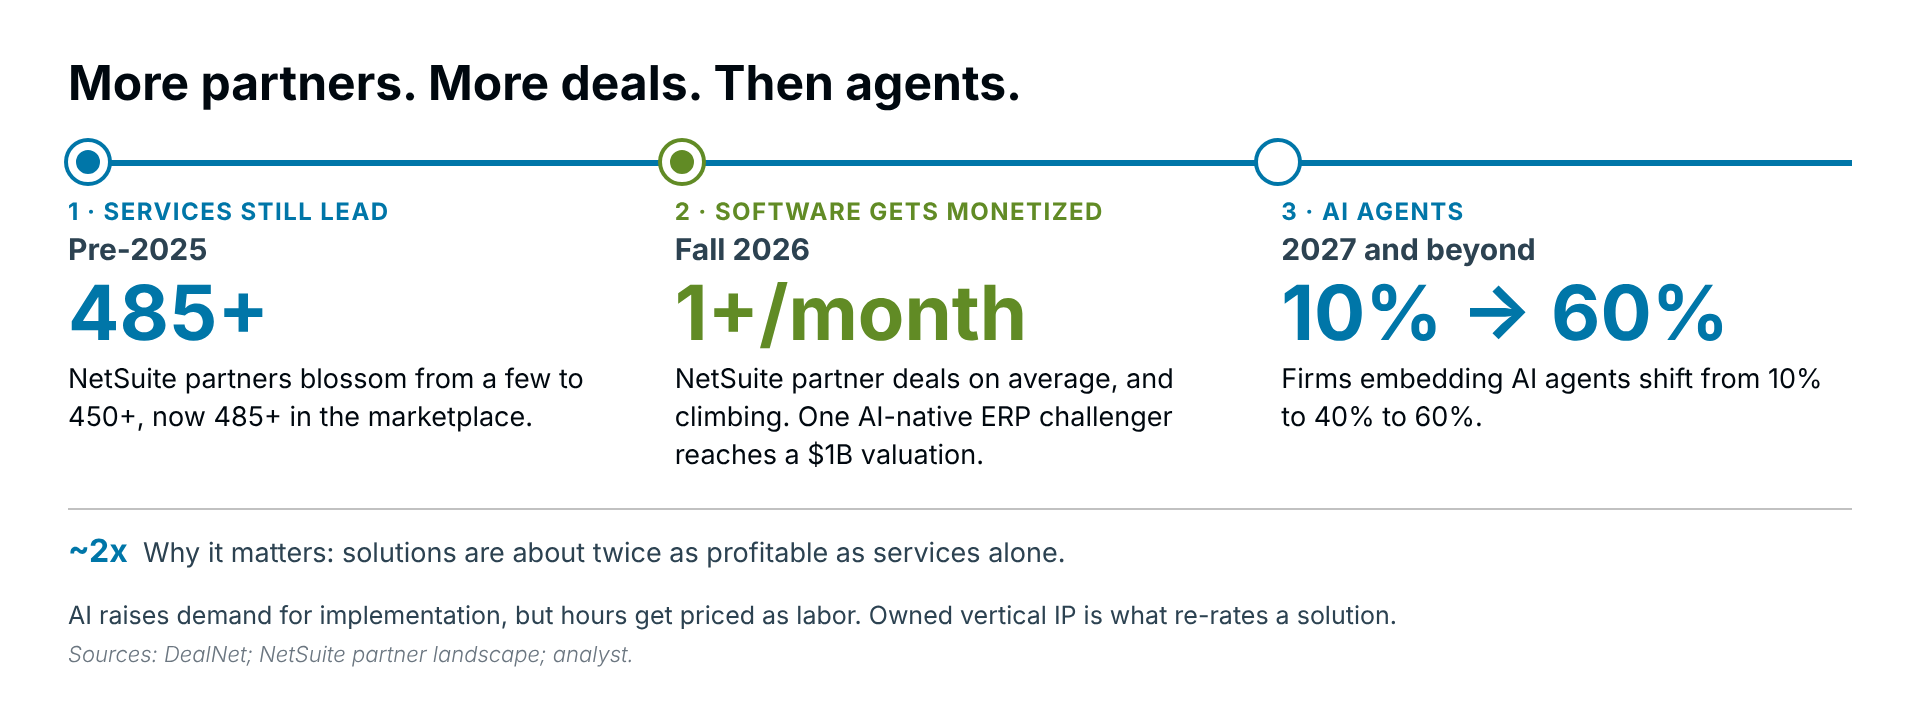
Our NetSuite ecosystem analyst briefing tracks 2K+ DealNet signals and 70 ERP-ecosystem deals so far in 2026, across 485+ NetSuite partners: implementation, consulting, accounting, SuiteApp software and BPO. Below are the headlines from SuiteWorld (Las Vegas, October 25–28), the three findings we took away, and the M&A finding driving deals right now.
The M&A evidence
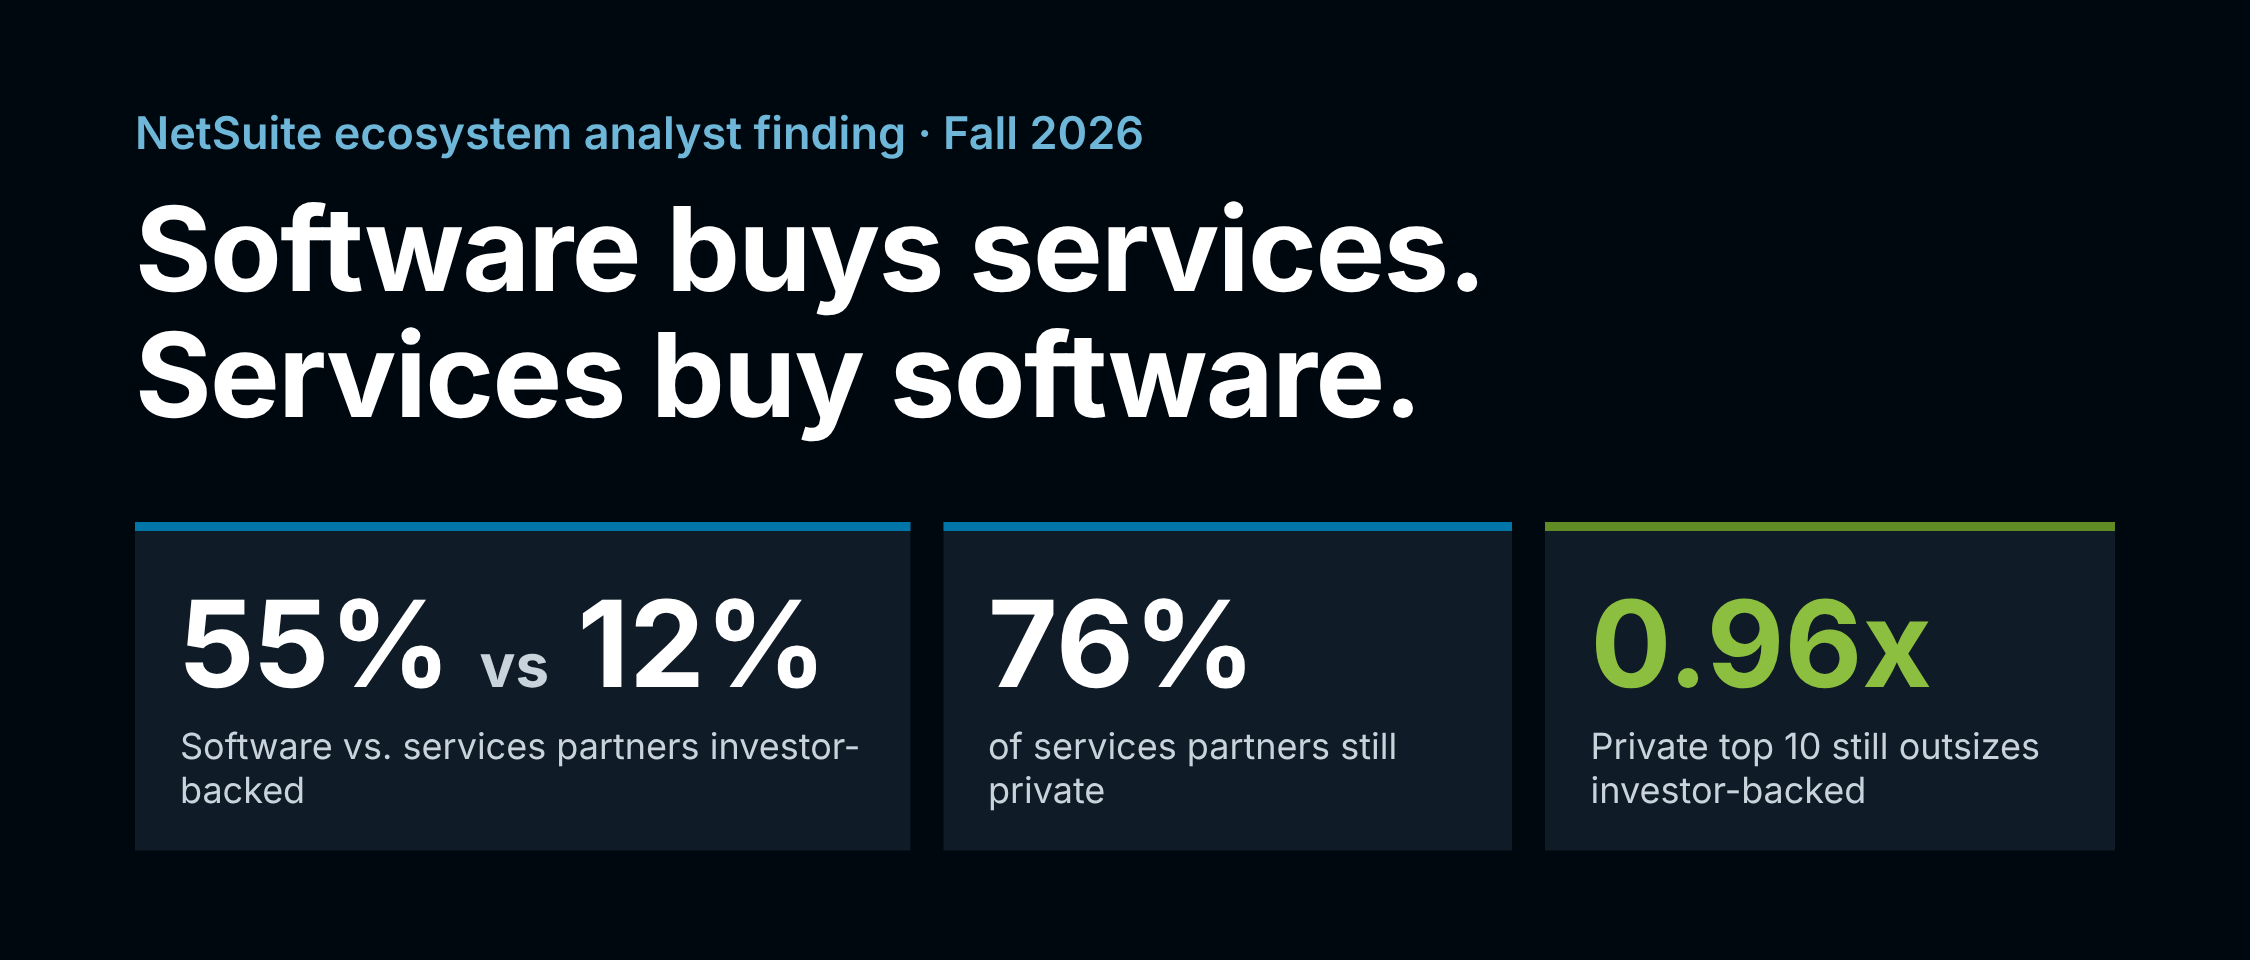
Software is buying services, and services are buying software, in a race to deliver outcomes in the AI revenue model era.
Customers now buy outcomes, not licenses or hours. Capital has backed the software side: 55% of NetSuite software partners are investor-backed, versus 12% of services partners. The services partners that deliver the outcome are still mostly private, and that is where the next deals land.
The partners who get premium prices will be the ones who own software IP and deliver solutions as well as hours.
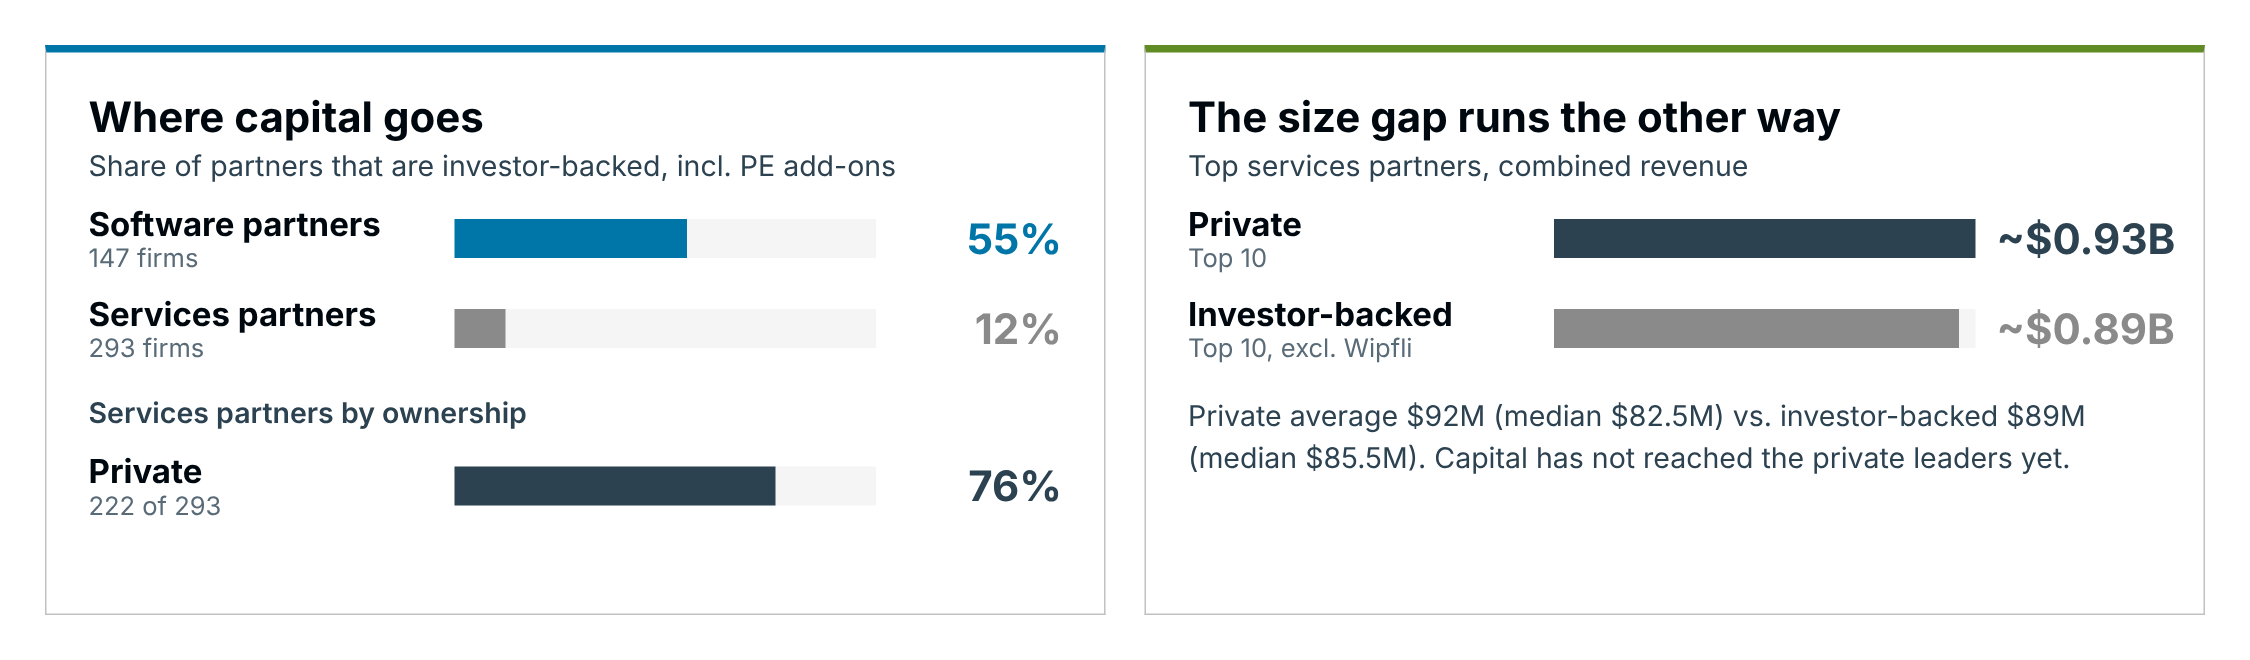
Source: DealNet. Services partners only (implementation, consulting and accounting). Wipfli (~$923M, investor-backed) is excluded because its full CPA-firm revenue distorts the comparison.
Five stats that highlight the market trend
NetSuite is the platform. The premium goes to the solution.

Source: Oracle NetSuite partner programs.
NetSuite sorts its partners by program. Buyers sort them by model. A platform is software others build on. A solution provider delivers services directly and owns proprietary software. Both are required.
Most NetSuite partners sell hours: implementation, consulting, accounting. Hours get priced as labor. The partners that own software IP, such as SuiteApps, connectors or managed workflows, and deliver the outcome as a solution are the ones that re-rate.
AI raises demand for implementation and orchestration
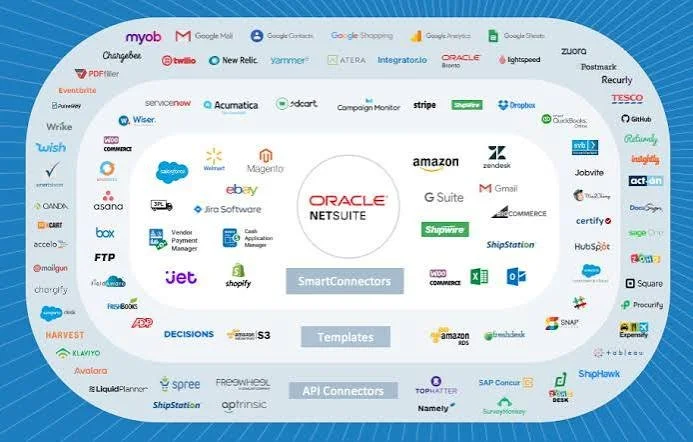
Source: NetSuite integration ecosystem graphic.
AI does not remove the partner layer. It raises demand for both implementation and orchestration, managed as a solution. Every agent, connector and workflow that touches the ledger needs to be set up, governed and run. The partner who owns that orchestration, and charges for the outcome, owns the client.
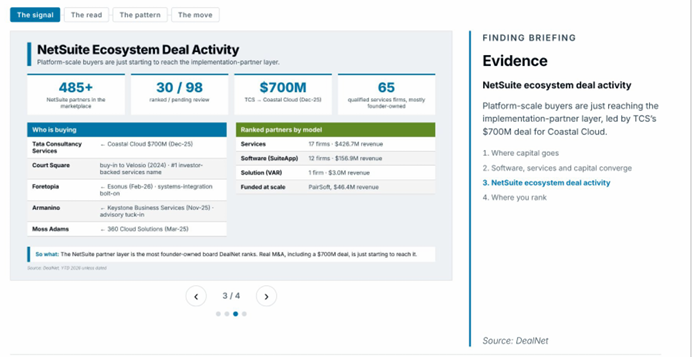
Software, services and capital converge on ERP partners, 2025–26
| Buyer / investor | Target | Move |
|---|---|---|
| Tata Consultancy Services | Coastal Cloud | Services buys a NetSuite + Salesforce partner ($700M, Dec 2025) |
| Armanino | Keystone Business Services | CPA-led services buys a NetSuite provider (Nov 2025) |
| Longshore Capital Partners | Enavate | PE invests in a Microsoft ERP partner (Dec 2025) |
| Foretopia | Esonus | Buys a NetSuite systems integrator (Feb 2026) |
| Innovia Consulting | 365 Vertical / 365 Cannabis | Services buys ERP software (Feb 2026) |
| Velosio (Court Square) | Acuitas | PE-backed ERP partner adds services (Jul 2026) |
| Consero Global | Waxman Associates; Pro Visio | Solution provider rolls up outsourced accounting |
Source: DealNet; company announcements.
The market math
| Metric | What it means |
|---|---|
| 485+ | NetSuite partners in the marketplace; SuiteWorld exhibitors grew from 45 (2021) to 137 (2024) |
| 0.96x | Size gap: ~$0.89B for the top 10 investor-backed services partners vs. ~$0.93B for the top 10 private. The private leaders are still bigger; capital has not reached them yet |
| 2X | Solutions are 2X more profitable than services alone |
| $77B → $157B | Global ERP software market, 2025 to 2033 |
Source: DealNet, YTD October 2026; SuiteWorld exhibitor lists 2021–2024.
Investor-backed NetSuite services partners: top 10
| # | Company | Revenue |
|---|---|---|
| 1 | Riveron | $268M |
| 2 | Net at Work | $147M |
| 3 | Velosio | $122M |
| 4 | ScaleNorth | ~$100M |
| 5 | Consero Global | ~$100M |
| 6 | Bridgepoint Consulting | $71M |
| 7 | Netgain Solutions | $32M |
| 8 | inDinero | $22M |
| 9 | SaaS Consulting Group | $19M |
| 10 | SquareWorks Consulting | $13M |
| Top 10 combined (avg $89M · median $85.5M) | ~$0.89B |
Services partners only. Wipfli excluded. Private rankings, including yours, are in the full briefing. Source: DealNet.
Top AI use cases on the SuiteWorld agenda, ranked by ROI
All five A-grade use cases are Office of the CFO delivery work: close, global F&A and payroll, and matching. That is where AI cuts the most labor, and where partners that deliver globally, people plus AI, earn the premium.
| # | AI use case | NetSuite feature | ROI | Partner opportunity |
|---|---|---|---|---|
| 1 | Continuous close | EPM Reconciliation Agent; Autonomous Close agents | A | Managed continuous close |
| 2 | AI-run close across subsidiaries | Intelligent Close Manager | A | Close redesign plus managed close |
| 3 | Global F&A delivery: AP, AR, GL across entities | OneWorld + AI matching and agents | A | F&A outsourcing, AI-plus-people delivery |
| 4 | Global payroll delivery into the GL | Payroll integrations; AI reconciliation | A | Global payroll and EOR tied to the ledger |
| 5 | Bank feed to GL matching | AI bank transaction matching | A | Outsourced accounting efficiency |
| 6 | Planning and variance in plain language | EPM Planning Agent | B | FP&A services and software |
| 7 | Margin-based pricing by segment | AI-assisted Advanced Pricing | B | Pricing and usage billing setup |
| 8 | Faster implementations with AI | SuiteScript AI Assistant; partner AI tools | B | Fixed-fee projects; partner-built agents |
| 9 | Board and management narratives | AI-generated report narratives | B | Fractional CFO and reporting |
| 10 | Ask your ERP in plain language | NetSuite Next, Ask Oracle | C | NetSuite Next adoption |
| 11 | Customer 360 summaries | AI Customer 360 summaries | C | CRM-to-ERP integration |
| 12 | Custom agents in SuiteApps | SuiteAgent, AI Toolkits, AI Connector Service (MCP) | C | SuiteApp IP that re-rates a partner |
ROI grade is an analyst assessment of hours replaced, task frequency and direct margin impact. AI governance (role-based access, approvals, audit trail, human review) sits under every use case. Source: Oracle NetSuite SuiteConnect 2026 announcements; SuiteWorld 2026 agenda and sponsor sessions.
Close is where the money is going
About 12 to 1. Since January 2025, the close and ledger companies we track raised about $341M in disclosed rounds: Rillet $70M (Aug25) and $100M (Aug26), DualEntry $90M (Oct25), Numeric $51M (Nov25) and Maxima $30M (Nov25). The AP and AR companies on the same list raised about $28M over the same stretch.
AP and AR already have funded leaders, Tipalti, HighRadius and Ottimate, whose big rounds landed in 2021–23. Close is the open category. The agent sits on top of the ledger, it is the highest-ROI AI use case on the SuiteWorld agenda, and three of the early-stage close players (Ledge, Maxima, Lumera) run on NetSuite. Ledge is a certified SuiteApp partner at SuiteWorld this week.
SuiteWorld put the close on the main stage. NetSuite demoed its Intelligent Close workspace and said some customers have cut the close from about 20 days to 2–3 (NetSuite product keynote, Oct26). Futurum's Keith Kirkpatrick named the gap partners can fill: “Whether finance teams will trust agents with the close remains the open question” (Futurum, Oct26).
For NetSuite partners, the close agent is the next SuiteApp to own, partner with or buy. The partner who runs continuous close as a managed service owns the client.
Funding by module
| Module | Early-stage companies | Early-stage raised | Raised since Jan25* | Investor-backed leaders (total raised) |
|---|---|---|---|---|
| Close and ledger | Ledge, Maxima, Artifact, Lumera; DualEntry (AI-native ERP) | $154M+ | ~$341M | FloQast $281.5M; Rillet $208.7M; Numeric $89M |
| AP and global F&A | OpenEnvoy, Hyperbots, Itemize, DOKKA | ~$34M | ~$6.5M | Tipalti $690M; Ottimate $164M; Stampli $142.7M |
| AR and order-to-cash | Fazeshift, Upflow, Growfin.ai, Ardina AI | ~$56M | ~$21M | HighRadius $475M |
| Audit and reporting | Trullion | $30M | — | — |
*Disclosed rounds since Jan 2025 across early-stage companies and leaders in each module. Close and ledger: Rillet, DualEntry, Numeric, Maxima. AP: Hyperbots. AR: Fazeshift. Undisclosed rounds (Ledge Series A, Ardina AI, Lumera) not counted. Source: Grata; company announcements; DealNet.
Top 5 early-stage ERP, by total raised
| # | Company | Module | Raised | Latest signal |
|---|---|---|---|---|
| 1 | DualEntry | Close and ledger (AI-native ERP) | $100M+ | Oct26: Deel partnership; $6M ERP Rescue Fund to switch off legacy ERP |
| 2 | Maxima | Close | ~$41M | Jun26: launched Max agent; $400B+ transaction volume |
| 3 | Trullion | Audit and reporting | $30M | Jul26: operator CEO; BDO Alliance channel push |
| 4 | Upflow | AR and order-to-cash | $25M+ | Apr26: MCP server; 70%+ of customers use AI daily |
| 5 | Fazeshift | AR and order-to-cash | $22M | May26: $17M Series A; revenue up 12x YoY |
Early stage per Grata funding stage. Source: Grata; company announcements.
Top 5 investor-backed market leaders, by total raised
| # | Company | Module | Raised | Latest round |
|---|---|---|---|---|
| 1 | Tipalti | AP and global payables | $690M | Last round May23 |
| 2 | HighRadius | AR and order-to-cash | $475M | Last round Mar21 |
| 3 | FloQast | Close | $281.5M | Last round Apr24 |
| 4 | Rillet | Close and ledger (AI-native ERP) | $208.7M | Aug26: $100M Series C at $1B valuation |
| 5 | Ottimate | AP | $164M | Last round Nov21 |
Private, investor-backed; excludes PE platforms and public companies. Source: Grata; company announcements.
Who is winning: contenders to watch
The companies below each own one layer of the autonomous suite and charge for the outcome. Each carries a dated proof point; the podium stays open until results are proven.
| Company | Layer it owns | AI revenue model | Proof point |
|---|---|---|---|
| Celigo | Orchestration | Integration platform plus AI agents, subscription | SuiteCloud Partner of the Year (2024); 5,000+ joint NetSuite customers |
| DualEntry | AI-native ERP, ledger | Subscription | $90M raised (Oct25) |
| Rillet | AI-native ERP, close and ledger | Subscription | $100M Series C at a $1B valuation; 600+ customers (Aug26) |
| Tabs | Billing for AI revenue models | Usage, credits and outcome billing | $55M Series B led by Lightspeed (Sep25); Statsig tripled invoice volume with no added headcount |
| Vayu Finance | Usage billing and revenue ops on NetSuite | Usage-based billing | SuiteWorld 26 session: Narmi moved from hand-tracked 60-page contracts to automatic usage billing (Oct26) |
| Zone & Co | SuiteApps: billing, reporting, payroll | Subscription SuiteApps | 4 NetSuite partner acquisitions, latest Solution 7 (May24) |
Analyst selection, A–Z. Source: company announcements; DealNet; SuiteWorld 26 sessions.
What's inside the full briefing
- Market map rankings index. Your exact position against private, early-stage and investor-backed peers.
- Deal partner market map. Sponsors and strategics, ranked, with your options.
- Corporate development best playbook. The moves creating value right now.
- Profit strategies for the next 2 years. Where AI, convergence and consolidation pay off.
Founder questions, answered
Who is buying NetSuite partners?
Software, services and capital are all buying. TCS bought Coastal Cloud for $700M, Armanino bought Keystone Business Services, Foretopia bought Esonus, Innovia bought 365 Vertical and Velosio added Acuitas.
What multiple does an ERP or NetSuite partner deal get?
The median disclosed ERP deal is 5.15x EV/revenue in DealNet coverage. Partners that own software IP and deliver solutions price higher than hours-only services firms.
How does a NetSuite partner earn a higher multiple?
Own software IP and deliver the outcome as a solution, not just hours. Solutions are about 2X more profitable than services alone, and buyers pay for that margin.
Is AI replacing NetSuite partners?
No. AI raises demand for both implementation and orchestration, managed as a solution. The risk is staying an hours-only shop while buyers pay for a solution.
Read more
- ERP in the AI Era: The Seven Findings Reshaping Backoffice Finance
- NetSuite Ecosystem Findings Briefing Preview
Sources: DealNet; NetSuite SuiteWorld 26 keynotes and press releases; Oracle Q4 FY26 results and Investor Day 2026; Futurum; diginomica; Computer Weekly; Enterprise Times; CPA Practice Advisor; iTWire; International FinTech; BILL; Billtrust; company announcements.
